



 Chat with AI
Exam 12: Intangibles

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


Purchased goodwill is the difference between the acquisition price of an acquired company and the fair value of its identifiable net assets.

Free
(True/False)
4.8/5  (90)
(90) Correct Answer: Verified
True
An identifiable intangible asset that has a finite life is not amortized but is periodically reviewed for impairment.
Free
(True/False)
4.7/5 (83)
(83) Correct Answer:Verified
VerifiedFalse
At the date of purchase, materials, equipment, facilities, and intangibles purchased from others that have no alternative future uses in research and development or other activities should be
Free
(Multiple Choice)
4.8/5 (74)
(74) Correct Answer:Verified
VerifiedC
During 2016, Quartz, Inc. developed a new financial accounting software package for sale. The company spent
$15,000,000 on the system, 30% of which was incurred prior to technological feasibility being established. The package was put on sale January 1, 2017, and the company estimates that over the five-year life of the package it will generate $100 million in sales. During 2017, sales amounted to $30 million.
Required:
a. Prepare the journal entry to record the development costs incurred in 2016.
b. Compute the amortization expense of the capitalized software costs for 2017.
(Essay)
4.8/5 (80)
(80) GAAP requires that research and development costs be expensed and that purchased goodwill be capitalized and not be amortized.
Required:
From a conceptual viewpoint, discuss the validity of the different treatments for these two types of expenditures.
(Essay)
4.8/5 (87)
(87) Identifiable intangible assets would include all of the following except
(Multiple Choice)
4.9/5 (77)
(77) Burger Prince incurred the following costs during 2017 in the development and production of a new product:
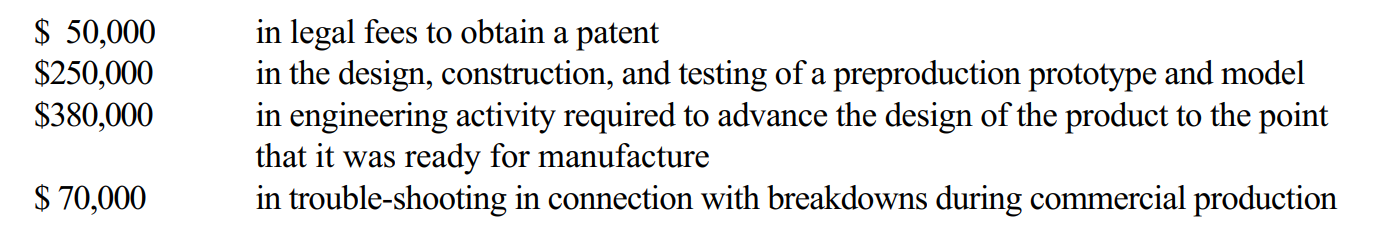 How much should be included in R&D expense for 2017?
 (Multiple Choice)
4.9/5 (89)
(89) Which of the following is not a required disclosure regarding goodwill for each period a company presents a balance sheet?
(Multiple Choice)
4.8/5 (84)
(84) In January 2014, Western Co. purchased a patent for $750,000 that had an estimated remaining economic life of ten years. On January 2, 2017, the company incurred $140,000 in legal fees to successfully defend the validity of the patent. In January 2019, the company incurred $88,000 in legal fees in a new infringement lawsuit. In this situation, the lawsuit was lost, and the patent was determined to be worthless as a result. What is the expense to be recognized in 2019 by Western with regard to the patent?
(Multiple Choice)
4.8/5 (79)
(79) The Shane Company began business early in 2016, when Shane paid an initial fee of $100,000 to purchase a franchise. In forming the company, Shane also spent $11,000 on legal fees and $4,500 on accounting fees. During the year, Shane spent $7,500 on product development and paid $10,000 in continuing franchise fees. What amount should Shane capitalize for intangible assets in 2016?
(Multiple Choice)
4.8/5 (73)
(73) The Clementine Company agreed to purchase the Orange Company for $650,000. At the date of purchase, Orange had current assets with a fair market value of $400,000, noncurrent assets including no marketable securities) with a fair market value of $700,000, and liabilities of $500,000. In accounting for this transaction, Clementine should
(Multiple Choice)
4.9/5 (86)
(86) The Lane Company incurred the following expenditures in January 2016: 1) research and development costs of $510,000 that resulted in a new product that was patented during the year, 2) $12,000 in legal fees to have the patent registered, 3) $100,000 in advertising costs to develop a trademark for the newly patented product, 4) Legal fees of $8,000 incurred with the registration of the trademark, which will only be used for five years, and 5) $25,000 of advertising costs to promote its good name. Benefits to be derived from the patent are expected to last for five years. The president believes the promotion of Lane's good name will benefit the firm for three years. How much amortization expense should Lane recognize for 2016?
(Multiple Choice)
4.8/5 (62)
(62) Which of the following groups would be classified as intangible assets for financial accounting and reporting purposes?
(Multiple Choice)
4.9/5 (76)
(76) If a research and development cost has alternative future uses, then the company
(Multiple Choice)
4.8/5 (81)
(81) At the date of purchase, materials, equipment, facilities, and intangibles purchased from others that have alternative future uses in research and development should be
(Multiple Choice)
4.8/5 (75)
(75) Because goodwill only produces cash flows in connection with other assets, it is tested for impairment within the context of its reporting unit. Assume that an assessment of qualitative factors indicates that it is more likely than not that the fair value of the reporting unit is less than its carrying value, describe the ensuing two-step quantitative impairment test.
Required:
Briefly describe the process for testing for impairment of goodwill.
(Essay)
4.8/5 (80)
(80) Technological feasibility of software products is established when the product is ready for general use.
(True/False)
4.9/5 (77)
(77) The Mario Company was organized at the end of 2015. The following items acquired on January 1, 2016, were listed by the company as intangible assets at the end of 2016: 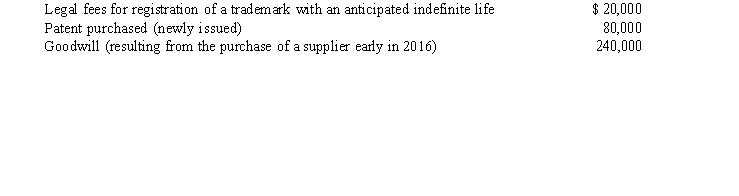 At the beginning of 2016, Mario also purchased a research building at a cost of $275,000. The company estimates that the building will be used in numerous projects over a 20-year period. During the year, Mario spent $75,000 on research and development materials and salaries. In early January 2016, Mario purchased a patent for $75,000 that was used exclusively for a single research project conducted during 2016. Mario uses straight-line amortization over the maximum allowable periods. In addition, on July 1, 2016, Mario incurred legal fees of $25,400 to defend the new patent that had been acquired for $80,000. Mario's lawyers were successful in the defense of the patent.
Required:
Determine the amortization expense for intangibles for 2016. Mario calculates amortization expense to the nearest month.
At the beginning of 2016, Mario also purchased a research building at a cost of $275,000. The company estimates that the building will be used in numerous projects over a 20-year period. During the year, Mario spent $75,000 on research and development materials and salaries. In early January 2016, Mario purchased a patent for $75,000 that was used exclusively for a single research project conducted during 2016. Mario uses straight-line amortization over the maximum allowable periods. In addition, on July 1, 2016, Mario incurred legal fees of $25,400 to defend the new patent that had been acquired for $80,000. Mario's lawyers were successful in the defense of the patent.
Required:
Determine the amortization expense for intangibles for 2016. Mario calculates amortization expense to the nearest month. (Essay)
5.0/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)