



 Chat with AI
Exam 19: Accounting for Post-Retirement Benefits

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


Exhibit 19-01
Marley Co. has an underfunded prepaid/accrued pension cost of $2,000 debit balance) at December 31, 2015. The following information pertains to 2016: 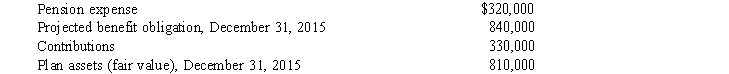 -Refer to Exhibit 19-1. The December 31, 2016, adjusting entry should be

-Refer to Exhibit 19-1. The December 31, 2016, adjusting entry should be
(Short Answer)
4.9/5  (78)
(78) What three methods are available to provide guidance for companies to recognize gains or losses in pension expense?
(Essay)
4.9/5 (87)
(87) Joan, Inc. started a pension plan on January 1, 2016. At that date, prior service cost of $1,100,000 was recognized as a result of prior service credit granted to existing employees. At December 31, 2016, the following information was available: 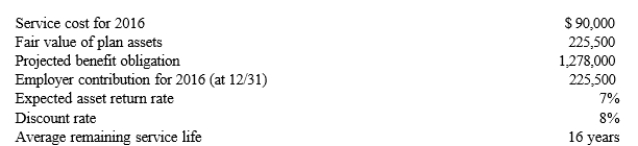 Required:
a. Compute the pension expense for 2016.
b. Prepare appropriate journal entries for 2016.
Required:
a. Compute the pension expense for 2016.
b. Prepare appropriate journal entries for 2016. (Essay)
4.8/5 (85)
(85) Current GAAP requires that a company with a defined benefit pension plan disclose a reconciliation of the beginning and ending balances of the projected benefit obligation.
Required:
State the items that must be included in this disclosure.
(Essay)
4.8/5 (83)
(83) The defined benefit plan is a type of plan in which the employer's contribution into the pension fund is based on a formula.
(True/False)
5.0/5 (76)
(76) John Company adopted a defined benefit pension plan on January 1, 2015, and prior service credit was granted to employees. The present value of that prior service obligation as of January 1, 2015 was $1,400,000 and is being amortized by the straight-line method over the remaining 20-year service life of the company's active employees. Additional information relating to the company's pension plan for 2015 is presented below: 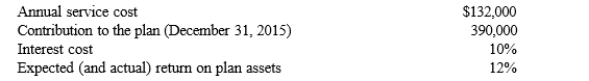 What amount should be recorded in Prepaid/Accrued Pension Cost when recording the 2015 pension expense and funding at December 31, 2015?
 (Multiple Choice)
4.8/5 (79)
(79) Define the following:
expected postretirement benefit obligation EPBO)
accumulated postretirement benefit obligation APBO)
(Essay)
4.9/5 (77)
(77) With respect to the process of assigning the cost of postretirement benefits to periods of employee service, attribution period ends at
(Multiple Choice)
4.8/5 (71)
(71) Which of the following is not one of the pension expense components that a company recognizes?
(Multiple Choice)
4.9/5 (69)
(69) In June 2011, the IASB amended IAS 19, Employee Benefits, and significantly changed the method of accounting for defined benefit plan pensions. Regarding these changes, which of the following statements is false?
(Multiple Choice)
4.8/5 (83)
(83) The Lucas Company offers employees a defined contribution pension plan. In 2015, Lucas contributed $175,000 to the plan, which paid $195,000 to retired employees. Which of the following statements is true?
(Multiple Choice)
4.8/5 (75)
(75) The corridor is defined as 10% of the greater of the beginning of the year projected benefit obligation or the end of the year fair value of the plan.
(True/False)
4.9/5 (91)
(91) With respect to the process of assigning the cost of postretirement benefits to periods of employee service, the attribution period starts on the
(Multiple Choice)
4.9/5 (87)
(87) Current GAAP regarding employers' accounting for defined benefit pension plans defines a pension plan as being underfunded at the end of the period when the
(Multiple Choice)
4.8/5 (77)
(77) In the computation of pension expense, interest cost is the
(Multiple Choice)
4.9/5 (91)
(91) Which of the following pension-related definitions is not correct?
(Multiple Choice)
4.7/5 (103)
(103) Amortization of any net gain or loss is included in pension expense of a given year if at the
(Multiple Choice)
4.9/5 (82)
(82) What are the three major differences between the accounting for pensions and the accounting for other
Postretirement Benefits OPRB's)?
(Essay)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)