



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


The intraperiod tax allocation involves separation of the income taxes on income from continuing operations from income taxes on discontinued operations and other comprehensive income.
(True/False)
4.9/5  (87)
(87) The following information relates to the Kill Devil Hills Company for the year ending December 31, 2016: 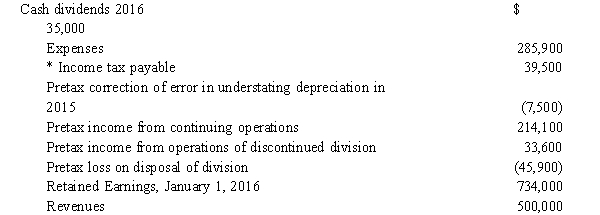 * Of this amount $4,800 relates to the pretax income from the operations of discontinued division; pretax loss on the
disposal of division resulted in a tax savings of $13,350; and pretax correction of the depreciation error resulted in a tax savings of $1,500.
Required:
1) Prepare the year end journal entry necessary to record the 2016 intraperiod income tax allocation.
2) Prepare Kill Devil Hill's 2016 income statement and statement of retained earnings.
* Of this amount $4,800 relates to the pretax income from the operations of discontinued division; pretax loss on the
disposal of division resulted in a tax savings of $13,350; and pretax correction of the depreciation error resulted in a tax savings of $1,500.
Required:
1) Prepare the year end journal entry necessary to record the 2016 intraperiod income tax allocation.
2) Prepare Kill Devil Hill's 2016 income statement and statement of retained earnings. (Essay)
4.8/5 (78)
(78) What conclusion did the FASB come to in regards to GAAP for the financial reporting of operating loss carrybacks and carryforwards?
(Essay)
4.9/5 (77)
(77) Under IFRS ,valuation allowances for deferred tax assets are not recorded.
(True/False)
4.9/5 (87)
(87) At the end of its first year of operations on December 31, 2016, the GAC Company reported taxable income of
$30,000 and a pretax financial loss of $40,000. Differences between taxable income and pretax financial income included estimated bad debt expense for which accounts were expected to be written off in 2017, $20,000, and warranty costs expensed for accounting purposes in excess of cash paid for warranty claims, $50,000. The warranty costs are expected to be paid in 2017. The enacted tax rate for 2016 and 2017 is 30%.
Required:
a. Prepare the income tax journal entry for the GAC Company on December 31, 2016, assuming that it is more likely than not that the deferred tax asset will be realized.
b. Prepare the income tax journal entry for the GAC Company on December 31, 2016, assuming that it is more likely than not that 40% of the deferred tax asset from the warranty costs will not be realized.
(Essay)
4.9/5 (82)
(82) Jefferson Corporation reported the following pretax and taxable income items from 2016: 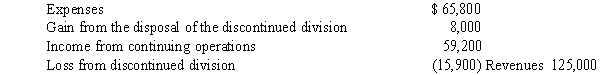 Required:
1) Prepare the journal entries for 2016 to record the intraperiod income tax allocation. The tax rate for the first
$30,000 of income is 15%? the tax rate thereafter is 35%.
2) Prepare the 2016 income statement for Jefferson Corporation. Heading is not necessary)
Required:
1) Prepare the journal entries for 2016 to record the intraperiod income tax allocation. The tax rate for the first
$30,000 of income is 15%? the tax rate thereafter is 35%.
2) Prepare the 2016 income statement for Jefferson Corporation. Heading is not necessary) (Essay)
4.8/5 (84)
(84) Which one of the following transactions would result in the creation of a noncurrent deferred tax liability?
(Multiple Choice)
4.8/5 (70)
(70) At the end of its first year of operations on December 31, 2016, the Brandon Company reported taxable income of $100,000 and had a pretax financial loss of $60,000. Differences between taxable income and pretax financial income included interest revenue received from municipal obligations of $20,000 and warranty expense accruals of
$180,000. Warranty expenses of $90,000 are expected to be paid in 2017 and $110,000 in 2018. The enacted income tax rates for 2016, 2017, and 2018 are 30%, 35%, and 40%, respectively. The journal entry to record income tax expense on December 31, 2016, would be 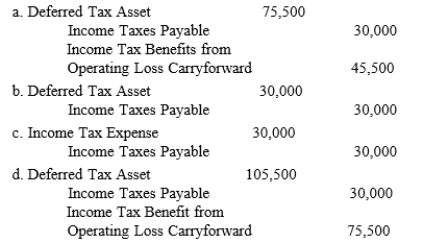
(Short Answer)
4.9/5 (67)
(67) At the end of the current year, Brothers company claims a $225,000 tax credit on its income tax return. Brothers is uncertain about whether the IRS will accept the credit. After some research it is determined that the IRS may not accept all of the tax credit. Brothers estimates the likelihood using the following probability distribution: 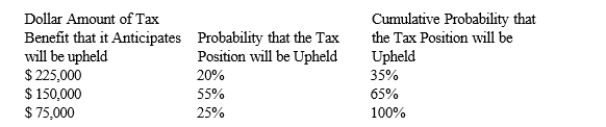 Required:
For the current year determine:
1) the amount Brothers will be able to recognize as a current tax benefit
2) the amount that will be record as the unrecognized tax benefit.
Required:
For the current year determine:
1) the amount Brothers will be able to recognize as a current tax benefit
2) the amount that will be record as the unrecognized tax benefit. (Essay)
4.8/5 (83)
(83) A deferred tax asset arises when current taxable income is greater than pretax financial income.
(True/False)
4.9/5 (77)
(77) Revenue from installment sales is recognized in the period received for tax purposes and recognized in the period earned for accounting purposes. If these periods are different, this is an example of a
(Multiple Choice)
4.9/5 (89)
(89) All of the following involve a temporary difference for purposes of income tax allocation except
(Multiple Choice)
4.8/5 (73)
(73) The Wyatt Company reports the following for both pretax financial and taxable income: 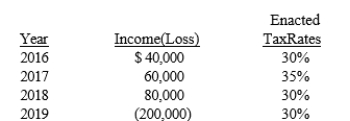 Wyatt uses the carryback provision for net operating losses when possible. Congress has enacted a tax rate for 2020 and future years of 40%. The entry on December 31, 2019, to record income tax expense would include a
 (Multiple Choice)
4.9/5 (93)
(93) The presentation of the combination or "offsetting" of noncurrent deferred tax assets and liabilities is
(Multiple Choice)
4.9/5 (86)
(86) Which of the following transactions would typically result in the creation of a deferred tax liability?
(Multiple Choice)
4.8/5 (77)
(77) Compare and contrast interperiod and intraperiod tax allocation methods.
(Essay)
4.7/5 (79)
(79) GAAP require intraperiod income tax allocation to income or loss as they relate to discontinued operations and other comprehensive income but not to retrospective adjustments or prior period adjustments.
(True/False)
4.9/5 (93)
(93) Deferred tax liabilities and deferred tax assets must be reported on the balance sheet.
Required:
Explain the procedure for classifying and reporting deferred tax liabilities and deferred tax assets.
(Essay)
4.8/5 (69)
(69) Moore Company reported the following operating results during its first three years of operations: 2016 Pretax operating loss $ (40,000)
2017 Pretax operating loss $(200,000)
2018 Pretax operating income $ 300,000
No permanent or temporary differences occurred during these fiscal periods. Assuming an income tax rate of 35%, what is the amount of current income tax liability that Moore should report as of December 31, 2018?
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)