



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


Pruett Corporation began operations in 2015 and appropriately recorded a deferred tax liability at the end of 2015 and 2016 based on the following depreciation temporary differences between pretax financial income and taxable income: 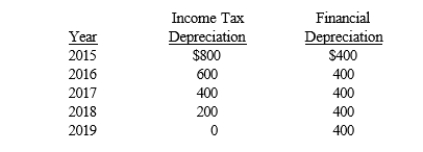 The income tax rate for 2015 and 2016 was 30%. In February 2017, due to budget constraints, Congress enacted an income tax rate of 35%. What is the journal entry required to adjust the Deferred Tax Liability account in February 2017?
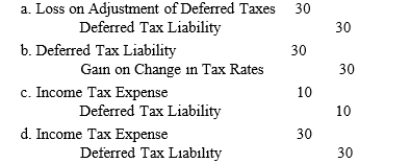
The income tax rate for 2015 and 2016 was 30%. In February 2017, due to budget constraints, Congress enacted an income tax rate of 35%. What is the journal entry required to adjust the Deferred Tax Liability account in February 2017? (Short Answer)
4.8/5  (65)
(65) Assuming there are no prior period adjustments during the fiscal year, net income would be affected by 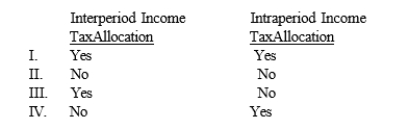
(Multiple Choice)
4.9/5 (70)
(70) The value of deferred tax assets and liabilities should be measured using the enacted tax rates that will be in existence when the temporary differences initially occur.
(True/False)
4.9/5 (77)
(77) Combining the net deferred tax asset and liability amounts in the noncurrent group is one of the few situations in which GAAP allow offsetting assets and liabilities.
(True/False)
4.7/5 (72)
(72) At December 31, 2016, the Blue Agave Company had a current deferred tax asset of $60,000, arising from cash for magazine subscriptions received and taxed in 2016 but that will be recognized as income for accounting purposes in
2017; a noncurrent deferred tax liability of $160,000 arising from an excess of MACRS tax depreciation over straight-line accounting depreciation of plant assets; and a long-term deferred tax asset of $80,000, arising from contingency expenses for accounting purposes that will be tax deductible when paid estimated to be in 2018). The
2017 pretax financial income and taxable income for Blue Agave are as follows: 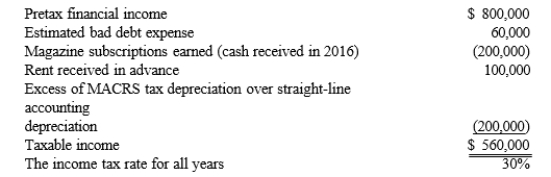 Required:
Prepare the income tax journal entry for the Blue Agave Company at the end of 2017.
Required:
Prepare the income tax journal entry for the Blue Agave Company at the end of 2017. (Essay)
4.7/5 (95)
(95) The Pink Diamonds Company installs fire alarm systems for large manufacturing enterprises and golf courses. Due to the design of their systems, some projects frequently extend over a two-year period. Pink Diamonds uses the percentage-of-completion method for financial accounting purposes and the completed-contract method for tax purposes. As of December 31, 2016, all projects were completed. The following information relates to projects started but not completed as of December 31, 2017: 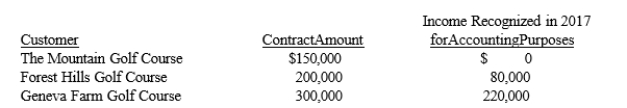 Assuming an income tax rate of 30%, what amount should be included in the deferred tax liability account at December 31, 2017?
 (Multiple Choice)
4.9/5 (95)
(95) At the end of its first year of operations on December 31, 2016, the Mojave Company reported pretax financial income of $100,000. An investigation of that income revealed the following items:
· Bad debts expense of $12,000 was recognized. The accounts will be written off in 2017.
· Installment sales of $50,000 were recognized in financial income. These sales were accounted for by the installment sales method for income tax purposes. Only $20,000 was reported on the tax return.
· Warranty expenses of $16,000 were accrued for financial reporting purposes, but were not expected to result in a cash payment until 2017.
· Depreciation on the tax return exceeded depreciation for financial reporting purposes by $32,000.
Assume that any deferred tax assets are considered more likely than not to be realized. The enacted income tax rate for all years is 25%.
Required:
a. Compute taxable income.
b. Prepare the entry to record income tax expense and any related assets and liabilities for
Mojave on December 31, 2016.
(Essay)
5.0/5 (62)
(62) Which of the following statements regarding current and deferred income taxes is not correct?
(Multiple Choice)
4.8/5 (67)
(67) A corporation must report its deferred tax liabilities and assets in two classifications: gross current amounts and gross noncurrent amounts.
(True/False)
4.8/5 (78)
(78) Briefly describe the four major differences between IFRS and GAAP in the measurement procedures used in accounting for deferred income taxes.
(Essay)
4.7/5 (86)
(86) Each of the following can result in a temporary difference between pretax financial income and taxable income except
(Multiple Choice)
4.8/5 (72)
(72) What two objectives did the FASB identify for accounting for income taxes?
(Essay)
4.8/5 (89)
(89) Using accelerated depreciation for tax purposes and straight-line method for book purposes results in a deferred tax asset.
(True/False)
4.7/5 (71)
(71) Lewes Company appropriately uses the installment sales method for tax purposes and the accrual method for revenue recognition for accounting purposes. Pertinent data at December 31, 2016, the close of the first year of operations, are as follows: 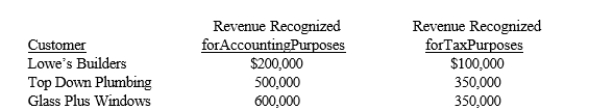 Lewes's tax rate is 30%. What amount should be included in the deferred tax account at December 31, 2016 for these installment sales?
 (Multiple Choice)
4.7/5 (76)
(76) When Congress changes the tax laws or rates, a corporation's deferred tax liability and asset accounts
(Multiple Choice)
4.9/5 (72)
(72) What should a corporation disclose for the provisions for income taxes and the effective tax rates?
(Essay)
4.7/5 (96)
(96) On December 31, 2016, the Town Hall Company had a deferred tax liability balance of $12,570, arising from an excess of MACRS depreciation for tax purposes over straight-line depreciation for accounting purposes. The tax effects of that timing difference are expected to reverse in the following years:  On January 27, 2017, Congress raised the effective income tax rate to 38% for all future years, including the current year, 2017.
Required:
Prepare the entry to record any adjustments necessary due to the income tax rate increase on January 27, 2017.
On January 27, 2017, Congress raised the effective income tax rate to 38% for all future years, including the current year, 2017.
Required:
Prepare the entry to record any adjustments necessary due to the income tax rate increase on January 27, 2017. (Essay)
4.7/5 (82)
(82) Exhibit 18-1
On December 31, 2015, Fredericksburg, Inc. had no temporary differences that created deferred income taxes. On January 2, 2016, a new machine was purchased for $30,000. Straight-line depreciation over a four-year life no residual value) was used for financial accounting. Depreciation expense for tax purposes was $11,000 in 2016,
$9,000 in 2017, $6,000 in 2018, and $4,000 in 2015. In each year, the income tax rate was 20% and Fredericksburg had no other items that created differences between pretax financial income and taxable income. Fredericksburg reported the following pretax financial income for 2016 through 2019: 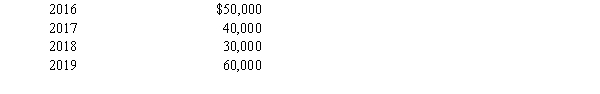 -Refer to Exhibit 18-1. The entry to record income taxes on December 31, 2017, would include a
 (Multiple Choice)
4.9/5 (84)
(84) Which of the following is not a timing difference that would cause pretax financial accounting income to differ from taxable income?
(Multiple Choice)
4.9/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)