



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


A corporation must recognize a valuation allowance if, based on available evidence, it is more likely than not that a deferred liability will not be realized.
(True/False)
4.8/5  (79)
(79) In applying intraperiod income tax allocation to discontinued operations, other comprehensive income, retrospective adjustments, and prior period adjustments, what tax rate should be used?
(Multiple Choice)
4.8/5 (94)
(94) The amount of income tax expense as determined by GAAP differs from amount determined under the Internal
Revenue Code due to measurement and timing.
(True/False)
4.9/5 (68)
(68) Which one of the following statements regarding operating losses is false?
(Multiple Choice)
4.8/5 (79)
(79) Match each item to its descriptive phrase by placing the appropriate letter in the space provided
Correct Answer: Verified
Premises:
Responses:
(Matching)
4.9/5 (86)
(86) Discuss what criteria a company should employ to determine whether a deferred tax asset is considered impaired or
"more likely than not" to be realized.
(Essay)
4.8/5 (77)
(77) What three groups are measuring and timing differences categorized?
(Multiple Choice)
4.9/5 (71)
(71) Lakeland Corporation reported the following pretax and taxable) information for 2016: 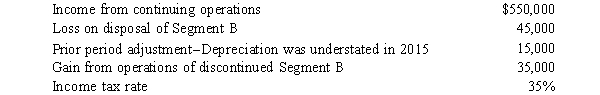 Required:
a. Prepare the lower portion of Lakeland's 2016 income statement, beginning with pretax income for continuing operations. Omit the heading.)
b. Prepare Lakeland's 2016 statement of retained earnings, assuming that retained earnings at January 1, 2016, was $750,000 and the company paid $45,000 of dividends in 2016. Omit the heading.)
Required:
a. Prepare the lower portion of Lakeland's 2016 income statement, beginning with pretax income for continuing operations. Omit the heading.)
b. Prepare Lakeland's 2016 statement of retained earnings, assuming that retained earnings at January 1, 2016, was $750,000 and the company paid $45,000 of dividends in 2016. Omit the heading.) (Essay)
4.8/5 (79)
(79) On December 31, 2015, Jefferson Lake, Inc. reported a deferred tax liability of $1,875, based on the following schedule of future taxable amounts and enacted tax rates: 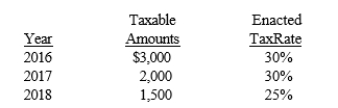 On February 7, 2016, Congress amended a previously passed tax law. The amendment changed the tax rate to 35%
for 2016 and all future years.
Required:
Prepare the income tax journal entry for Jefferson Lake, Inc. necessary on February 7, 2016.
On February 7, 2016, Congress amended a previously passed tax law. The amendment changed the tax rate to 35%
for 2016 and all future years.
Required:
Prepare the income tax journal entry for Jefferson Lake, Inc. necessary on February 7, 2016. (Essay)
4.8/5 (82)
(82) A temporary difference will result in a deferred tax liability when future taxable income will be less than future pretax financial income.
(True/False)
4.9/5 (77)
(77) Which of the following would not result in a permanent difference between pretax financial income and taxable income?
(Multiple Choice)
4.8/5 (74)
(74) In 2016, its first year of operations, Richmond Corporation reported pretax financial income of $80,000 for the year ended December 31. Richmond depreciates its fixed assets using an accelerated cost recovery method for tax purposes and straight-line depreciation for financial reporting. On assets acquired in 2016, the following are differences between depreciation on the tax return and accounting income during the asset's five-year life: 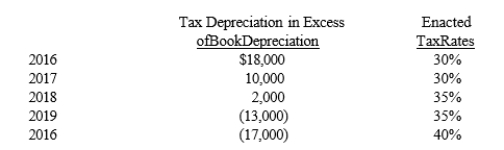 Assuming no other temporary or permanent differences, which of the following combinations of noncurrent deferred tax liabilitiy and income taxes payable would be included on Richmond's December 31, 2016 balance sheet?
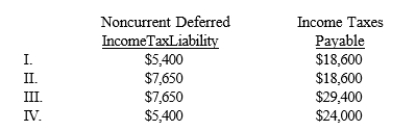
Assuming no other temporary or permanent differences, which of the following combinations of noncurrent deferred tax liabilitiy and income taxes payable would be included on Richmond's December 31, 2016 balance sheet? (Multiple Choice)
4.9/5 (84)
(84) When Congress makes a tax law or rate change, a corporation recognizes financial statement impact by adjusting the deferred assets or liabilities as of the beginning of the year in which the change is made.
(True/False)
4.9/5 (77)
(77) The acceptable balance sheet classifications for deferred tax assets and deferred tax liabilities under GAAP and IFRS are 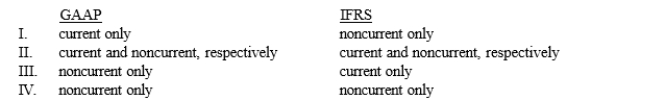
(Multiple Choice)
4.9/5 (76)
(76) A corporation's deferred tax expense or benefit is the change in its deferred tax liabilities or assets during the year.
(True/False)
4.8/5 (76)
(76) Which of the following statements appropriately describe the different effects of operating loss carrybacks and carryforwards?
(Multiple Choice)
4.9/5 (71)
(71) For the year ended December 31, 2016, the Bowling Green Company reported income of $350,000 before provision for income tax. In arriving at taxable income for income tax purposes, the following differences were identified: Bad debt expense but not written off) $ 8,000
Depreciation deducted for tax purposes in excess of
Depreciation for accounting purposes 50,000
Income for installment sales reportable for income tax purposes in excess of income reported for financial
Reporting purposes 30,000
Assuming a corporate income tax rate of 30%, Huntsville's current income tax liability as of December 31, 2016, is
(Multiple Choice)
4.8/5 (82)
(82) Fairfax Company had a balance in Deferred Tax Liability of $840 on December 31, 2016, resulting from depreciation timing differences. Differences in tax and accounting depreciation for assets purchased on January 1, 2016, are as follows: 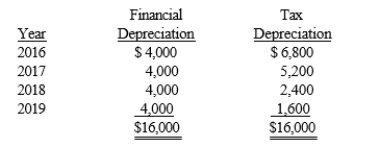 In addition to the 2016 depreciation timing difference, Fairfax Company expensed $2,000 of warranty costs that will be deducted for tax purposes when paid in future years. Fairfax's taxable income in 2016 was $35,000. The 2016 income tax rate was 35%, and no changes in the tax rate for future years have been enacted.
Required:
Prepare the income tax journal entry for the Fairfax Company for December 31, 2016.
In addition to the 2016 depreciation timing difference, Fairfax Company expensed $2,000 of warranty costs that will be deducted for tax purposes when paid in future years. Fairfax's taxable income in 2016 was $35,000. The 2016 income tax rate was 35%, and no changes in the tax rate for future years have been enacted.
Required:
Prepare the income tax journal entry for the Fairfax Company for December 31, 2016. (Essay)
4.8/5 (81)
(81) Which one of the following requires interperiod tax allocation?
(Multiple Choice)
5.0/5 (75)
(75) Shane Company uses an accelerated depreciation method for income tax purposes and the straight-line depreciation method for financial reporting purposes. As of December 31, 2016, Shane has a deferred tax liability balance related to depreciation temporary differences of $80,000. In 2017, depreciation for income tax purposes was $360,000, while depreciation for financial reporting purposes was $300,000. If the income tax rate is 30%, no other temporary or permanent differences exist, and taxable income is $400,000,which of the following would be included in the entry to record income tax expense on December 31, 2017?
(Multiple Choice)
4.9/5 (62)
(62) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)