



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


Smyrna Company had financial and taxable incomes as follows: 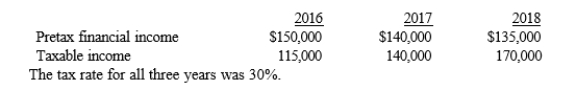 Required:
a. Prepare the journal entries to record income taxes for all three years.
b. Explain why the taxes paid in 2018 are different from the tax return and the amount reported in the financial statements and provide an example of what could cause this difference.
Required:
a. Prepare the journal entries to record income taxes for all three years.
b. Explain why the taxes paid in 2018 are different from the tax return and the amount reported in the financial statements and provide an example of what could cause this difference. (Essay)
4.8/5  (91)
(91) As of December 31, 2016, the Williamsburg Company reported a deferred tax asset of $60,000 related to accrued, unpaid warranty costs. However, since profits have been declining, Williamsburg decides that it is more likely than not that $24,000 of the deferred tax asset will not be realized. The entry to record the valuation allowance would include a
(Multiple Choice)
4.9/5 (81)
(81) When accounting for the current impact of loss carrybacks and carryforwards it is proper to recognize
(Multiple Choice)
4.9/5 (87)
(87) Life insurance proceeds payable to a corporation upon the death of an insured employee are an example of
(Multiple Choice)
4.9/5 (76)
(76) Interperiod tax allocation is required for all of the following situations except
(Multiple Choice)
4.9/5 (84)
(84) The Chance Company began operations in 2016 and, for that calendar year, reported an operating loss of $200,000. Due to sufficient verifiable positive evidence, no valuation allowance was established to reduce the deferred tax asset as of December 31, 2016. During 2017, Chance reported pretax accounting income of $375,000. Assuming an income tax rate of 35%, what should Chance record in 2017 as income tax payable at the end of 2017?
(Multiple Choice)
4.8/5 (70)
(70) The amount owed the IRS is recorded in the accounting records in which account?
(Multiple Choice)
4.9/5 (65)
(65) Port Deposit, Inc. reports the following deferred tax items at the end of 2016: 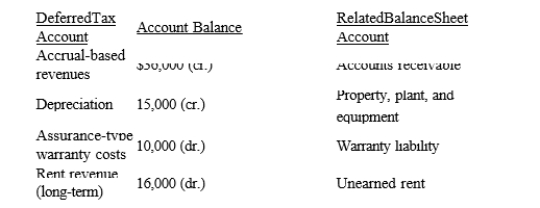 Required:
Show how the deferred tax items will be reported on the December 31, 2016 balance sheet.
Required:
Show how the deferred tax items will be reported on the December 31, 2016 balance sheet. (Essay)
4.7/5 (84)
(84) Differences between pretax financial accounting and taxable income that are expected to reverse in one or more future accounting periods are called
(Multiple Choice)
4.7/5 (68)
(68) What are the three types of permanent differences between a corporation's pretax financial income and taxable income?
(Short Answer)
4.9/5 (79)
(79) Which one of the following would require interperiod tax allocation?
(Multiple Choice)
4.8/5 (82)
(82) Deductions that are allowed for income tax purposes but do not qualify as expenses under GAAP are permanent differences.
(True/False)
4.9/5 (85)
(85) Delmarva Company, during its first year of operations in 2016, reported taxable income of $170,000 and pretax financial income of $100,000. The difference between taxable income and pretax financial income was caused by two timing differences: excess depreciation on tax return, $70,000; and warranty expenses in excess of warranty payments, $40,000. These two timing differences will reverse in the next three years as follows: 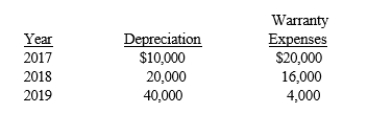 Enacted tax rates are 30% for 2016, 35% for 2017 and 2018, and 40% for 2019.
Required:
Prepare the income tax journal entry for Delmarva Company for December 31, 2016.
Enacted tax rates are 30% for 2016, 35% for 2017 and 2018, and 40% for 2019.
Required:
Prepare the income tax journal entry for Delmarva Company for December 31, 2016. (Essay)
4.7/5 (79)
(79) Permanent differences between pretax financial income and taxable income result when
(Multiple Choice)
4.8/5 (85)
(85) Intraperiod tax allocation would be appropriate for all of the following except
(Multiple Choice)
4.8/5 (77)
(77) Exhibit 18-1
On December 31, 2015, Fredericksburg, Inc. had no temporary differences that created deferred income taxes. On January 2, 2016, a new machine was purchased for $30,000. Straight-line depreciation over a four-year life no residual value) was used for financial accounting. Depreciation expense for tax purposes was $11,000 in 2016,
$9,000 in 2017, $6,000 in 2018, and $4,000 in 2015. In each year, the income tax rate was 20% and Fredericksburg had no other items that created differences between pretax financial income and taxable income. Fredericksburg reported the following pretax financial income for 2016 through 2019: 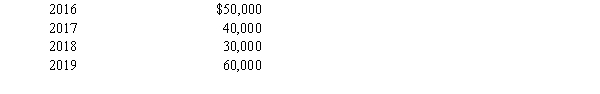 -Refer to Exhibit 18-1. The entry to record income taxes on December 31, 2018, would include a
 (Multiple Choice)
4.7/5 (84)
(84) Match each item to its descriptive phrase by placing the appropriate letter in the space provided
Correct Answer: Verified
Premises:
Responses:
(Matching)
4.8/5 (74)
(74) What two issues does a company need to consider in regards to operating loss carrybacks?
(Essay)
4.8/5 (73)
(73) Differences arising between financial accounting and tax accounting fall into three categories, what are the three categories?
(Short Answer)
4.9/5 (71)
(71) Which one of the following requires intraperiod tax allocation?
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)