



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models459 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes420 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care337 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance512 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs326 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets256 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income260 Questions
Exam 20: Unemployment and Inflation290 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles251 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies261 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run305 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money, Banks, and the Federal Reserve System278 Questions
Exam 26: Monetary Policy280 Questions
Exam 27: Fiscal Policy313 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy277 Questions
Exam 30: The International Financial System258 Questions
Select questions type


The delivery of first-class mail by the U.S. Postal Service is an example of
(Multiple Choice)
4.7/5  (86)
(86) In long-run perfectly competitive equilibrium, which of the following is false?
(Multiple Choice)
4.9/5 (77)
(77) What is meant by allocative efficiency? How does a perfectly competitive firm achieve allocative efficiency?
(Essay)
4.9/5 (71)
(71) Table 12-3
 Arnie sells basketballs in a perfectly competitive market. Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC) and marginal cost (MC).
-Refer to Table 12-3. What price (P) will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50?
Arnie sells basketballs in a perfectly competitive market. Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC) and marginal cost (MC).
-Refer to Table 12-3. What price (P) will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50? (Multiple Choice)
4.9/5 (75)
(75) Figure 12-18 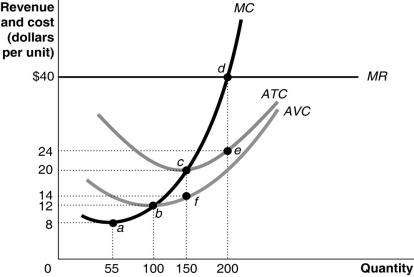 -Refer to Figure 12-18. Use the figure above to answer the following questions.
a. How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b. What is the market price?
c. What is the profit-maximizing output?
d. What is total revenue at the profit-maximizing output?
e. What is the total cost at the profit-maximizing output?
f. What is the profit or loss at the profit-maximizing output?
g. What is the firm's total fixed cost?
h. What is the total variable cost?
i. Identify the firm's short-run supply curve.
j. Is the industry in a long-run equilibrium?
k. If it is not in long-run equilibrium, what will happen in this industry to restore long-run equilibrium?
l. In long-run equilibrium, what is the firm's profit maximizing quantity?
-Refer to Figure 12-18. Use the figure above to answer the following questions.
a. How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b. What is the market price?
c. What is the profit-maximizing output?
d. What is total revenue at the profit-maximizing output?
e. What is the total cost at the profit-maximizing output?
f. What is the profit or loss at the profit-maximizing output?
g. What is the firm's total fixed cost?
h. What is the total variable cost?
i. Identify the firm's short-run supply curve.
j. Is the industry in a long-run equilibrium?
k. If it is not in long-run equilibrium, what will happen in this industry to restore long-run equilibrium?
l. In long-run equilibrium, what is the firm's profit maximizing quantity? (Essay)
5.0/5 (81)
(81) Table 12-1
 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1. If the market price of each camera case is $8 and the firm maximizes profit, what is the amount of the firm's profit or loss?
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1. If the market price of each camera case is $8 and the firm maximizes profit, what is the amount of the firm's profit or loss? (Multiple Choice)
4.8/5 (88)
(88) Perfectly competitive industries tend to produce low-priced, low-technology products.
(True/False)
4.8/5 (82)
(82) Which of the following describes a situation in which every good or service is produced up to the point where the last unit provides a marginal benefit to consumers equal to the marginal cost of producing it?
(Multiple Choice)
4.7/5 (87)
(87) A perfectly competitive apple farm produces 1,000 bushels of apples at a total cost of $36,000. The price of each bushel is $50. Calculate the firm's short-run profit or loss.
(Multiple Choice)
4.8/5 (84)
(84) Figure 12-16  -Refer to Figure 12-16. Which panel best represents the perfectly competitive organic produce market's transition to the long run when some firms in the market are earning economic profits?
 (Multiple Choice)
4.9/5 (70)
(70) If, for a given output level, a perfectly competitive firm's price is less than its average variable cost, then the firm
(Multiple Choice)
5.0/5 (84)
(84) Some markets have many buyers and sellers but fall into the category of monopolistic competition rather than perfect competition. The most common reason for this is
(Multiple Choice)
4.8/5 (73)
(73) Maximizing average profit is equivalent to maximizing total profit.
(True/False)
4.8/5 (69)
(69) Figure 12-5  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5. What is the minimum price the firm requires to produce output?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5. What is the minimum price the firm requires to produce output? (Multiple Choice)
4.7/5 (96)
(96) In the short run, if price falls below a firm's minimum average total cost, then the firm should shut down.
(True/False)
4.8/5 (72)
(72) If a perfectly competitive firm's total revenue is less than its total variable cost, the firm
(Multiple Choice)
5.0/5 (78)
(78) Figure 12-5 Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5. If the market price is $20, what is the average profit at the profit-maximizing quantity?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5. If the market price is $20, what is the average profit at the profit-maximizing quantity? (Multiple Choice)
4.9/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)