



 Chat with AI
Exam 11: Standard Costs for Control: Flexible Budgets and Manufacturing Overhead

Exam 1: Management Accounting: Information for Creating Value and Managing Resources67 Questions
Exam 2: Management Accounting: Cost Terms and Concepts87 Questions
Exam 3: Cost Behaviour, Cost Drivers and Cost Estimation93 Questions
Exam 4: Product Costing Systems88 Questions
Exam 5: Process Costing and Operation Costing87 Questions
Exam 6: Service Costing91 Questions
Exam 7: A Closer Look at Overhead Costs99 Questions
Exam 8: Activity-Based Costing91 Questions
Exam 9: Budgeting Systems92 Questions
Exam 10: Standard Costs for Control: Direct Material and Direct Labour105 Questions
Exam 11: Standard Costs for Control: Flexible Budgets and Manufacturing Overhead109 Questions
Exam 12: Managing and Reporting Performance102 Questions
Exam 13: Financial Performance Measures and Incentive Schemes93 Questions
Exam 14: Strategic Performance Measurement Systems80 Questions
Exam 15: Managing Suppliers and Customers90 Questions
Exam 16: Managing Costs and Quality92 Questions
Exam 17: Sustainability and Management Accounting76 Questions
Exam 18: Cost Volume Profit Analysis111 Questions
Exam 19: Information for Decisions: Relevant Costs and Benefits116 Questions
Exam 20: Pricing and Product Mix Decisions113 Questions
Exam 21: Information for Capital Expenditure Decisions125 Questions
Select questions type


Management response to volume variance
The SanBo Plant has an overall plant manager, four assistant plant managers and 30 department managers. One of the assistant plant managers made the following comments at a meeting of the department managers that report to him: 'These unfavourable production volume variances are killing our performance. When these variances are put on a per unit basis and added to our standard costs, the resulting product costs make us look like the worst plant in the company. If we don't get our unit costs down and look more efficient, we will be in deep trouble. The plant might be closed.
'This is what we should do. I want these departments to run at 100 per cent of normal output. If you don't have specific orders, make some of the components that are used for our most popular products. We can store the stuff; we will have to use it some time. Meanwhile that will boost our output, eliminate the unfavourable production volume variances and get our unit costs back down where they should be.'
Will the assistant plant manager's suggestion improve the plant's performance? Explain why or why not.
(Essay)
4.7/5  (83)
(83) Use the following data to determine the company's fixed overhead volume variance for March. 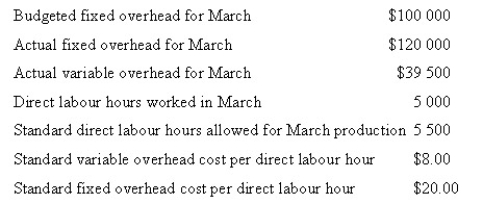 A. $10 000 overapplied
B. $10 000 underapplied
C. $20 000 overapplied
D. $20 000 underapplied
A. $10 000 overapplied
B. $10 000 underapplied
C. $20 000 overapplied
D. $20 000 underapplied (Not Answered)
This question doesn't have any answer yet
When does budgeted fixed overhead differ from applied fixed overhead? (Assume the number of machine hours is the activity base.)
(Multiple Choice)
4.8/5 (78)
(78) Hamilton Pty Ltd uses a standard costing system for product costing. The company uses direct labour hours as the cost driver to apply overhead costs. The following amounts were budgeted for the year: 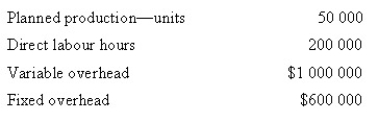 The following were the actual results:
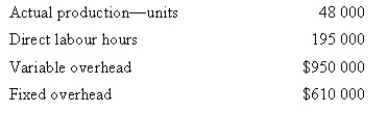 Calculate the amount of overhead cost applied to work in process inventory.
The following were the actual results:
Calculate the amount of overhead cost applied to work in process inventory. (Multiple Choice)
4.9/5 (86)
(86) Felter Company uses a standard costing system based on direct labour hours. Last month, Felter Company used more direct labour hours than planned, while the production level was consistent with expectations. This is likely to result in
(Multiple Choice)
4.9/5 (75)
(75) 
Felter Company uses a standard costing system based on direct labour hours. Last month, Felter Company used more electricity and indirect materials than planned. This is likely to result in
(Multiple Choice)
4.9/5 (66)
(66) Hamilton Pty Ltd uses a standard costing system for product costing. The company uses direct labour hours as the cost driver to apply overhead costs. The following amounts were budgeted for the year: 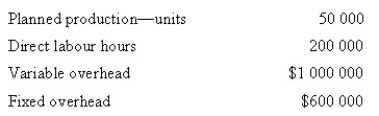 The following were the actual results:
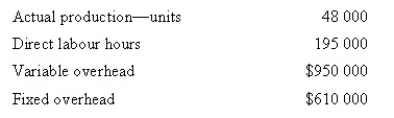 Calculate the amount of variable overhead spending variance.
The following were the actual results:
Calculate the amount of variable overhead spending variance. (Multiple Choice)
4.9/5 (72)
(72) Management uses flexible budgets for controlling manufacturing overhead costs.
(True/False)
4.7/5 (83)
(83) A flexible budget is prepared for an expected level of activity.
(True/False)
4.8/5 (67)
(67) Advantages of standard costing
One of the stated advantages of standard costing is 'more stable product costs'.
i. List two other advantages of standard costing.
ii. Assume that the company's business activity has a strong seasonal pattern; namely, the volume of activity in the busiest month of the year is four times as large as the volume in the slowest month. Explain how standard costing gives more stable product costs in this situation. You may assume that, on average, fixed costs of production amount to more than half of the cost of the product.
(Essay)
5.0/5 (77)
(77) Hamilton Pty Ltd uses a standard costing system for product costing. The company uses direct labour hours as the cost driver to apply overhead costs. The following amounts were budgeted for the year: 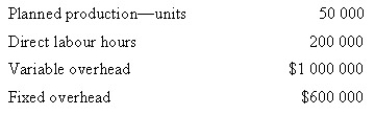 The following were the actual results:
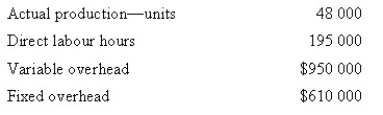 Calculate the fixed overhead volume variance.
The following were the actual results:
Calculate the fixed overhead volume variance. (Multiple Choice)
4.9/5 (88)
(88) Atrex Company determined that its variable overhead spending variance was $10 000 unfavourable for the year. Actual variable overhead was $100 000 for the year. Variable overhead is applied based on machine hours. The standard rate per machine hour was $9. The standard quantity of machine hours allowed for good output was 9000. What was the actual quantity of machine hours used?
(Multiple Choice)
4.8/5 (73)
(73) Hamilton Pty Ltd uses a standard costing system for product costing. The company uses direct labour hours as the cost driver to apply overhead costs. The following amounts were budgeted for the year: 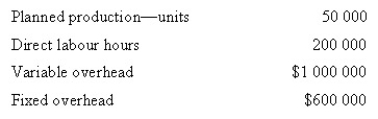 The following were the actual results:
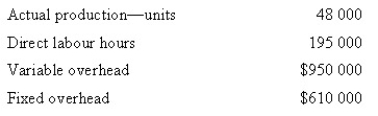 Calculate the amount of variable overhead efficiency variance.
The following were the actual results:
Calculate the amount of variable overhead efficiency variance. (Multiple Choice)
4.9/5 (65)
(65) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)