



 Chat with AI
Exam 7: Financial Assets

Exam 1: Accounting: Information for Decision Making135 Questions
Exam 2: Basic Financial Statements158 Questions
Exam 3: The Accounting Cycle: Capturing Economic Events161 Questions
Exam 4: The Accounting Cycle: Accruals and Deferrals160 Questions
Exam 5: The Accounting Cycle: Reporting Financial Results136 Questions
Exam 6: Merchandising Activities144 Questions
Exam 7: Financial Assets233 Questions
Exam 8: Inventories and the Cost of Goods Sold169 Questions
Exam 9: Plant and Intangible Assets154 Questions
Exam 10: Liabilities221 Questions
Exam 11: Stockholders Equity: Paid-In Capital166 Questions
Exam 12: Income and Changes in Retained Earnings153 Questions
Exam 13: Statement of Cash Flows181 Questions
Exam 14: Financial Statement Analysis165 Questions
Exam 15: Global Business and Accounting95 Questions
Exam 16: Management Accounting: a Business Partner124 Questions
Exam 17: Job Order Cost Systems and Overhead Allocations116 Questions
Exam 18: Process Costing103 Questions
Exam 19: Costing and the Value Chain89 Questions
Exam 20: Cost-Volume-Profit Analysis147 Questions
Exam 21: Incremental Analysis119 Questions
Exam 22: Responsibility Accounting and Transfer Pricing108 Questions
Exam 23: Operational Budgeting115 Questions
Exam 24: Standard Cost Systems130 Questions
Exam 25: Rewarding Business Performance71 Questions
Exam 26: Capital Budgeting125 Questions
Exam 28: Forms of Business Organization52 Questions
Exam 27: The Time Value of Money: Future Amounts and Present Values Answer Key49 Questions
Select questions type


Red Pine, Inc. established a $400 petty cash fund several months ago and replenishes it at the end of each month. During the first two weeks of March, $185 was disbursed from the petty cash box for miscellaneous items. If a surprise count of the fund is made on March 15, the petty cash box should contain:
(Multiple Choice)
4.8/5  (74)
(74) At year-end, Atkins Company applies the income statement approach in estimating uncollectible accounts expense and determines such expense to be 2% of net sales. At December 31 of the current year, accounts receivable total $600,000, and Allowance for Doubtful Accounts has a credit balance of $4,200 prior to adjustment. Net sales for the current year were $2,300,000. Compute the net realizable value of accounts receivable to be reported in Dewey's December 31 balance sheet.
(Essay)
4.9/5 (72)
(72) Assuming Neptune does not sell this investment, the mark-to-market adjustment necessary at December 31, 2011, includes:
(Multiple Choice)
4.9/5 (84)
(84) Prepare the journal entry to correct Huang's records as of June 30. (Explanations may be omitted; one compound journal entry is acceptable.)
2009 General Journal Debit Credit June 30
(Essay)
4.8/5 (89)
(89) Stanley, Inc.'s 2009 income statement reported net sales of $6,000,000, uncollectible accounts expense of $160,000, and net income of $700,000. Stanley's average accounts receivable during 2009 amounted to $1,200,000. Using 360 days to a year, Stanley's
(Multiple Choice)
4.9/5 (78)
(78) The valuation principle of "mark-to-market" applied to investments classified as available for sale securities:
(Multiple Choice)
4.9/5 (80)
(80) Taylor, Inc. had accounts receivable of $310,000 and an allowance for doubtful accounts of $19,500 just before writing off as worthless an account receivable from Burton Company of $1,300. The net realizable value of the accounts receivable before and after the write-off were:
(Multiple Choice)
4.9/5 (71)
(71) While preparing a bank reconciliation, an accountant discovered that a $426 check returned with the bank statement had been recorded erroneously in the depositor's accounting records as $462. In preparing the bank reconciliation the appropriate action to correct this error would be to:
(Multiple Choice)
5.0/5 (79)
(79) When an Allowance for Doubtful Accounts is used, accounts receivable are valued in the balance sheet at their estimated net realizable value.
(True/False)
4.8/5 (77)
(77) Financial assets describe not just cash, but all assets that are easily and directly convertible into known amounts of cash, except marketable securities.
(True/False)
4.8/5 (97)
(97) An unrealized loss on available-for-sale securities will reduce net income.
(True/False)
4.8/5 (85)
(85) Assuming a 365 day year, Bush Industries calculated an average of 47 days to collect its accounts receivable in 2012. During 2012, Bush's accounts receivable turnover rate:
(Multiple Choice)
4.8/5 (81)
(81) In preparing a bank reconciliation, a service charge shown on the bank statement should be:
(Multiple Choice)
4.9/5 (71)
(71) Silver Company received a 60-day, 6% note for $16,000 on August 5. Which of the following statements is true?
(Multiple Choice)
4.7/5 (82)
(82) An Unrealized Holding Gain (or Loss) on Investments classified as "available-for-sale" securities:
(Multiple Choice)
4.8/5 (76)
(76) An unrealized gain on available-for-sale securities will increase shareholders' equity.
(True/False)
4.8/5 (68)
(68) Tutor uses the balance sheet approach in estimating uncollectible accounts expense, and aging the accounts receivable indicates the estimated uncollectible portion to be $7,400. The net realizable value of Tutor's accounts receivable in the March 31 balance sheet is:
(Multiple Choice)
4.8/5 (80)
(80) Windsor uses the balance sheet approach in estimating uncollectible accounts expense, and aging the accounts receivable indicates the estimated uncollectible portion to be $7,400. What is the amount of uncollectible accounts expense recognized in Windsor's income statement for January?
(Multiple Choice)
4.8/5 (86)
(86) If a company uses a percentage of net sales in computing the amount of uncollectible accounts expense:
(Multiple Choice)
4.7/5 (70)
(70) You are to complete the June 30 bank reconciliation for Huang, Inc. using the following information:
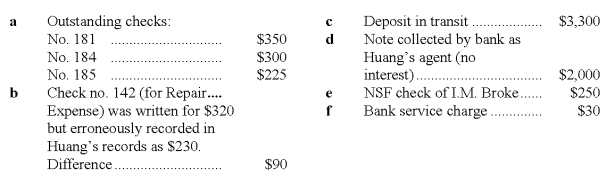
(Essay)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)