



 Chat with AI
Exam 25: Taxation of International Transactions

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


"Inbound" and "offshore" asset transfers by a U.S. business can be subject to immediate Federal income taxation under § 367.
(True/False)
4.9/5  (76)
(76) Kipp, a U.S. shareholder under the CFC provisions, owns 40% of a CFC. If the CFC's Subpart F income for the taxable year is $200,000, Kipp is taxed on receipt of a constructive dividend of $80,000.
(True/False)
4.9/5 (79)
(79) Match the definition with the correct term.
a. Expatriate
b. Resident
c. Nonresident alien
d. U.S. trade or business
e. Branch profits tax
f. Effectively connected income
-An individual who gives up U.S. citizenship to avoid U.S. income taxes.
(Short Answer)
4.7/5 (66)
(66) During Year 4, Josita, an NRA, receives interest income of $50,000 from Talmadge, Inc., an unrelated U.S. corporation. Considering the following facts related to Talmadge's operations, what is the sourcing of the interest income received by Josita?

(Essay)
4.9/5 (84)
(84) In creating a foreign subsidiary, to avoid current income taxation, a U.S. person should transfer ownership to the subsidiary of:
(Multiple Choice)
4.7/5 (100)
(100) Which of the following statements regarding the sourcing of gross income is true?
(Multiple Choice)
4.8/5 (75)
(75) Which of the following statements regarding a non-U.S. person's U.S. tax consequences is true?
(Multiple Choice)
4.8/5 (86)
(86) Which of the following statements regarding a non-U.S. person's U.S. tax consequences is true?
(Multiple Choice)
4.9/5 (81)
(81) Unused foreign tax credits are carried back two years and then forward 20 years.
(True/False)
4.8/5 (81)
(81) In which of the following independent situations would Slane, a foreign corporation, be classified as a controlled foreign corporation? The Slane stock is directly owned 12% by Jen, 10% by Kathy, 12% by Leslie, 10% by David, 8% by Ben, and 48% by Mike.
(Multiple Choice)
4.8/5 (83)
(83) Gains on the sale of U.S. real property held directly or indirectly through U.S. stock ownership by NRAs and foreign corporations are subject to tax at capital gains rates under FIRPTA.
(True/False)
4.7/5 (79)
(79) The following persons own Schlecht Corporation, a non-U.S.entity. 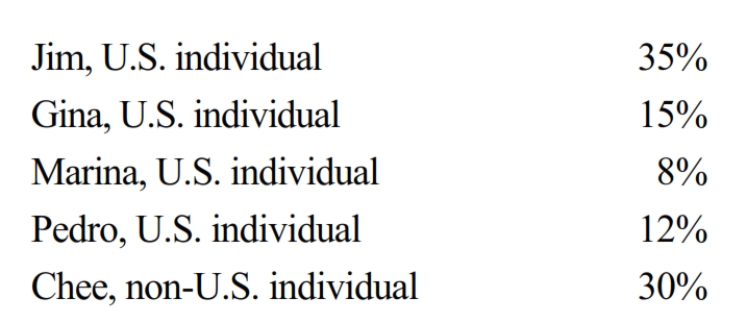 None of the shareholders are related. Subpart F income for the tax year is $300,000. No distributions are made. Which of the following statements is correct?
 (Multiple Choice)
4.8/5 (69)
(69) Match the definition with the correct term.
a. Inbound
b. Outbound
c. Allocation and apportionment
d. Qualified business unit
e. Tax haven
f. Income tax treaty
g. Section 482
-Treasury powers over transfer pricing.
(Short Answer)
5.0/5 (82)
(82) The IRS can use § 482 reallocations to assure that transactions between related parties are properly reflected in a tax return.
(True/False)
4.9/5 (80)
(80) Match the definition with the correct term.
a. Inbound
b. Outbound
c. Allocation and apportionment
d. Qualified business unit
e. Tax haven
f. Income tax treaty
g. Section 482
-A country with very low or no income tax.
(Short Answer)
4.8/5 (79)
(79) ForCo, a non-U.S. corporation based in Aldonza, purchases widgets from USCo, Inc., its U.S. parent corporation.
The widgets are sold by ForCo to an unrelated foreign corporation in Aldonza. The income from sale of the widgets by ForCo is Subpart F foreign base company sales income.
(True/False)
4.8/5 (79)
(79) Luisa, a non-U.S. person with a green card, spends the following days in the United States. 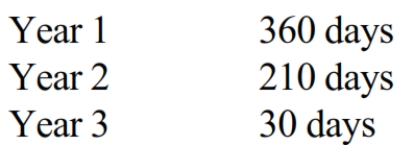 Luisa's residency status for Year 3 is:
 (Multiple Choice)
4.7/5 (78)
(78) Which of the following statements regarding the U.S. taxation of non-U.S. persons is true?
(Multiple Choice)
4.8/5 (83)
(83) Describe and diagram the timeline that most businesses use to enter the international markets.
(Essay)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)