



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models233 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System259 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes208 Questions
Exam 5: Externalities, environmental Policy, and Public Goods267 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care169 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade189 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting278 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice,taxes,and the Distribution of Income258 Questions
Select questions type


Figure 12-5  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.What is the minimum price the firm requires to produce output?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.What is the minimum price the firm requires to produce output? (Multiple Choice)
4.8/5  (73)
(73) Figure 12-1  -Refer to Figure 12-3.If the firm is producing 500 units,what is the amount of its profit or loss?
 (Multiple Choice)
4.8/5 (70)
(70) For a perfectly competitive firm,which of the following is not true at profit maximization?
(Multiple Choice)
4.7/5 (73)
(73) A perfectly competitive firm's horizontal demand curve implies that the firm does not have to lower its price to sell more output.
(True/False)
4.9/5 (75)
(75) A teenaged babysitter is similar to a firm in a perfectly competitive industry in that,for both
(Multiple Choice)
4.8/5 (73)
(73) In a decreasing-cost industry,the entry of new firms lowers average cost at each level of output.
(True/False)
4.7/5 (80)
(80) Ethan Nicholas,who developed the iShoot application for the iPhone 3G,found that to maintain sales in a profitable competitive market,the price of a product
(Multiple Choice)
4.9/5 (86)
(86) Table 12-1
 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8,what is the profit-maximizing quantity?
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8,what is the profit-maximizing quantity? (Multiple Choice)
4.9/5 (80)
(80) Table 12-4
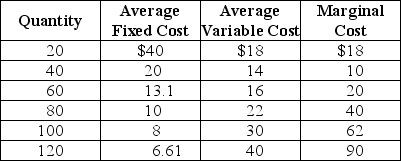 Table 12-4 shows the short-run cost data of a perfectly competitive firm. Assume that output can only be increased in batches of 20 units.
-Refer to Table 12-4.If the market price is $45 the firm will produce
Table 12-4 shows the short-run cost data of a perfectly competitive firm. Assume that output can only be increased in batches of 20 units.
-Refer to Table 12-4.If the market price is $45 the firm will produce (Multiple Choice)
4.8/5 (71)
(71) Which of the following is a characteristic of a firm in a perfectly competitive market?
(Multiple Choice)
4.9/5 (82)
(82) If the market price is $25 in a perfectly competitive market,the marginal revenue from selling the fifth unit is
(Multiple Choice)
4.8/5 (79)
(79) A very large number of small sellers who sell identical products imply
(Multiple Choice)
4.8/5 (70)
(70) Marty's Bird House suffers a short-run loss.Marty can reduce his loss below the amount of his total fixed costs by continuing to produce if his revenue
(Multiple Choice)
4.9/5 (80)
(80) Figure 12-9  Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.Identify the firm's short-run supply curve.
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.Identify the firm's short-run supply curve. (Multiple Choice)
4.8/5 (80)
(80) In an increasing-cost industry the long-run supply curve is upward sloping.
(True/False)
4.9/5 (77)
(77) Figure 12-5 Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens in the diagram above?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens in the diagram above? (Multiple Choice)
5.0/5 (83)
(83) A perfectly competitive industry achieves allocative efficiency because
(Multiple Choice)
4.7/5 (84)
(84) Figure 12-1
-Refer to Figure 12-1.If the firm is producing 700 units
-Refer to Figure 12-1.If the firm is producing 700 units (Multiple Choice)
4.7/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)