



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models233 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System259 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes208 Questions
Exam 5: Externalities, environmental Policy, and Public Goods267 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care169 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade189 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting278 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice,taxes,and the Distribution of Income258 Questions
Select questions type


Assume that the personal computer industry is perfectly competitive.The fact that the price of personal computers over the last decade has fallen despite increases in demand signifies that the industry is a decreasing-cost industry.
(True/False)
4.7/5  (83)
(83) A perfectly competitive firm in long-run equilibrium produces output at the lowest possible average total cost.
(True/False)
4.9/5 (79)
(79) Figure 12-9  Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.At price P4,the firm would produce
Figure 12-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-9.At price P4,the firm would produce (Multiple Choice)
4.9/5 (78)
(78) Figure 12-5  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.The figure shows the cost structure of a firm in a perfectly competitive market.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens to its profit-maximizing output level?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.The figure shows the cost structure of a firm in a perfectly competitive market.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens to its profit-maximizing output level? (Multiple Choice)
4.9/5 (76)
(76) Figure 12-13 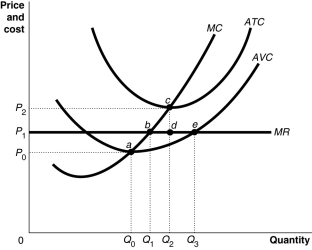 -Refer to Figure 12-13.Suppose the prevailing price is P1 and the firm is currently producing its loss-minimizing quantity.In the long-run equilibrium
 (Multiple Choice)
4.9/5 (74)
(74) Competition has driven the economic profits in the video rental business to zero.Surya Bacha,who owns a video rental business,would be better off leaving the industry for another alternative.
(True/False)
4.9/5 (79)
(79) For a given quantity,the total profit of a perfectly competitive firm is equal to the vertical distance between the firm's total revenue curve and its total cost curve.
(True/False)
4.7/5 (83)
(83) Assume the market for organic produce sold at farmers' markets is perfectly competitive.All else equal,as more farmers choose to produce and sell organic produce at farmers' markets,what is likely to happen to the equilibrium price of the produce and profits of the organic farmers in the long run?
(Multiple Choice)
4.8/5 (67)
(67) If price = marginal cost at the output produced by a perfectly competitive firm and the firm is earning an economic profit,then
(Multiple Choice)
4.9/5 (83)
(83) Which of the following is not an assumption of perfectly competitive markets?
(Multiple Choice)
4.8/5 (78)
(78) In long-run perfectly competitive equilibrium,which of the following is false?
(Multiple Choice)
4.7/5 (86)
(86) Perfect competition is characterized by all of the following except
(Multiple Choice)
4.8/5 (89)
(89) How are market price,average revenue,and marginal revenue related for a perfectly competitive firm and why?
(Essay)
4.8/5 (88)
(88) Table 12-1
 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8 and the firm maximizes profit,what is the amount of the firm's profit or loss?
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8 and the firm maximizes profit,what is the amount of the firm's profit or loss? (Multiple Choice)
4.9/5 (78)
(78) Figure 12-8  -Refer to Figure 12-8.Suppose the firm produces 4,000 units.What does the shaded area labeled A represent?
 (Multiple Choice)
4.9/5 (94)
(94) In the short run,a firm that is operating at a loss has two options.These options are
(Multiple Choice)
4.8/5 (72)
(72) Use a graph to show the demand,AVC,ATC,MC,and MR curves of a firm that should temporarily shut down in the short run.Identify the shutdown point on the graph.
(Essay)
4.7/5 (87)
(87) Figure 12-11  -Refer to Figure 12-11.Suppose the prevailing price is $20 and the firm is currently producing 1,350 units.In the long-run equilibrium,the firm represented in the diagram
 (Multiple Choice)
4.9/5 (67)
(67) The market demand curve for a perfectly competitive industry is the horizontal summation of each individual firm's demand curve.
(True/False)
4.9/5 (84)
(84) A constant cost,perfectly competitive market is in long-run equilibrium.At present,there are 1,000 firms each producing 400 units of output.The price of the good is $60.Now suppose there is a sudden increase in demand for the industry's product which causes the price of the good to rise to $64.In the new long-run equilibrium,how will the average total cost of producing the good compare to what it was before the price of the good rose?
(Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)