



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models233 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System259 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes208 Questions
Exam 5: Externalities, environmental Policy, and Public Goods267 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care169 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade189 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting278 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice,taxes,and the Distribution of Income258 Questions
Select questions type


Table 12-1
 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.The firm will not produce in the short run if the output price falls below
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.The firm will not produce in the short run if the output price falls below (Multiple Choice)
4.8/5  (102)
(102) Figure 12-14 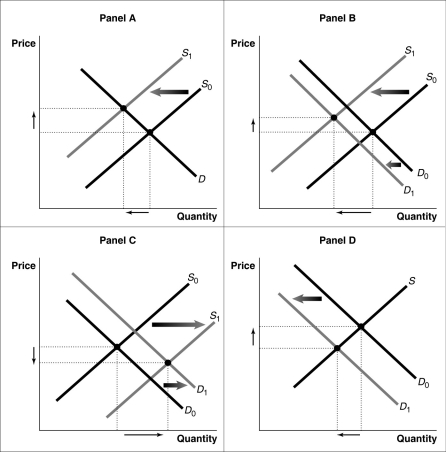 -Refer to Figure 12-14.Consider a typical firm in a perfectly competitive industry which is incurring short-run losses.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (78)
(78) If,for a given output level,a perfectly competitive firm's price is less than its average variable cost,the firm
(Multiple Choice)
4.8/5 (77)
(77) If the long-run average cost curve is U-shaped,the optimal scale of production from society's viewpoint is
(Multiple Choice)
4.9/5 (79)
(79) Figure 12-2  -Refer to Figure 12-2.Why is the total revenue curve a ray from the origin?
 (Multiple Choice)
4.8/5 (76)
(76) New York Times writer Michael Lewis wrote that "The sad truth,for investors,seems to be that most of the benefits....are passed through to consumers free of charge." To which of the following did Lewis refer?
(Multiple Choice)
4.7/5 (78)
(78) Assume that firms in a perfectly competitive market are earning economic profits.Which of the following statements describes the change in market price and output as a result of the entry of new firms into this market?
(Multiple Choice)
4.9/5 (82)
(82) At the profit-maximizing level of output for a perfectly competitive firm
(Multiple Choice)
4.8/5 (64)
(64) Under what conditions should a competitive firm shut down in the short run?
(Essay)
4.8/5 (64)
(64) Assuming a market price of $4,fill in the columns in the following table.What is the profit-maximizing level of production? What are the two ways to determine the profit-maximizing level of production?
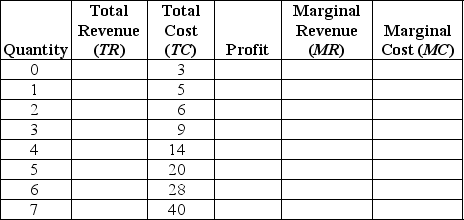
(Essay)
4.9/5 (78)
(78) If price is equal to average variable cost,a perfectly competitive firm breaks even.
(True/False)
4.9/5 (90)
(90) Figure 12-17  The graphs in Figure 12-17 represent the perfectly competitive market demand and supply curves for the apple industry and demand and cost curves for a typical firm in the industry.
-Refer to Figure 12-17.Which of the following statements is true?
The graphs in Figure 12-17 represent the perfectly competitive market demand and supply curves for the apple industry and demand and cost curves for a typical firm in the industry.
-Refer to Figure 12-17.Which of the following statements is true? (Multiple Choice)
4.8/5 (82)
(82) The minimum point on the average variable cost curve is called the loss-minimizing point.
(True/False)
4.7/5 (79)
(79) Which of the following characteristics of a farmers' market make it a good example of a perfectly competitive market?
(Multiple Choice)
4.9/5 (76)
(76) If in a perfectly competitive industry,the market price facing a firm is below its average total cost but above average variable cost at the output where marginal cost equals marginal revenue
(Multiple Choice)
4.9/5 (86)
(86) Letters are used to represent the terms used to answer this question: price (P),quantity of output (Q),total cost (TC)and average total cost (ATC).Which of the following equations is equal to a firm's average profit?
(Multiple Choice)
4.8/5 (91)
(91) What is meant by productive efficiency? How does a perfectly competitive firm achieve productive efficiency?
(Essay)
4.9/5 (84)
(84) The short-run supply curve for a perfectly competitive firm is that part of the firm's marginal cost curve that lies above the minimum point of its average variable cost curve.
(True/False)
4.9/5 (90)
(90) Figure 12-4  Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30 and the firm is producing output,what is the amount of the firm's profit or loss?
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30 and the firm is producing output,what is the amount of the firm's profit or loss? (Multiple Choice)
5.0/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)