



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models233 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System259 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes208 Questions
Exam 5: Externalities, environmental Policy, and Public Goods267 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care169 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade189 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting278 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice,taxes,and the Distribution of Income258 Questions
Select questions type


A perfectly competitive firm has to charge the same price as every other firm in the market.Therefore,the firm
(Multiple Choice)
4.8/5  (93)
(93) If firms do not earn economic profits in a competitive equilibrium,why would the firms choose to stay in business?
(Essay)
4.8/5 (71)
(71) An individual seller in perfect competition will not sell at a price lower than the market price because
(Multiple Choice)
4.8/5 (89)
(89) In a graph that illustrates a perfectly competitive firm,marginal revenue is
(Multiple Choice)
4.9/5 (77)
(77) The minimum point on the average variable cost curve is called
(Multiple Choice)
4.8/5 (77)
(77) If,as a perfectly competitive industry expands,it can supply larger quantities only at a higher long-run equilibrium price,it is
(Multiple Choice)
4.8/5 (76)
(76) Assume that price is greater than average variable cost.If a perfectly competitive seller is producing at an output where price is $11 and the marginal cost is $14.54,then to maximize profits the firm should
(Multiple Choice)
4.8/5 (79)
(79) Table 12-3
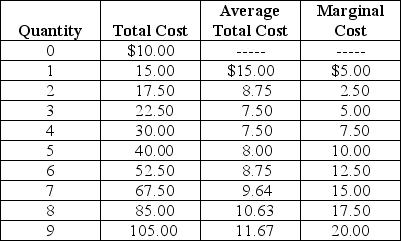 Arnie sells basketballs in a perfectly competitive market. Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC) and marginal cost (MC).
-Refer to Table 12-3.What price (P)will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50?
Arnie sells basketballs in a perfectly competitive market. Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC) and marginal cost (MC).
-Refer to Table 12-3.What price (P)will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50? (Multiple Choice)
4.9/5 (79)
(79) If in the long run a firm makes zero profit,it should exit the industry.
(True/False)
4.8/5 (74)
(74) In the long run,perfectly competitive firms earn zero economic profit.Why do firms enter an industry when they know that in the long-run they will not earn any profit?
(Essay)
4.9/5 (83)
(83) If,for the last bushel of apples produced and sold by an apple farm marginal revenue exceeds marginal cost,then in producing that bushel the farm
(Multiple Choice)
4.8/5 (79)
(79) Perfectly competitive industries tend to produce low-priced,low-technology products.
(True/False)
4.9/5 (91)
(91) Table 12-2
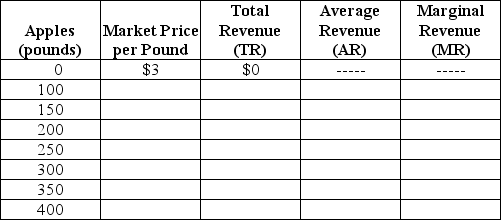 Table 12-2 lists the various pounds (lbs.) of apples that Margie Stattler can sell. Assume that Margie operates in a perfectly competitive market.
-Refer to Table 12-2.How many pounds of apples should Margie sell to maximize her profit?
Table 12-2 lists the various pounds (lbs.) of apples that Margie Stattler can sell. Assume that Margie operates in a perfectly competitive market.
-Refer to Table 12-2.How many pounds of apples should Margie sell to maximize her profit? (Multiple Choice)
4.9/5 (72)
(72) Figure 12-12 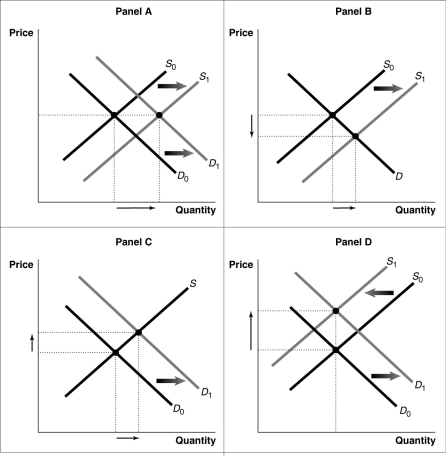 -Refer to Figure 12-12.Consider a typical firm in a perfectly competitive industry that makes short-run profits.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.9/5 (76)
(76) If a perfectly competitive firm raises the price it charges to consumers,which of the following is the most likely outcome?
(Multiple Choice)
4.9/5 (93)
(93) Firms in perfect competition produce the allocatively efficient output in the short run and in the long run.
(True/False)
4.8/5 (80)
(80) Which of the following is not an option for a perfectly competitive firm that suffers short-run losses?
(Multiple Choice)
4.8/5 (82)
(82) The market demand curve in a perfectly competitive market is downward-sloping.
(True/False)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)