



 Chat with AI
Exam 21: Partnerships

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


The amount of a partnership's income and loss from operating activities is combined with separately stated income and expenses in determining the partnership's net income (loss).This amount is reconciled to book income on the partnership's Schedule M-1 or Schedule M-3.
(True/False)
4.8/5  (82)
(82) Katherine invested $80,000 this year to purchase a 30% interest in the KLM Partnership.The partnership reported $200,000 of net income from operations, a $2,000 short-term capital loss, and a $10,000 charitable contribution.In addition, the partnership distributed $20,000 to Katherine and $10,000 each to partners Lauren and Missy.Assuming the partnership has no beginning or ending liabilities, what is Katherine's basis in her partnership interest at the end of the year?
(Essay)
4.9/5 (66)
(66) Jeordie and Kendis created the JK Partnership by contributing $100,000 each.The $200,000 cash was used by the partnership to acquire a depreciable asset.The partnership agreement provides that the partners' capital accounts will be maintained in accordance with Reg.§ 1.704-1(b) (the "economic effect" Regulations) and that any partner with a deficit capital account will be required to restore that capital account when the partner's interest is liquidated.The partnership agreement provides that MACRS will be allocated 20% to Jeordie and 80% to Kendis.All other items of partnership income, gain, loss, deduction, and credit will be allocated equally between the partners.In the first year, MACRS is $40,000 and no other operating transactions occur.The property is sold at the end of the year for $160,000 and the partnership is liquidated immediately thereafter.
To satisfy the economic effect test, how much of the $160,000 cash (from the sale) is allocated each to Jeordie and Kendis?
(Essay)
4.9/5 (84)
(84) Mack has a basis in a partnership interest of $200,000, including his share of partnership debt. At the end of the current year, the partnership distributed to Mack, in a proportionate nonliquidating distribution, cash of $20,000, inventory (basis to the partnership of $30,000 and fair market value of $40,000), and land (basis to the partnership of $40,000 and fair market value of $42,000).In addition, Mack's share of partnership debt decreased by $12,000 during the year. What basis does Mack take in the inventory and land and in the partnership interest (including debt share) following the distribution?
(Multiple Choice)
4.8/5 (79)
(79) Loss will be recognized on any distribution from a partnership in which cash, unrealized receivables and/or appreciated inventory are the only items distributed.
(True/False)
4.8/5 (87)
(87) On a partnership's Form 1065, which of the following statements is not true?
(Multiple Choice)
4.9/5 (85)
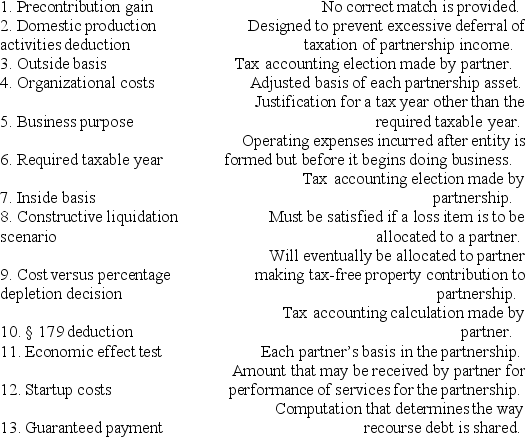
(85) Match each of the following statements with the terms below that provide the best definition.
(Essay)
4.7/5 (73)
(73) Mark and Addison formed a partnership.Mark received a 25% interest in partnership capital and profits in exchange for land with a basis of $40,000 and a fair market value of $60,000.Addison received a 75% interest in partnership capital and profits in exchange for $180,000 of cash.Three years after the contribution date, the land contributed by Mark is sold by the partnership to a third party for $76,000.How much taxable gain will Mark recognize from the sale?
(Multiple Choice)
4.7/5 (80)
(80) Seven years ago, Paul purchased residential rental estate that he has been depreciating as MACRS property over 27.5 years.This year, when his adjusted basis in the property was $250,000, Paul transferred the property to the newly formed PLA LLC in exchange for a one-third interest in the LLC.PLA incurred $10,000 of transfer taxes and fees related to the property.PLA must treat the $260,000 basis in the property, fees, and expenses, as new MACRS property depreciable over 27.5 years.
(True/False)
4.8/5 (83)
(83) Nick sells his 25% interest in the LMNO Partnership to new partner Katrina for $57,500.The partnership's assets consist of cash ($100,000), land (basis of $90,000, fair market value of $70,000), and inventory (basis of $40,000, fair market value of $60,000).Nick's basis in his partnership interest was $57,500.On the sale, Nick will recognize ordinary income of $5,000 and a capital loss of $5,000.
(True/False)
4.9/5 (65)
(65) In a limited liability partnership, all partners are protected from all debts of the partnership.
(True/False)
4.9/5 (78)
(78) In which of the following independent situations would the transaction most likely be characterized as a disguised sale?
(Multiple Choice)
4.9/5 (77)
(77) Michelle and Jacob formed the MJ Partnership.Michelle contributed $20,000 of cash in exchange for her 50% interest in the partnership capital and profits.During the first year of partnership operations, the following events occurred: the partnership had a net taxable income of $10,000; Michelle received a distribution of $8,000 cash from the partnership; and Michelle had a 50% share in the partnership's $16,000 of recourse liabilities on the last day of the partnership year.Michelle's adjusted basis for her partnership interest at year end is:
(Multiple Choice)
4.8/5 (82)
(82) Section 721 provides that, in general, no gain or loss is recognized by the partnership or the partner on contribution of appreciated or depreciated property to a partnership in exchange for an interest in the partnership.
(True/False)
4.8/5 (73)
(73) Emma's basis in her BBDE LLC interest is $60,000 at the beginning of the tax year.Her allocable share of LLC items are as follows: $20,000 of ordinary income, $2,000 tax-exempt interest income, and a $6,000 long-term capital gain.In addition, the LLC distributed $12,000 of cash to Emma during the year.Assuming the LLC had no liabilities at the beginning or the end of the year, Emma's ending basis in her LLC interest is $88,000.
(True/False)
4.8/5 (75)
(75) Beth sells her 25% partnership interest to Katie for $50,000 cash on July 1 of the current tax year.Katie also assumed Beth's share of the partnership's liabilities.Beth's basis in her partnership interest at the beginning of the year was $40,000, including a $15,000 share of partnership liabilities.The partnership's income for the entire year was $100,000, and Beth's share of partnership debt was $10,000 as of the date she sold the partnership interest.Assume the partnership has no hot assets and that its income is earned evenly throughout the year.Beth recognizes a gain of $12,500 on the sale.
(True/False)
4.8/5 (67)
(67) An examination of the RB Partnership's tax books provides the following information for the current year:
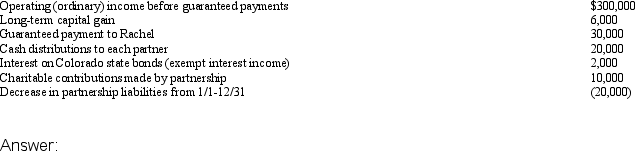 Rachel is a 30% partner in partnership capital, profits, and losses.Assume the adjusted basis of her partnership interest is $60,000 at the beginning of the year, and she shares in 30% of the partnership's liabilities for basis purposes.
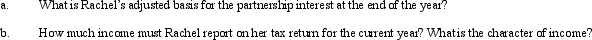
Rachel is a 30% partner in partnership capital, profits, and losses.Assume the adjusted basis of her partnership interest is $60,000 at the beginning of the year, and she shares in 30% of the partnership's liabilities for basis purposes.
(Essay)
4.9/5 (90)
(90) Your client has operated a sole proprietorship for several years, and is now interested in raising capital for expansion.He is considering forming either a C corporation or an LLC.
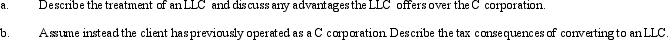
(Essay)
4.7/5 (68)
(68) Sharon contributed property to the newly formed QRST Partnership.The property had a $100,000 adjusted basis to Sharon and a $160,000 fair market value on the contribution date.The property was also encumbered by a $120,000 nonrecourse debt, which was transferred to the partnership on that date.Another partner, Rochelle, shares 30% of the partnership income, gain, loss, deduction, and credit.Under IRS regulations, Rochelle's share of the nonrecourse debt for basis purposes is:
(Multiple Choice)
4.9/5 (78)
(78) Debt of a limited liability company is allocated among LLC members using the nonrecourse debt allocation rules unless an LLC member has personally guaranteed the debt.
(True/False)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)