



 Chat with AI
Exam 21: Partnerships

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


In the current year, the CAR Partnership received revenues of $400,000 and paid the following amounts: $160,000 in rent, utilities, and salaries; a $40,000 guaranteed payment to partner Ryan; $20,000 to partner Amy for consulting services; and a $40,000 distribution to 25% partner Cameron.In addition, the partnership realized a $12,000 net long-term capital gain.Cameron's basis in his partnership interest was $60,000 at the beginning of the year, and included his $25,000 share of partnership liabilities.At the end of the year, his share of partnership liabilities was $15,000.

(Essay)
4.8/5  (80)
(80) Michelle receives a proportionate liquidating distribution when the basis of her partnership interest is $50,000.The distribution consists of $58,000 cash and noninventory property (adjusted basis to the partnership of $10,000 and fair market value of $12,000).The partnership has no hot assets.How much gain or loss does Michelle recognize, and what is her basis in the distributed property?
(Multiple Choice)
4.9/5 (74)
(74) Which of the following is not a specific adjustment to the partners' basis in the partnership interest?
(Multiple Choice)
4.9/5 (86)
(86) Julie and Kate form an equal partnership during the current year.Julie contributes cash of $160,000, and Kate contributes property (adjusted basis of $90,000, fair market value of $260,000) subject to a nonrecourse liability of $100,000.As a result of these transactions, Kate has a basis in her partnership interest of $40,000.
(True/False)
4.8/5 (82)
(82) For Federal income tax purposes, a distribution from a partnership to a partner is treated the same as a distribution from a C corporation to its shareholders.
(True/False)
4.9/5 (81)
(81) Rebecca is a limited partner in the RST Partnership, which is not publicly traded.Her allocable share of RST's passive ordinary losses from a nonrealty activity for the current year is ($60,000).Rebecca has a $40,000 adjusted basis (outside basis) for her interest in RST (before deduction of any of the passive losses).Her amount "at risk" under § 465 is $30,000 (before deduction of any of the passive losses).She also has $25,000 of passive income from other sources.How much of her ($60,000) allocable loss can Rebecca deduct on her current year's tax return?
(Multiple Choice)
4.9/5 (80)
(80) Which of the following is an election or calculation made by the partner rather than the partnership?
(Multiple Choice)
5.0/5 (82)
(82) Items that are not required to be passed through separately from a partnership to the partners include AMT adjustments and preferences and taxes paid to foreign countries.
(True/False)
5.0/5 (88)
(88) Justin and Kevin formed the equal JK Partnership during the current year, with Justin contributing $60,000 in cash and Kevin contributing land (basis of $40,000, fair market value of $30,000) and equipment (basis of $0, fair market value of $30,000).Kevin recognizes a $20,000 gain on the contribution and his basis in his partnership interest is $60,000.
(True/False)
4.8/5 (73)
(73) Ashley purchased her partnership interest from Lindsey on the first day of the current year for $40,000 cash.She received a $10,000 cash distribution from the partnership during the year, and her share of partnership income is $15,000.If her share of partnership liabilities on the last day of the partnership year is $20,000, her outside basis for her partnership interest at the end of the year is $65,000.
(True/False)
4.8/5 (88)
(88) The BLM LLC's balance sheet on August 31 of the current year is as follows. 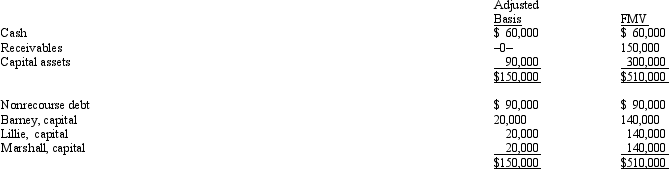 The nonrecourse debt is shared equally among the LLC members.On that date, Lillie sells her one-third interest to Robyn for $170,000, including cash and relief of Lillie's share of the nonrecourse debt.Lillie's outside basis for her interest in the LLC is $50,000, including her share of the LLC's debt.How much capital gain and/or ordinary income will Lillie recognize on the sale?
 (Multiple Choice)
4.8/5 (85)
(85) Tara and Robert formed the TR Partnership four years ago.Because they decided the company needed some expertise in multimedia presentations, they offered Katie a 1/3 interest in partnership capital if she would come to work for the partnership.She will also receive a 25% interest in future partnership profits.On July 1 of the current year, the unrestricted partnership capital interest (fair market value of $25,000) was transferred to Katie.How should Katie treat the receipt of the partnership interest in the current year?
(Multiple Choice)
4.8/5 (78)
(78) The BAM Partnership distributed the following assets to partner Barbie in a proportionate non-liquidating distribution: $10,000 cash, land parcel A (basis of $5,000, fair market value of $30,000) and land parcel B (basis of $25,000, fair market value of $20,000).Barbie's basis in her partnership interest was $40,000 immediately before the distribution.Barbie will allocate a basis of $15,000 each to the two land parcels, and her basis in her partnership interest will be reduced to $0.
(True/False)
4.9/5 (82)
(82) PaulCo, DavidCo, and Sean form a partnership with cash contributions of $80,000, $50,000 and $30,000, respectively, and agree to share profits and losses in the ratio of their original cash contributions.PaulCo uses a January 31 fiscal year-end, while DavidCo and Sean use a November 30 and December 31 year-end, respectively.The partnership must use the least aggregate deferral method to determine its year end.
(True/False)
4.8/5 (81)
(81) A partnership has accounts receivable with a basis of $0 and a fair market value of $20,000 and depreciation recapture potential of $30,000.All other assets of the partnership are either cash, capital assets, or § 1231 assets.If a purchaser acquires a 40% interest in the partnership from another partner, the selling partner will be required to recognize ordinary income of $20,000.
(True/False)
4.7/5 (89)
(89) Tim and Darby are equal partners in the TD Partnership.Partnership income for the year is $60,000.Tim needs cash in order to pay tax on his share of the partnership income, but Darby wants to leave the cash in the partnership for expansion.If the partners agree, it is acceptable for TD to distribute $8,000 to Tim, and no cash or other property to Darby.
(True/False)
4.9/5 (72)
(72) Martha receives a proportionate nonliquidating distribution when the basis of her partnership interest is $50,000.The distribution consists of $60,000 cash and noninventory property (adjusted basis to the partnership of $20,000, fair market value of $23,000).How much gain or loss does Martha recognize, and what is her basis in the distributed property and in her partnership interest following the distribution?
(Multiple Choice)
4.8/5 (78)
(78) Meagan is a 40% general partner in the calendar year, cash basis MKK Partnership.The partnership received $100,000 income from services and paid the following other amounts:
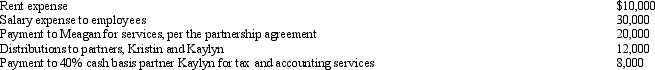 How much will Meagan's adjusted gross income increase as a result of the above items?
 (Essay)
4.8/5 (97)
(97) Marcie is a 40% member of the M&A LLC.Her basis is $10,000 immediately before the LLC distributes to her $30,000 of cash and land (basis to the LLC of $20,000 and fair market value of $25,000).As a result of the proportionate, nonliquidating distribution, Marcie recognizes a gain of $20,000 and her basis in the land is $0.
(True/False)
4.8/5 (78)
(78) In the current year, Derek formed an equal partnership with Cody.Derek contributed land with an adjusted basis of $110,000 and a fair market value of $200,000.Derek also contributed $50,000 cash to the partnership.Cody contributed land with an adjusted basis of $80,000 and a fair market value of $230,000.The land contributed by Derek was encumbered by a $60,000 nonrecourse debt.The land contributed by Cody was encumbered by $40,000 of nonrecourse debt.Assume the partners share debt equally.Immediately after the formation, what is the basis of Cody's partnership interest?
(Essay)
4.8/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)