



 Chat with AI
Exam 23: Exempt Entities

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


An educational organization such as the College of William and Mary that is exempt under § 501(c)(3) cannot be classified as a private foundation if its only sources of revenue are from tuition and alumni contributions.
(True/False)
4.9/5  (85)
(85) Which of the following exempt organizations are required to file Form 990 (Return of Organization Exempt from Income Tax)?
(Multiple Choice)
4.8/5 (83)
(83) If an exempt organization owns a feeder organization, the exempt organization is taxed on the profits of the feeder organization under the unrelated business income tax (UBIT) rules.
(True/False)
4.8/5 (80)
(80) Robin, Inc., an exempt organization, acquired a building for $500,000 which it will lease to XYZ, Inc., for $35,000 annually.To finance the acquisition of the building, Robin secures a mortgage on it of $312,500.Advise Robin as to whether it has any unrelated debt-financed income or deductions.
(Essay)
4.9/5 (79)
(79) For an activity to be considered as regularly carried on for purposes of the unrelated business income tax, the activity must be conducted during the work week (i.e., activities performed on the weekend are not considered in determining if the activity is regularly carried on).
(True/False)
4.9/5 (83)
(83) Which of the following statements regarding low-cost articles is correct?
(Multiple Choice)
4.8/5 (69)
(69) The due date for both Form 990 (Return of Organization Exempt from Income Tax) and Form 990-PF (Return of Private Foundation) is the fifteenth day of the fourth month after the end of the taxable year.
(True/False)
4.7/5 (69)
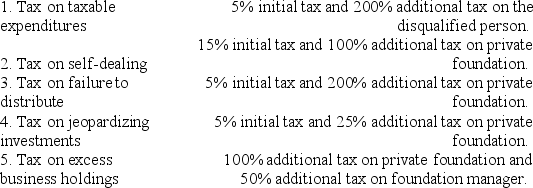
(69) For each of the following taxes which are imposed on private foundations, match the appropriate initial tax or additional tax.
(Essay)
4.8/5 (81)
(81) An entity satisfies the "not-for-profit" requirement for exempt status if its total expenses for the year exceed its gross income.
(True/False)
4.9/5 (81)
(81) Support the Pets, Inc., a § 501(c)(3) organization, provides pet food to humane societies.All of the pet food is received as contributions from individuals or from a wholly-owned, for-profit subsidiary (Sales, Inc.), which is in the retail pet food business (i.e., pet food that has been in inventory for over 120 days is transferred to Support the Pets for distributions to humane societies).In addition to the pet food, Sales distributes 75% of its net income each year to Support the Pets.
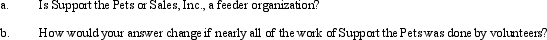
(Essay)
4.8/5 (71)
(71) The general objective of the tax on unrelated business income is to tax such income as if the entity were a taxable corporation.
(True/False)
4.9/5 (81)
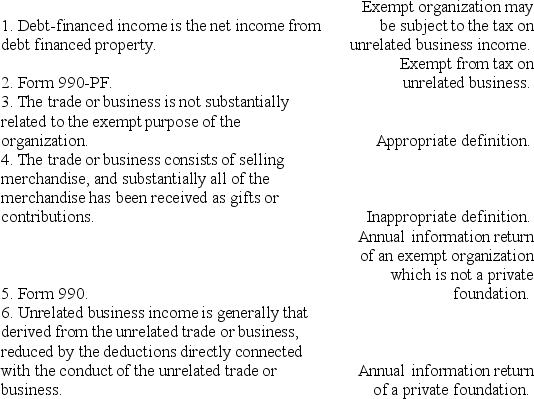
(81) 
Wett, Inc., a § 501(c)(3) exempt organization, acquired all the stock of a for-profit corporation for $150,000.Wett is a private foundation.The acquired corporation was not a related business.Calculate the tax on excess business holdings.Assume that corrective action is taken so that the additional tax does not apply.
(Essay)
4.8/5 (75)
(75) A § 501(c)(3) organization exchanges its membership lists with another exempt organization.What are the Federal income tax consequences?
(Essay)
4.9/5 (78)
(78) Which of the following excise taxes are imposed on the private foundation because it engages in prohibited transactions?
(Multiple Choice)
4.8/5 (84)
(84) Watch, Inc., a § 501(c)(3) exempt organization, solicits contributions through a mail campaign.An executive, who recently completed an executive MBA degree program, recommends that personal address labels be included as an additional way to motivate the potential donor to contribute.The value of these labels is $9.00 per potential donor.What is the effect of the inclusion of the address labels on Watch's unrelated business income?
(Essay)
4.9/5 (70)
(70) An exempt organization that is eligible to elect under § 501(h) to engage in lobbying activities on a limited basis incurs no tax liability from lobbying, if the lobbying expenditures for the tax year do not exceed the lobbying expenditures ceiling.
(True/False)
4.8/5 (89)
(89) Which exempt organizations are not required to file an annual Federal tax return?
(Essay)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)