



 Chat with AI
Exam 23: Exempt Entities

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Woeful, Inc., a tax-exempt organization, leases a building and machinery to Purple Partnership.The rental income from the building is $180,000, with related expenses of $70,000.The rental income from the machinery is $12,000, with related expenses of $3,000.What adjustment must be made to net unrelated business income?
(Essay)
4.9/5  (82)
(82) To maintain exempt status, an organization must do which of the following:
(Multiple Choice)
4.9/5 (81)
(81) If an organization qualifies for exempt status for Federal income tax purposes, it is exempt from all Federal income taxes.
(True/False)
4.9/5 (92)
(92) Which of the following statements regarding intermediate sanctions is correct?
(Multiple Choice)
4.7/5 (74)
(74) Which of the following activities is not subject to the feeder organization rules?
(Multiple Choice)
5.0/5 (79)
(79) Sandy is the treasurer for Choose, Inc., a § 501(c)(3) organization.The CEO has indicated that he would like for the exempt organization to make a substantial contribution to an entity which is lobbying against a legislative position that would be detrimental to Choose, Inc.Describe for the CEO under what circumstances an exempt organization can be eligible to lobby.
(Essay)
4.7/5 (95)
(95) Midge is the chairman of the board for a § 501(c)(3) exempt organization.She would like the exempt organization to be able to avoid private foundation classification status.Describe how this can be achieved.
(Essay)
4.9/5 (94)
(94) Soft, Inc., a § 501(c)(3) organization, has been leasing a building to Ice, Inc., a taxable entity, for 12 years.The lease terminates in the current tax year.Soft's adjusted basis for the building is $350,000.It sells the building to the Realty Partnership, a taxable entity, for $625,000.Selling expenses are $37,500.
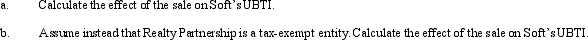
(Essay)
4.9/5 (88)
(88) Federal agencies exempt from Federal income tax under § 501(c)(1) are not subject to the unrelated business income tax (UBIT).
(True/False)
4.9/5 (83)
(83) The excise taxes such as the tax on self-dealing and the tax on excess business holdings are imposed on exempt organizations classified as private foundations and are not imposed on exempt organizations classified as public charities.
(True/False)
4.7/5 (78)
(78) Amber, Inc., an exempt organization, reports unrelated business taxable income of $300,000. Total charitable contributions are $35,000, of which $31,000 (associated with the unrelated trade or business) has been deducted in calculating net unrelated business income. Calculate Amber's positive and negative adjustments in calculating unrelated business taxable income.
(Essay)
4.9/5 (56)
(56) The excise tax that is imposed on private foundations for making jeopardizing investments is imposed because the foundation has made speculative investments that put the foundation's income at risk.
(True/False)
4.8/5 (77)
(77) A corporate payment to an exempt organization that qualifies as a qualified sponsorship payment is not subject to the unrelated business income tax (UBIT).
(True/False)
4.8/5 (85)
(85) Define average acquisition indebtedness with respect to debt-financed property.
(Essay)
4.9/5 (84)
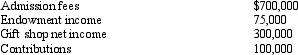
(84) First Americans, Inc., a § 501(c)(3) organization, operates a museum which depicts the lives of a tribe of Native Americans. It charges an admission fee, but also finances its operations through endowment income, contributions, and gift shop sales. The gift shop is operated by 50 volunteers and the museum is operated by 15 employees. Revenue by source is:
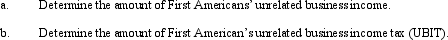
(Essay)
4.9/5 (69)
(69) Loyal, Inc., is a §501(c)(3) organization that is not classified as a private foundation.During the current year, it is subject to intermediate sanctions.What other options does the IRS have in dealing with an exempt organization engaging in prohibited transactions?
(Essay)
4.9/5 (68)
(68) Lemon, Inc., a private foundation, engages in a transaction with a disqualified person in the amount of $300,000.Calculate the tax on self-dealing.Assume that corrective action is taken so that the additional tax does not apply.
(Essay)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)