



 Chat with AI
Exam 26: Tax Practice and Ethics

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


When the IRS issues a notice of tax due, the taxpayer has 90 days to either pay the tax or file a petition with the Tax Court.This is conveyed in the "ninety-day letter."
(True/False)
4.8/5  (71)
(71) A negligence penalty is assessed when the taxpayer is found to have not made a reasonable attempt to apply with the tax law.
(True/False)
4.8/5 (81)
(81) The penalty for substantial understatement of tax liability does not apply if:
(Multiple Choice)
4.7/5 (89)
(89) Ron, a calendar year taxpayer subject to a 35% marginal income tax rate, claimed a Form 1040 charitable contribution deduction of $250,000 for a sculpture that the IRS later valued at $150,000.The applicable overvaluation penalty is:
(Multiple Choice)
5.0/5 (73)
(73) Yin-Li is the preparer of the Form 1120 for Cloves Corporation.On the return, Cloves claimed a deduction that the IRS later disallowed on audit.Compute the tax preparer penalty that could be assessed against Yin-Li in each of the following independent situations.
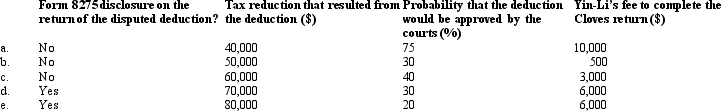
(Essay)
4.9/5 (75)
(75) The general statute of limitations regarding Federal tax returns extends for ____________________ years.It is ____________________ years if a substantial understatement of income is found, and ____________________ years with respect to worthless securities.
or
(Short Answer)
4.8/5 (97)
(97) A tax preparer can incur a penalty if the client's return includes an unreasonable or ___________________ tax return position that understates the tax liability.
(Short Answer)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)