



 Chat with AI
Exam 4: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Ira, a calendar year taxpayer, purchases as an investment stock in Redbird Corporation on November 1, 2013. On February 1, 2014, Redbird Corporation is declared bankrupt, and Ira's stock becomes worthless. Presuming § 1244 (stock in a small business corporation) does not apply, Ira has a short-term capital loss for 2014.
(True/False)
4.9/5  (82)
(82) In structuring the capitalization of a corporation, the tax law is neutral for the investor as to debt versus equity financing.
(True/False)
4.9/5 (83)
(83) A city contributes $500,000 to a corporation as an inducement to locate in the city. Within the next 12 months, the corporation uses the money to purchase property. The corporation has income of $500,000 and must reduce its tax basis in the property by the same amount.
(True/False)
4.7/5 (74)
(74) In a § 351 transaction, if a transferor receives consideration other than stock, the transaction can be taxable.
(True/False)
4.8/5 (69)
(69) Ruth transfers property worth $200,000 (basis of $60,000) to Goldfinch Corporation. In return, she receives 80% of its stock (worth $180,000) and a long-term note, executed by Goldfinch and made payable to Ruth (worth $20,000). Ruth will recognize no gain on the transfer.
(True/False)
4.8/5 (70)
(70) Jane transfers property (basis of $180,000 and fair market value of $500,000) to Green Corporation for 80% of its stock (worth $425,000) and a long-term note (worth $75,000), executed by Green Corporation and made payable to Jane. As a result of the transfer:
(Multiple Choice)
4.9/5 (78)
(78) Art, an unmarried individual, transfers property (basis of $130,000 and fair market value of $120,000) to Condor Corporation in exchange for § 1244 stock. The transfer qualifies as a nontaxable exchange under § 351. Because the property is loss property, Condor takes a basis in the property of $120,000. Five years later, Art sells the Condor stock for $50,000. With respect to the sale, Art has:
(Multiple Choice)
4.7/5 (89)
(89) Gabriella and Maria form Luster Corporation with each receiving 50 shares of its stock. Gabriella transfers cash of $50,000, while Maria transfers a proprietary formula (basis of $0; fair market value of $50,000). Neither Gabriella nor Maria will recognize gain on the transfer.
(True/False)
4.8/5 (84)
(84) In return for legal services worth $60,000 rendered incident to its formation, Crimson Corporation issues stock to Greta, an attorney. Crimson cannot immediately deduct the value of any of this stock but instead must capitalize it as an organizational expenditure.
(True/False)
4.9/5 (93)
(93) A taxpayer may never recognize a loss on the transfer of property in a transaction subject to § 351.
(True/False)
4.8/5 (85)
(85) Sean, a sole proprietor, is engaged in a service business and uses the cash basis of accounting. In the current year, Sean incorporates his business by forming Aqua Corporation. In exchange for all of its stock, Aqua receives: assets (basis of $400,000 and fair market value of $2 million), trade accounts payable of $110,000, and loan due to a bank of $390,000. The proceeds from the bank loan were used by Sean to provide operating funds for the business. Aqua Corporation assumes all of the liabilities transferred to it.
a. Does Sean recognize any gain on the incorporation? Explain.
b. What basis does Sean have in the Aqua stock?
c. What basis does Aqua Corporation have in the assets it receives?
(Essay)
4.8/5 (82)
(82) Wade and Paul form Swan Corporation with the following investments. Wade transfers machinery (basis of $40,000 and fair market value of $100,000), while Paul transfers land (basis of $20,000 and fair market value of $90,000) and services rendered (worth $10,000) in organizing the corporation. Each is issued 25 shares in Swan Corporation. With respect to the transfers:
(Multiple Choice)
4.9/5 (83)
(83) A shareholder transfers a capital asset to Red Corporation for its stock. If the transfer qualifies under § 351, Red's holding period for the asset begins on the day of the exchange.
(True/False)
4.9/5 (81)
(81) Dawn, a sole proprietor, was engaged in a service business and reported her income on a cash basis. Later, she incorporates her business and transfers the assets of the business to the corporation in return for all the stock in the corporation plus the corporation's assumption of the liabilities of her proprietorship. All the receivables and the unpaid trade payables are transferred to the newly formed corporation. The assets of the proprietorship had a basis of $105,000 and fair market value of $300,000. The trade accounts payable totaled $25,000. There was a note payable to the bank in the amount of $95,000 that the corporation assumes. The note was issued for the purchase of computers and other business equipment.
(Multiple Choice)
4.7/5 (90)
(90) Nancy, Guy, and Rod form Goldfinch Corporation with the following consideration.
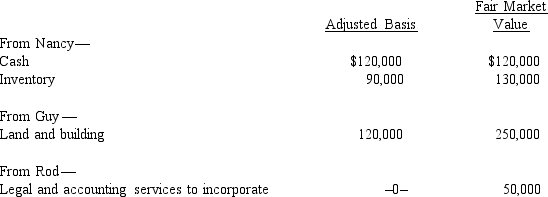 Goldfinch issues its 500 shares of stock as follows: 250 to Nancy, 200 to Guy, and 50 to Rod. In addition, Guy gets $50,000 in cash.
a. Does Nancy, Guy, or Rod recognize gain (or income)?
b. What basis does Guy have in the Goldfinch stock?
c. What basis does Goldfinch Corporation have in the inventory? In the land and building?
d. What basis does Rod have in the Goldfinch stock?
Goldfinch issues its 500 shares of stock as follows: 250 to Nancy, 200 to Guy, and 50 to Rod. In addition, Guy gets $50,000 in cash.
a. Does Nancy, Guy, or Rod recognize gain (or income)?
b. What basis does Guy have in the Goldfinch stock?
c. What basis does Goldfinch Corporation have in the inventory? In the land and building?
d. What basis does Rod have in the Goldfinch stock? (Essay)
4.9/5 (62)
(62) Tina incorporates her sole proprietorship with assets having a fair market value of $100,000 and an adjusted basis of $110,000. Even though § 351 applies, Tina may recognize her realized loss of $10,000.
(True/False)
4.8/5 (72)
(72) To ease a liquidity problem, all of the shareholders of Osprey Corporation contribute additional cash to its capital. Osprey has no tax consequences from the contribution.
(True/False)
4.9/5 (96)
(96) Gabriella and Juanita form Luster Corporation. Gabriella transfers cash of $50,000 for 50 shares of stock, while Juanita transfers information concerning a proprietary process (basis of zero and fair market value of $50,000) for 50 shares of stock.
(Multiple Choice)
4.9/5 (85)
(85) How is the transfer of liabilities in a property transaction generally treated for tax purposes? How is a transfer of liabilities generally treated in a § 351 transaction? What exceptions could arise to this usual treatment in a § 351 setting?
(Essay)
4.7/5 (73)
(73) If a shareholder owns stock received as a gift from her mother, it cannot be § 1244 stock.
(True/False)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)