



 Chat with AI
Exam 4: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


When consideration is transferred to a corporation in return for stock, the definition of "property" is important because tax deferral treatment of § 351 is available only to taxpayers who transfer property.
(True/False)
4.8/5  (79)
(79) Rick transferred the following assets and liabilities to Warbler Corporation. 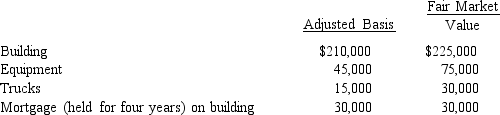 In return, Rick received $75,000 in cash plus 90% of Warbler Corporation's only class of stock outstanding (fair market value of $225,000).
 (Multiple Choice)
4.8/5 (69)
(69) The use of § 351 is not limited to the initial formation of a corporation, and it can apply to later transfers as well.
(True/False)
4.8/5 (82)
(82) Lark City donates land worth $300,000 and cash of $100,000 to Orange Corporation as an inducement to locate in the city. Four months later, Orange purchases additional land and a building at a cost of $500,000 and moves its operations to Lark City. Ann, the sole shareholder, contributes equipment (basis of $70,000 and fair market value of $200,000) to help Orange in its new operations. What are the tax consequences of these transfers to Orange Corporation?
(Essay)
4.9/5 (77)
(77) Joyce, a single taxpayer, transfers property (basis of $120,000 and fair market value of $60,000) to Wren Corporation in exchange for shares of § 1244 stock. As the transfer qualifies under § 351, Joyce takes a $120,000 basis in the Wren stock. In the current year, Joyce sells the Wren Corporation stock for $40,000. What are the consequences of the sale to Joyce?
(Essay)
4.8/5 (72)
(72) Albert transfers land (basis of $140,000 and fair market value of $320,000) to Gold Corporation for 80% of its stock and a note payable in the amount of $80,000. Gold assumes Albert's mortgage on the land of $200,000.
(Multiple Choice)
4.9/5 (80)
(80) Amy owns 20% of the stock of Wren Corporation, which she acquired several years ago at a cost of $10,000. Amy is Vice-President of Wren and earns a salary of $80,000 annually. Last year, Wren Corporation was experiencing financial problems, and Amy loaned the corporation $25,000. In the current year, Wren becomes bankrupt, and both her stock investment and the loan become worthless. Amy has a nonbusiness bad debt deduction this year of $25,000.
(True/False)
5.0/5 (79)
(79) The transfer of an installment obligation in a transaction qualifying under § 351 is a disposition of the obligation that causes gain to be recognized by the transferor.
(True/False)
4.8/5 (81)
(81) Allen transfers marketable securities with an adjusted basis of $120,000, fair market value of $300,000, for 85% of the stock of Heron Corporation. In addition, he receives cash of $40,000. Allen recognizes a capital gain of $40,000 on the transfer.
(True/False)
5.0/5 (67)
(67) George transfers cash of $150,000 to Finch Corporation, a newly formed corporation, for 100% of the stock in Finch worth $80,000 and debt in the amount of $70,000, payable in equal annual installments of $7,000 plus interest at the rate of 9% per annum. In the first year of operation, Finch has net taxable income of $40,000. If Finch pays George interest of $6,300 and $7,000 principal payment on the note:
(Multiple Choice)
4.8/5 (86)
(86) Joe and Kay form Gull Corporation. Joe transfers cash of $250,000 for 200 shares in Gull Corporation. Kay transfers property with a basis of $50,000 and fair market value of $240,000. She agrees to accept 200 shares in Gull Corporation for the property and for providing bookkeeping services to the corporation in its first year of operation. The value of Kay's services is $10,000. With respect to the transfer:
(Multiple Choice)
4.9/5 (81)
(81) In order to encourage the development of an industrial park, a county donates land to Ecru Corporation. The donation does not result in gross income to Ecru.
(True/False)
4.8/5 (77)
(77) Leah transfers equipment (basis of $400,000 and fair market value of $500,000) for additional stock in Crow Corporation. After the transfer, Leah owns 80% of Crow's stock. Associated with the equipment is § 1245 depreciation recapture potential of $70,000. As a result of the transfer:
(Multiple Choice)
4.9/5 (98)
(98) The control requirement under § 351 requires that the person or persons transferring property to the corporation, immediately after the transfer, own stock possessing at least 80% of the total combined voting power of all classes of stock entitled to vote and at least 80% of the total number of shares of all other classes of stock of the corporation.
(True/False)
4.8/5 (85)
(85) Carl transfers land to Cardinal Corporation for 90% of the stock in Cardinal Corporation worth $20,000 plus a note payable to Carl in the amount of $40,000 and the assumption by Cardinal Corporation of a mortgage on the land in the amount of $100,000. The land, which has a basis to Carl of $70,000, is worth $160,000.
(Multiple Choice)
4.7/5 (84)
(84) For § 351 purposes, stock rights and stock warrants are included in the definition of "stock."
(True/False)
4.9/5 (82)
(82) Perry organized Cardinal Corporation 10 years ago by contributing property worth $2 million (basis of $450,000) for 2,500 shares of stock in Cardinal, representing 100% of the stock in the corporation. Perry later gave each of his children, Brittany and Julie, 750 shares of stock in Cardinal Corporation. In the current year, Perry transfers property worth $600,000 (basis of $150,000) to Cardinal for 1,000 shares in the corporation. What gain, if any, will Perry recognize on the transfer?
(Essay)
5.0/5 (70)
(70) Similar to likekind exchanges, the receipt of "boot" under § 351 can cause loss to be recognized.
(True/False)
4.8/5 (71)
(71) When Pheasant Corporation was formed under § 351, Kristen transferred property (basis of $26,000 and fair market value of $22,500) for § 1244 stock. Kristen's basis in the Pheasant stock is $26,000. Three years later, Pheasant Corporation goes bankrupt and its stock becomes worthless. Kristen, who is single, owned the stock as an investment. Kristen's loss is:
(Multiple Choice)
4.8/5 (81)
(81) What is the rationale underlying the tax deferral treatment available under § 351?
(Essay)
5.0/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)