



 Chat with AI
Exam 8: Firms in Perfectly Compitive Markets

Exam 1: Economics Foundations and Models160 Questions
Exam 2: Choices and Trade - Offs in the Market192 Questions
Exam 3: Where Prices Come Frome : The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply226 Questions
Exam 5: Economic Efficiency , Government Price Setting and Taxes187 Questions
Exam 6: Concumer Choice and Behavioural Economics254 Questions
Exam 7: Technology , Production and Costs300 Questions
Exam 8: Firms in Perfectly Compitive Markets270 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition : The Competitive Model in More Realistic Setting255 Questions
Exam 11: Oligopoly : Firms in Less Competitve Markets186 Questions
Exam 12: The Market for Labour and Other Factors of Production253 Questions
Exam 13: International Trade111 Questions
Exam 14: Government Intervention in the Market122 Questions
Exam 15: Externalities , Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy120 Questions
Select questions type


If the market price is $40, the average revenue of selling five units is
(Multiple Choice)
4.9/5  (80)
(80) When plasma television sets were first introduced, prices were high and few firms were in the market. Later, economic profits attracted new firms, and the price of plasma televisions fell. This example illustrates
(Multiple Choice)
4.8/5 (68)
(68)
-Refer to Table 8-1. If the market price of each camera case is $8 and the firm maximises profit, what is the amount of the firm's profit or loss?
(Multiple Choice)
5.0/5 (84)
(84)  -Refer to Figure 8-6. Suppose the firm produces 4000 units. What does the shaded area labeled B represent?
 (Multiple Choice)
4.7/5 (60)
(60) A teenaged babysitter is similar to a firm in a perfectly competitive industry in that, for both,
(Multiple Choice)
4.9/5 (86)
(86) Jason, a high-school student, mows lawns for families in his neighbourhood. The going rate is $12 for each lawn-mowing service. Jason would like to charge $20 because he believes he has more experience mowing lawns than the many other teenagers who also offer the same service. If the market for lawn mowing services is perfectly competitive, what would happen if Jason raised his price?
(Multiple Choice)
4.7/5 (90)
(90) If a firm in a perfectly competitive industry introduces a lower-cost way of producing an existing product, the firm will be able to earn economic profits in the long run.
(True/False)
4.8/5 (81)
(81) Firms in perfect competition produce the productively efficient output level in the short run and in the long run.
(True/False)
4.9/5 (74)
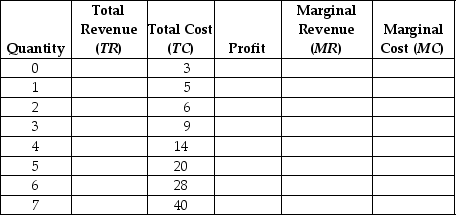
(74) Assuming a market price of $4, fill in the columns in the following table. What is the profit-maximising level of production? What are the two ways to determine the profit-maximising level of production?
(Essay)
4.8/5 (90)
(90) A perfectly competitive apple farm produces 1000 bushels of apples at a total cost of $36 000. The price of each bushel is $50. Calculate the firm's short-run profit or loss.
(Multiple Choice)
4.8/5 (84)
(84) Assume the market for organically-grown produce is perfectly competitive. All else equal, as farmers find it less profitable to produce and sell organic produce in this market,
(Multiple Choice)
4.9/5 (69)
(69) 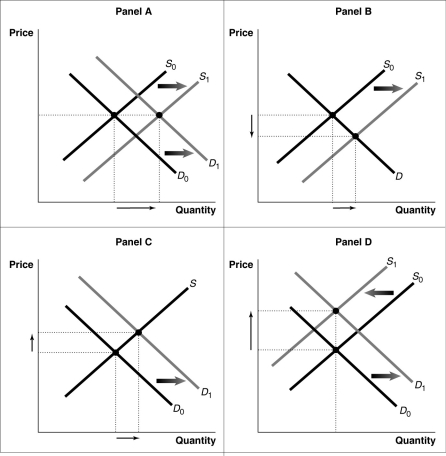 -Refer to Figure 8-13. Assume that the medical screening industry is perfectly competitive and that some firms are incurring short-run losses. Suppose the medical screening industry runs an effective advertising campaign which convinces a large number of people that yearly CT scans are critical for good health. Which of the diagrams in the figure best describes what happens in the industry?
 (Multiple Choice)
4.8/5 (68)
(68)  -Refer to Figure 8-2. Why is the total revenue curve a ray from the origin?
 (Multiple Choice)
4.9/5 (82)
(82) Use the figure above to answer the following questions.
a. How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b. What is the market price?
c. What is the profit-maximising output?
d. What is total revenue at the profit-maximising output?
e. What is the total cost at the profit-maximising output?
f. What is the profit or loss at the profit-maximising output?
g. What is the firm's total fixed cost?
h. What is the total variable cost?
i. Identify the firm's short-run supply curve.
j. Is the industry in a long-run equilibrium?
k. If it is not in long-run equilibrium, what will happen in this industry to restore long-run equilibrium?
l. In long-run equilibrium, what is the firm's profit maximising quantity?
(Essay)
4.9/5 (68)
(68) At the profit-maximising level of output for a perfectly competitive firm, price equals marginal cost. Which of the following is also true?
(Multiple Choice)
5.0/5 (75)
(75)  -Refer to Figure 8-7. At price P3, the firm would produce

Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)