



 Chat with AI
Exam 8: Firms in Perfectly Compitive Markets

Exam 1: Economics Foundations and Models160 Questions
Exam 2: Choices and Trade - Offs in the Market192 Questions
Exam 3: Where Prices Come Frome : The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply226 Questions
Exam 5: Economic Efficiency , Government Price Setting and Taxes187 Questions
Exam 6: Concumer Choice and Behavioural Economics254 Questions
Exam 7: Technology , Production and Costs300 Questions
Exam 8: Firms in Perfectly Compitive Markets270 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition : The Competitive Model in More Realistic Setting255 Questions
Exam 11: Oligopoly : Firms in Less Competitve Markets186 Questions
Exam 12: The Market for Labour and Other Factors of Production253 Questions
Exam 13: International Trade111 Questions
Exam 14: Government Intervention in the Market122 Questions
Exam 15: Externalities , Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy120 Questions
Select questions type


A perfectly competitive firm has to charge the same price as every other firm in the market. Therefore, the firm
(Multiple Choice)
4.9/5  (76)
(76)
-Refer to Table 8-4. If the market price is $45 the firm will produce
(Multiple Choice)
4.9/5 (75)
(75) In the short run, a firm that is operating at a loss has two options. These options are
(Multiple Choice)
4.8/5 (85)
(85) The long-run supply curve for a perfectly competitive, constant-cost industry
(Multiple Choice)
4.7/5 (72)
(72)  -Refer to Figure 8-7. Identify the short-run shut down point for the firm.
 (Multiple Choice)
4.8/5 (92)
(92)  -Refer to Figure 8-2. Suppose the firm is currently producing Q2 units. What happens if it expands output to Q3 units?
 (Multiple Choice)
4.9/5 (80)
(80)
-Refer to Figure 8-2. What is the amount of profit if the firm produces Q2 units?
-Refer to Figure 8-2. What is the amount of profit if the firm produces Q2 units? (Multiple Choice)
4.7/5 (87)
(87) A constant cost, perfectly competitive market is in long-run equilibrium. At present, there are 1000 firms each producing 400 units of output. The price of the good is $60. Now suppose there is a sudden increase in demand for the industry's product which causes the price of the good to rise to $64. In the new long-run equilibrium, how will the average total cost of producing the good compare to what it was before the price of the good rose?
(Multiple Choice)
4.8/5 (76)
(76) Ben's Peanut Shoppe suffers a short-run loss. Ben will not choose to shut down if
(Multiple Choice)
4.9/5 (87)
(87) Fill in the columns in the following table and use the values in the table to determine the profit-maximising level of output.
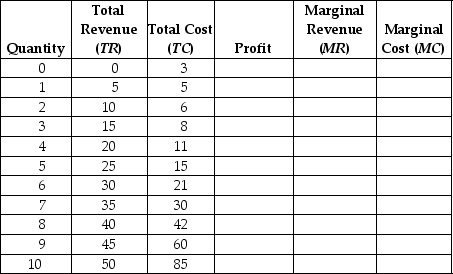
(Essay)
4.7/5 (78)
(78) If a perfectly competitive firm's price is above its average total cost, the firm
(Multiple Choice)
4.8/5 (92)
(92) All of the following can be used to compute average profit except
(Multiple Choice)
4.7/5 (86)
(86) Suppose Veronica sells teapots in the perfectly competitive teapot market. Her output per day and her costs are as follows:
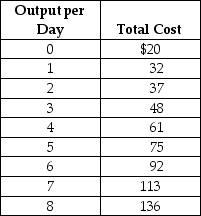 Suppose the current equilibrium price in the teapot market is $15. To maximise profit, how many teapots will Veronica produce, what price will she charge, and how much profit (or loss) will she make? Draw a graph to illustrate your answer. Your graph should include Veronica's demand, ATC, AVC, MC, and MR curves, the price she is charging, the quantity she is producing, and the area representing her profit (or loss).
 (Essay)
4.8/5 (82)
(82) If, as a perfectly competitive industry expands, it can supply larger quantities only at a higher long-run equilibrium price, it is
(Multiple Choice)
4.8/5 (79)
(79)  -Refer to Figure 8-14. Which panel best represents the perfectly competitive organic produce market in which some firms are experiencing short-run losses, and consumers are displaying an increased preference for organic produce?
 (Multiple Choice)
5.0/5 (67)
(67) A very large number of small sellers who sell identical products imply
(Multiple Choice)
4.8/5 (83)
(83) Which of the following describes a situation in which a good or service is produced at the lowest possible cost?
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)