



 Chat with AI
Exam 8: Firms in Perfectly Compitive Markets

Exam 1: Economics Foundations and Models160 Questions
Exam 2: Choices and Trade - Offs in the Market192 Questions
Exam 3: Where Prices Come Frome : The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply226 Questions
Exam 5: Economic Efficiency , Government Price Setting and Taxes187 Questions
Exam 6: Concumer Choice and Behavioural Economics254 Questions
Exam 7: Technology , Production and Costs300 Questions
Exam 8: Firms in Perfectly Compitive Markets270 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition : The Competitive Model in More Realistic Setting255 Questions
Exam 11: Oligopoly : Firms in Less Competitve Markets186 Questions
Exam 12: The Market for Labour and Other Factors of Production253 Questions
Exam 13: International Trade111 Questions
Exam 14: Government Intervention in the Market122 Questions
Exam 15: Externalities , Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy120 Questions
Select questions type


 -Refer to Figure 8-5. The firm's manager suggests that the firm's goal should be to maximise average profit. If the firm does this, what is the amount of profit that it will earn?
 (Multiple Choice)
4.8/5  (86)
(86) The price of a seller's product in perfect competition is determined by
(Multiple Choice)
4.9/5 (78)
(78) If a perfectly competitive firm's total revenue is less than its total variable cost, the firm
(Multiple Choice)
4.8/5 (81)
(81) The marginal revenue curve for a perfectly competitive firm
(Multiple Choice)
4.8/5 (83)
(83) If the long-run average cost curve is U-shaped, the optimal scale of production from society's viewpoint is
(Multiple Choice)
4.9/5 (82)
(82) Which of the following characteristics of a farmers' market make it a good example of a perfectly competitive market?
(Multiple Choice)
4.9/5 (66)
(66) Mark Frost grows apples in a perfectly competitive market. If we drew a line in a graph that illustrates Mark's total revenue from selling apples, it would be
(Multiple Choice)
4.9/5 (89)
(89)  -Refer to Figure 8-8. At the profit-maximising output level, the firm earns
 (Multiple Choice)
5.0/5 (72)
(72) Werner & Sons is a manufacturer of three-ring binders operating in a perfectly competitive industry. Table 8-5 shows the firm's cost schedule.
Table 8-5
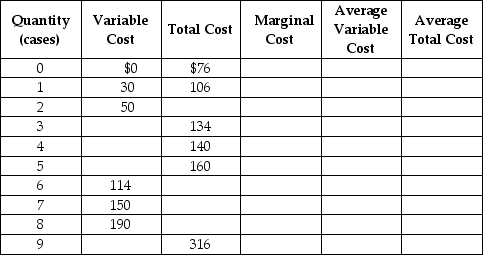 Use the table to answer the following questions.
a. Complete Table 8-5 by filling in the blank cells.
b. Werner is selling in a perfectly competitive market at a price of $40. What is the profit maximising or loss-minimising output?
c. Calculate the firm's profit or loss.
d. Should the firm continue to produce in the short run? Explain.
e. If the firm's fixed costs were $30 higher, what would be the profit-maximising output level in the short run? Indicate whether the output level will increase, decrease or remain unchanged compared to your answer in b.
f. Suppose fixed cost remains at $76. If the price of three-ring binders falls to $20 what is the profit-maximising or loss-minimising output?
g. Calculate the profit or loss. Should the firm continue to produce in the short run? Explain your answer.
h. Suppose the fixed cost remains at $76. What price corresponds to the shut-down point?
i. Suppose the fixed cost remains at $76. What price corresponds to the break-even point?
Use the table to answer the following questions.
a. Complete Table 8-5 by filling in the blank cells.
b. Werner is selling in a perfectly competitive market at a price of $40. What is the profit maximising or loss-minimising output?
c. Calculate the firm's profit or loss.
d. Should the firm continue to produce in the short run? Explain.
e. If the firm's fixed costs were $30 higher, what would be the profit-maximising output level in the short run? Indicate whether the output level will increase, decrease or remain unchanged compared to your answer in b.
f. Suppose fixed cost remains at $76. If the price of three-ring binders falls to $20 what is the profit-maximising or loss-minimising output?
g. Calculate the profit or loss. Should the firm continue to produce in the short run? Explain your answer.
h. Suppose the fixed cost remains at $76. What price corresponds to the shut-down point?
i. Suppose the fixed cost remains at $76. What price corresponds to the break-even point? (Essay)
4.8/5 (98)
(98) 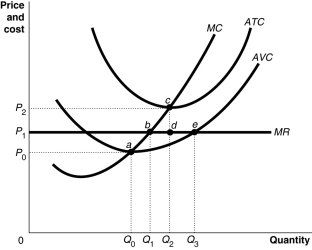 -Refer to Figure 8-11. Suppose the prevailing price is P1 and the firm is currently producing its loss-minimising quantity. If the firm represented in the diagram continues to stay in business, in the long-run equilibrium
 (Multiple Choice)
4.9/5 (74)
(74) Suppose Veronica sells teapots in the perfectly competitive teapot market. Her output per day and her costs are as follows:
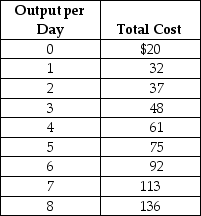 Suppose the current equilibrium price in the teapot market is $20. To maximise profit, how many teapots will Veronica produce, what price will she charge, and how much profit (or loss) will she make? Draw a graph to illustrate your answer. Your graph should include Veronica's demand, ATC, AVC, MC, and MR curves, the price she is charging, the quantity she is producing, and the area representing her profit (or loss).
 (Essay)
4.8/5 (77)
(77) Ted's Pancake Kitchen suffers a short-run loss. When should Ted decide to shut down rather than continue to produce?
(Multiple Choice)
4.8/5 (85)
(85)  -Refer to Figure 8-7. At price P1, the firm would produce
After an increase in demand in a constant-cost industry, firms will find themselves with higher average cost curves.
(True/False)
4.9/5 (81)
(81)  -Refer to Figure 8-4. Assuming the firm is profit maximising, what is the amount of its total fixed cost?
 (Multiple Choice)
4.8/5 (73)
(73) If, for a given output level, a perfectly competitive firm's price is less than its average variable cost, the firm
(Multiple Choice)
4.7/5 (71)
(71) Which of the following is not true for a firm in perfect competition?
(Multiple Choice)
4.9/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)