



 Chat with AI
Exam 8: Firms in Perfectly Compitive Markets

Exam 1: Economics Foundations and Models160 Questions
Exam 2: Choices and Trade - Offs in the Market192 Questions
Exam 3: Where Prices Come Frome : The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply226 Questions
Exam 5: Economic Efficiency , Government Price Setting and Taxes187 Questions
Exam 6: Concumer Choice and Behavioural Economics254 Questions
Exam 7: Technology , Production and Costs300 Questions
Exam 8: Firms in Perfectly Compitive Markets270 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition : The Competitive Model in More Realistic Setting255 Questions
Exam 11: Oligopoly : Firms in Less Competitve Markets186 Questions
Exam 12: The Market for Labour and Other Factors of Production253 Questions
Exam 13: International Trade111 Questions
Exam 14: Government Intervention in the Market122 Questions
Exam 15: Externalities , Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy120 Questions
Select questions type


If the market price is $25 in a perfectly competitive market, the marginal revenue from selling the fifth unit is
(Multiple Choice)
4.7/5  (80)
(80) In a decreasing-cost industry, the entry of new firms lowers average cost at each level of output.
(True/False)
4.7/5 (64)
(64) If a perfectly competitive firm raises the price it charges to consumers, which of the following is the most likely outcome?
(Multiple Choice)
4.8/5 (77)
(77) Which of the following is not a characteristic of a perfectly competitive market structure?
(Multiple Choice)
4.8/5 (68)
(68) 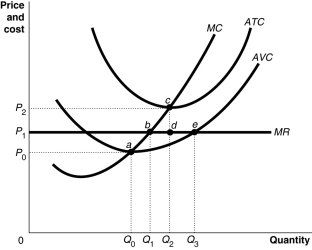 -Refer to Figure 8-11. Suppose the prevailing price is P1 and the firm is currently producing its loss-minimising quantity. In the long-run equilibrium
 (Multiple Choice)
4.8/5 (80)
(80) Suppose there are economies of scale in the production of a specialised memory chip that is used in manufacturing microwaves. This suggests that the microwave industry is a decreasing-cost industry.
(True/False)
4.9/5 (78)
(78)  -Refer to Figure 8-9. Suppose the prevailing price is $20 and the firm is currently producing 1350 units. In the long-run equilibrium, the firm represented in the diagram
 (Multiple Choice)
4.8/5 (90)
(90) If, for the last bushel of apples produced and sold by an apple farm, marginal revenue exceeds marginal cost, then in producing that bushel the farm
(Multiple Choice)
4.8/5 (86)
(86) 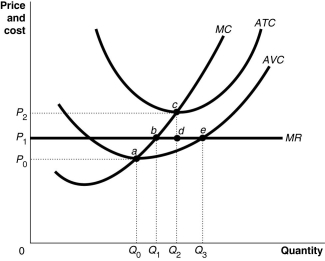 -Refer to Figure 8-16. If the market price is P1, what is the allocatively efficient output level?
 (Multiple Choice)
4.9/5 (77)
(77) If, for a perfectly competitive firm, price exceeds the marginal cost of production, the firm should
(Multiple Choice)
4.7/5 (70)
(70) In analysing the decision to shut down in the short run, we assume that the firm's fixed costs are
(Multiple Choice)
4.8/5 (73)
(73) If in the long run a firm makes zero profit, it should exit the industry.
(True/False)
4.9/5 (107)
(107) Consider the market for wheat which is a perfectly competitive market. Is the market demand curve the same as the demand curve facing an individual producer? If not, explain how and why they are different? Illustrate your answer graphically.
(Essay)
4.8/5 (87)
(87) A perfectly competitive firm produces 3000 units of a good at a total cost of $36 000. The price of each good is $10. Calculate the firm's short-run profit or loss.
(Multiple Choice)
4.9/5 (90)
(90) In August 2008, Ethan Nicholas developed the iShoot application for the apple iPhone 3G, and within five months had earned $800 000 from this program. By May 2009, Nicholas had dropped the price from $4.99 to $1.99 in an attempt to maintain sales. This example indicates that in a competitive market,
(Multiple Choice)
4.7/5 (78)
(78)  -Refer to Figure 8-7. At price P4, the firm would
A wheat farmer and a firm in a perfectly competitive market are similar in that
(Multiple Choice)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)