



 Chat with AI
Exam 8: Firms in Perfectly Compitive Markets

Exam 1: Economics Foundations and Models160 Questions
Exam 2: Choices and Trade - Offs in the Market192 Questions
Exam 3: Where Prices Come Frome : The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply226 Questions
Exam 5: Economic Efficiency , Government Price Setting and Taxes187 Questions
Exam 6: Concumer Choice and Behavioural Economics254 Questions
Exam 7: Technology , Production and Costs300 Questions
Exam 8: Firms in Perfectly Compitive Markets270 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition : The Competitive Model in More Realistic Setting255 Questions
Exam 11: Oligopoly : Firms in Less Competitve Markets186 Questions
Exam 12: The Market for Labour and Other Factors of Production253 Questions
Exam 13: International Trade111 Questions
Exam 14: Government Intervention in the Market122 Questions
Exam 15: Externalities , Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy120 Questions
Select questions type


 -Refer to Figure 8-7. At price P2, the firm would produce

A perfectly competitive firm in long-run equilibrium produces output at the lowest possible average total cost.
(True/False)
4.7/5  (79)
(79) In the long run, a firm in a perfectly competitive industry will supply output only if its total revenue covers its
(Multiple Choice)
4.8/5 (79)
(79) Suppose Veronica sells teapots in the perfectly competitive teapot market. Her output per day and her costs are as follows:
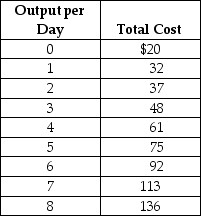 Suppose the current equilibrium price in the teapot market is $10. To maximise profit, how many teapots will Veronica produce, what price will she charge, and how much profit (or loss) will she make? Draw a graph to illustrate your answer. Your graph should include Veronica's demand, ATC, AVC, MC, and MR curves, the price she is charging, the quantity she is producing, and the area representing her profit (or loss).
 (Essay)
4.8/5 (87)
(87) What characteristic of a competitive market has made the 'long run pretty short' in the market for iPhone applications?
(Multiple Choice)
5.0/5 (86)
(86) For a perfectly competitive firm, at the profit-maximising output, average revenue equals marginal cost.
(True/False)
4.9/5 (81)
(81)  -Refer to Figure 8-5. If the market price is $20, what is the amount of the firm's profit?
 (Multiple Choice)
5.0/5 (83)
(83) A firm would decide to shut down if its production resulted in
(Multiple Choice)
4.8/5 (87)
(87) Firms in perfectly competitive industries are unable to control the prices of the products they sell and earn a profit in the long run. Which of the following is one reason for this?
(Multiple Choice)
4.9/5 (93)
(93)  -Refer to Figure 8-4. If the market price is $30 and if the firm is producing output, what is the amount of its total variable cost?
 (Multiple Choice)
4.8/5 (83)
(83) Allocative efficiency is achieved in an industry when firms supply those goods and services that provide consumers with a marginal benefit equal to the marginal cost of producing those goods and services.
(True/False)
4.8/5 (80)
(80) A perfectly competitive firm's marginal revenue curve is downward sloping.
(True/False)
4.8/5 (70)
(70) In the long run, perfectly competitive firms earn zero economic profit. Why do firms enter an industry when they know that in the long run they will not earn any profit?
(Essay)
4.8/5 (82)
(82) 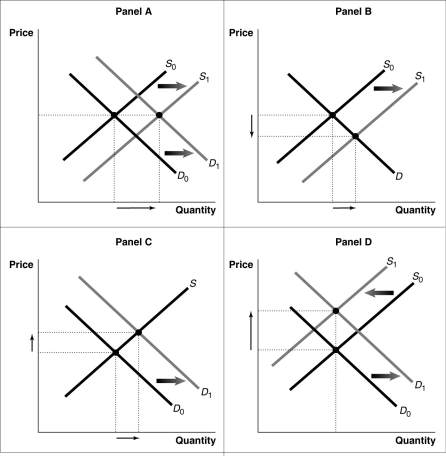 -Refer to Figure 8-10. Consider a typical firm in a perfectly competitive industry that makes short-run profits. Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (72)
(72)  -Refer to Figure 8-2. The firm breaks even at an output level of
 (Multiple Choice)
4.9/5 (89)
(89)
-Refer to Figure 8-5. If the firm's fixed cost increases by $1000 due to a new environmental regulation, what happens in the diagram above?
-Refer to Figure 8-5. If the firm's fixed cost increases by $1000 due to a new environmental regulation, what happens in the diagram above? (Multiple Choice)
4.8/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)