



 Chat with AI
Exam 9: Competitive Markets for Goods and Services

Exam 1: Economics: The Study of Choice145 Questions
Exam 2: Confronting Scarcity: Choices in Production198 Questions
Exam 3: Demand and Supply251 Questions
Exam 4: Applications of Supply and Demand113 Questions
Exam 5: Elasticity: a Measure of Response255 Questions
Exam 6: Markets, Maximizers, and Efficiency239 Questions
Exam 7: The Analysis of Consumer Choice244 Questions
Exam 8: Production and Cost227 Questions
Exam 9: Competitive Markets for Goods and Services265 Questions
Exam 10: Monopoly234 Questions
Exam 11: The World of Imperfect Competition237 Questions
Exam 12: Wages and Employment in Perfect Competition189 Questions
Exam 13: Interest Rates and the Markets for Capital and Natural Resources170 Questions
Exam 14: Imperfectly Competitive Markets for Factors of Production183 Questions
Exam 15: Public Finance and Public Choice188 Questions
Exam 16: Antitrust Policy and Business Regulation137 Questions
Exam 17: International Trade186 Questions
Exam 18: The Economics of the Environment148 Questions
Exam 19: Inequality, Poverty, and Discrimination140 Questions
Select questions type


In the short run, a perfectly competitive firm produces output and earns an economic profit if:
(Multiple Choice)
5.0/5  (84)
(84) Use the following to answer question(s):
Exhibit: The Market for Carrots
 -(Exhibit: The Market for Carrots) Assume that this is a perfectly competitive market and the original price is determined by D1 and S. If the demand shifts to D2, any firm could enter this market and:
 (Multiple Choice)
4.7/5 (71)
(71) Accountants use only _______ costs in their computations of short-run total cost.
(Multiple Choice)
4.9/5 (83)
(83) If all firms in a perfectly competitive industry earn zero economic profits, in the long run, the:
(Multiple Choice)
4.9/5 (75)
(75) If all firms in a perfectly competitive industry earn zero economic profits, in the long run, the:
(Multiple Choice)
4.9/5 (75)
(75) Suppose that the market for candy canes operates under conditions of perfect competition, that it is initially in long-run equilibrium, and that the price of each candy cane is $0.10. Now suppose that the price of sugar rises, increasing the marginal and average total costs of producing candy canes by $0.05. Based on the information given, we can conclude that in the short run a typical producer of candy canes will be making:
(Multiple Choice)
4.9/5 (99)
(99) People in the eastern part of Beirut are prevented by border guards from traveling to the western part of Beirut to shop for food. This situation violates the perfect competition assumption of:
(Multiple Choice)
4.9/5 (70)
(70) Discuss and explain what happens when a firm in perfect competition is making positive economic profit. Use graphs to support your answer. Do the same for a firm that is producing where P < ATC yet P > minimum AVC. Explain what a firm will do if P < minimum AVC.
(Essay)
4.9/5 (85)
(85) Use the following to answer question(s):
Exhibit: Total Revenue, Total Cost, and Economic Profit
 -(Exhibit: Total Revenue, Total Costs, and Economic Profit) Total revenue and total cost are equal at approximately _______ pounds and $_______ .
 (Multiple Choice)
4.8/5 (89)
(89) Use the following to answer question(s):
Exhibit: Total Revenue, Total Cost, and Economic Profit
-(Exhibit: Total Revenue, Total Costs, and Economic Profit) As output exceeds approximately ________ pounds, economic profits _______ as long as _______ rise faster than _______ .
-(Exhibit: Total Revenue, Total Costs, and Economic Profit) As output exceeds approximately ________ pounds, economic profits _______ as long as _______ rise faster than _______ . (Multiple Choice)
4.8/5 (76)
(76) Suppose that the market for candy canes operates under conditions of perfect competition, that it is initially in long-run equilibrium, and that the price of each candy cane is $0.10. Based on the information given, we can conclude that the average revenue for candy canes:
(Multiple Choice)
4.7/5 (70)
(70) Use the following to answer question(s):
Exhibit: Supply: Short and Long Run
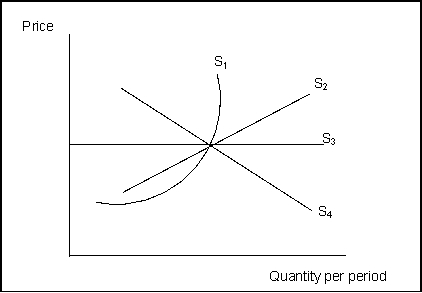 -(Exhibit: Supply: Short and Long Run) S3 would be the _______-run supply curve if _______.
 (Multiple Choice)
4.8/5 (78)
(78) A perfectly competitive industry's market supply curve is the sum of the supply curves of all firms in the industry.
(True/False)
4.7/5 (72)
(72) Which of the following is not an assumption economists make when using the model of perfect competition?
(Multiple Choice)
4.8/5 (82)
(82) Use the following to answer question(s):
Exhibit: A Perfectly Competitive Firm in the Short Run
 -(Exhibit: A Perfectly Competitive Firm in the Short Run) The lowest price that will yield zero economic profits is indicated by the distance:
 (Multiple Choice)
4.8/5 (76)
(76) Use the following to answer question(s):
Exhibit: Short-Run Costs
 -(Exhibit: Short-Run Costs) This firm's supply curve begins at quantity:
 (Multiple Choice)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)