



 Chat with AI
Exam 9: Competitive Markets for Goods and Services

Exam 1: Economics: The Study of Choice145 Questions
Exam 2: Confronting Scarcity: Choices in Production198 Questions
Exam 3: Demand and Supply251 Questions
Exam 4: Applications of Supply and Demand113 Questions
Exam 5: Elasticity: a Measure of Response255 Questions
Exam 6: Markets, Maximizers, and Efficiency239 Questions
Exam 7: The Analysis of Consumer Choice244 Questions
Exam 8: Production and Cost227 Questions
Exam 9: Competitive Markets for Goods and Services265 Questions
Exam 10: Monopoly234 Questions
Exam 11: The World of Imperfect Competition237 Questions
Exam 12: Wages and Employment in Perfect Competition189 Questions
Exam 13: Interest Rates and the Markets for Capital and Natural Resources170 Questions
Exam 14: Imperfectly Competitive Markets for Factors of Production183 Questions
Exam 15: Public Finance and Public Choice188 Questions
Exam 16: Antitrust Policy and Business Regulation137 Questions
Exam 17: International Trade186 Questions
Exam 18: The Economics of the Environment148 Questions
Exam 19: Inequality, Poverty, and Discrimination140 Questions
Select questions type


If a perfectly competitive firm is producing a quantity that generates P < MC, then profit:
(Multiple Choice)
4.9/5  (69)
(69) Suppose that pasta is produced under conditions of perfect competition and that the constant-cost industry is initially in long-run equilibrium. Now suppose there is an increase in the price of wheat, which is a key ingredient in producing pasta. Further assume that the price elasticity of demand for pasta is -1.8. After all long-run adjustments have occurred, we would expect total consumer spending on pasta to have:
(Multiple Choice)
4.9/5 (75)
(75) Suppose that the market for candy canes operates under conditions of perfect competition, that it is initially in long-run equilibrium, and that the price of each candy cane is $0.10. Based on the information given, we can conclude that a typical producer of candy canes is experiencing:
(Multiple Choice)
4.9/5 (60)
(60) A perfectly competitive firm's short-run supply curve is its:
(Multiple Choice)
4.9/5 (72)
(72) A reduction in variable production costs shifts the firm's _______ and _______ curves _______ in the short run.
(Multiple Choice)
4.9/5 (72)
(72) If price is less than average variable cost at the profit-maximizing quantity of output in the short run, a perfectly competitive firm will:
(Multiple Choice)
4.8/5 (91)
(91) Use the following to answer question(s):
Exhibit: The Market for Carrots
 -(Exhibit: The Market for Carrots) If demand is D1, the price of carrots will be _______ cents, the quantity demanded will be _______ , and the quantity supplied will be _______ .
 (Multiple Choice)
4.9/5 (91)
(91) If a perfectly competitive firm is producing a quantity that generates P = MC, then profit:
(Multiple Choice)
4.9/5 (78)
(78) If an industry experiences constant costs as industry output expands, the long-run industry supply curve will be:
(Multiple Choice)
4.8/5 (78)
(78) In the short run, a perfectly competitive firm produces output and incurs an economic loss if:
(Multiple Choice)
4.8/5 (91)
(91) Use the following to answer question(s):
Exhibit: Profit Maximizing
 -(Exhibit: Profit Maximizing) The exhibit shows cost curves for a firm operating in a perfectly competitive market. If the market price is P4, the firm will produce quantity _______ and _______ in the short run.
 (Multiple Choice)
4.9/5 (73)
(73) The primary application of the model of perfect competition is to predict how firms will respond to changes in demand and production costs.
(True/False)
4.8/5 (95)
(95) If a firm in perfect competition sells 500 units of a product at $10 per unit, its marginal revenue per unit is $10.
(True/False)
4.9/5 (74)
(74) Discuss and explain how the marginal decision rule, MR = MC, will result in profit maximization for the firm in perfect competition. Why can economic profit exist in the short run but not in the long run?
(Essay)
4.7/5 (70)
(70) Provided that there are no external benefits or costs, in the long run, perfect competition will result in an efficient allocation of resources because P = MC.
(True/False)
4.9/5 (85)
(85) The firm's supply curve in perfect competition is the MC curve.
(True/False)
4.9/5 (89)
(89) Use the following to answer question(s):
Exhibit: Supply: Short and Long Run
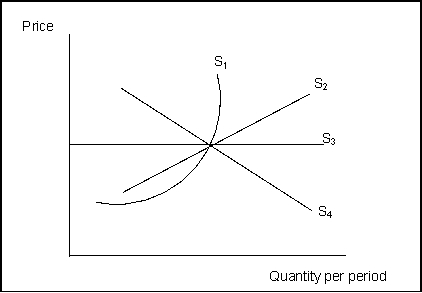 -(Exhibit: Supply: Short and Long Run) If industry expansion tends to increase production costs, then the relevant long-run supply curve is:
 (Multiple Choice)
4.8/5 (92)
(92) If a perfectly competitive industry is characterized by increasing cost in the long run, its long-run:
(Multiple Choice)
4.9/5 (62)
(62) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)