



 Chat with AI
Exam 9: Competitive Markets for Goods and Services

Exam 1: Economics: The Study of Choice145 Questions
Exam 2: Confronting Scarcity: Choices in Production198 Questions
Exam 3: Demand and Supply251 Questions
Exam 4: Applications of Supply and Demand113 Questions
Exam 5: Elasticity: a Measure of Response255 Questions
Exam 6: Markets, Maximizers, and Efficiency239 Questions
Exam 7: The Analysis of Consumer Choice244 Questions
Exam 8: Production and Cost227 Questions
Exam 9: Competitive Markets for Goods and Services265 Questions
Exam 10: Monopoly234 Questions
Exam 11: The World of Imperfect Competition237 Questions
Exam 12: Wages and Employment in Perfect Competition189 Questions
Exam 13: Interest Rates and the Markets for Capital and Natural Resources170 Questions
Exam 14: Imperfectly Competitive Markets for Factors of Production183 Questions
Exam 15: Public Finance and Public Choice188 Questions
Exam 16: Antitrust Policy and Business Regulation137 Questions
Exam 17: International Trade186 Questions
Exam 18: The Economics of the Environment148 Questions
Exam 19: Inequality, Poverty, and Discrimination140 Questions
Select questions type


Profit computed using explicit costs as the only measure of costs is:
(Multiple Choice)
4.8/5  (76)
(76) Suppose that the market for candy canes operates under conditions of perfect competition, that it is initially in long-run equilibrium, and that the price of each candy cane is $0.10. Based on the information given, we can conclude that the marginal revenue for candy canes:
(Multiple Choice)
4.9/5 (72)
(72) Use the following to answer question(s):
Exhibit: Perfectly Competitive Firm
 -(Exhibit: Perfectly Competitive Firm) The exhibit shows a perfectly competitive firm that faces demand curve d, has the cost curves shown, and maximizes profit. The firm's total revenue per day is:
 (Multiple Choice)
4.8/5 (71)
(71) Use the following to answer question(s):
Exhibit: Profit Maximizing
 -(Exhibit: Profit Maximizing) The exhibit shows cost curves for a firm operating in a perfectly competitive market. At quantity q5, AVC is the same as: _______ .
 (Multiple Choice)
5.0/5 (80)
(80) Suppose that some firms in a perfectly competitive industry are incurring negative economic profits. The:
(Multiple Choice)
4.9/5 (71)
(71) In the short run, if AVC < P < ATC, a perfectly competitive firm:
(Multiple Choice)
4.8/5 (91)
(91) Suppose that the market for candy canes operates under conditions of perfect competition, that it is initially in long-run equilibrium, and that the price of each candy cane is $0.10. Now suppose that the price of sugar rises, increasing the marginal and average total cost of producing candy canes by $0.05; there are no other changes in production costs. Based on the information given, we can conclude that once all the adjustments to long-run equilibrium are achieved, the price of candy canes will equal:
(Multiple Choice)
4.9/5 (80)
(80) Suppose that the market for haircuts in a community is perfectly competitive and that the market is initially in long-run equilibrium. Subsequently, an increase in population increases the demand for haircuts. In the short run, we expect that the typical firm is likely to begin:
(Multiple Choice)
4.9/5 (78)
(78) Use the following to answer question(s):
Exhibit: Supply: Short and Long Run
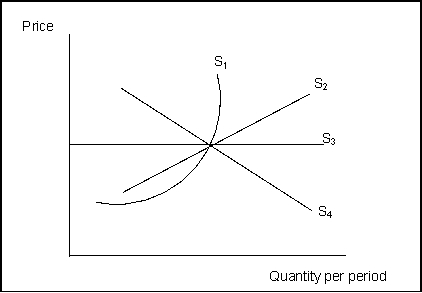 -(Exhibit: Supply: Short and Long Run) S1 is a short-run supply curve and is the _______ of individual firms' _______ .
 (Multiple Choice)
4.9/5 (73)
(73) Use the following to answer question(s):
Exhibit: Profit Maximizing
-(Exhibit: Profit Maximizing) The exhibit shows cost curves for a firm operating in a perfectly competitive market. Curve M is the _______ curve.
-(Exhibit: Profit Maximizing) The exhibit shows cost curves for a firm operating in a perfectly competitive market. Curve M is the _______ curve. (Multiple Choice)
4.9/5 (87)
(87) Use the following to answer question(s):
Exhibit: Total Revenue and Total Cost
 -(Exhibit: Total Revenue and Cost) Total cost at the most profitable level of output is given by point:
 (Multiple Choice)
4.9/5 (95)
(95) Explain why each of the following statements is false. What needs to be changed in each case to make the statement correct?
a. The competitive firm sets its price so that P = MC.
b. A firm will shut down when price is less than average cost.
c. Profits are profits, whether they are accounting or economic profits.
d. Costs are costs, whether they are implicit or explicit-they are still costs.
e. The supply curve for the firm in perfect competition is its marginal cost curve.
(Essay)
4.8/5 (89)
(89) Suppose that the market for computers is dominated by a single firm, like Dell, that is able to exert influence over prices and output. This situation violates the perfect competition assumption of:
(Multiple Choice)
4.9/5 (75)
(75) If a perfectly competitive firm is producing a quantity that generates MC = MR, then profit:
(Multiple Choice)
4.7/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)