



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


Investing in a zero-coupon asset with a maturity equal to the desired investment horizon removes interest rate risk from the investment management process.
(True/False)
4.8/5  (82)
(82) What is the percentage price change for the bond if interest rates decline 50 basis points from the original 5 percent?
(Multiple Choice)
4.9/5 (92)
(92) Market value accounting reflects economic reality of an FIs balance sheet.
(True/False)
4.9/5 (68)
(68) The following is an FI's balance sheet ($millions).
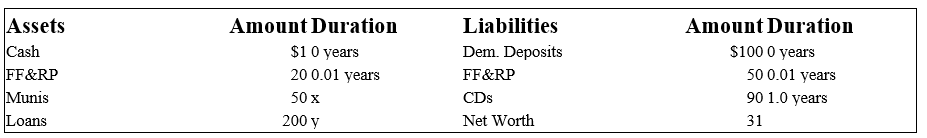 Notes to Balance Sheet.
Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. CDs are 1-year pure discount certificates of deposit paying 4.75 percent.
-What is this bank's interest rate risk exposure,if any?
Notes to Balance Sheet.
Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. CDs are 1-year pure discount certificates of deposit paying 4.75 percent.
-What is this bank's interest rate risk exposure,if any? (Multiple Choice)
4.9/5 (88)
(88) The use of duration to predict changes in bond prices for given changes in interest rate changes will always underestimate the amount of the true price change.
(True/False)
4.8/5 (66)
(66) Perfect matching of the maturities of the assets and liabilities will always achieve perfect immunization for the equity holders of an FI against interest rate risk.
(True/False)
4.8/5 (88)
(88) 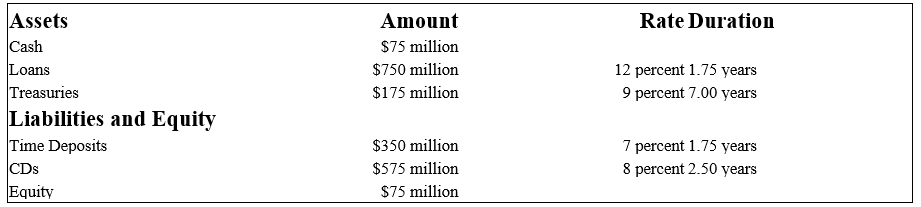 -Calculate the duration of the assets to four decimal places.
 (Multiple Choice)
4.7/5 (93)
(93) The error from using duration to estimate the new price of a fixed-income security will be less as the amount of convexity increases.
(True/False)
4.9/5 (79)
(79) The following information is about current spot rates for Second Duration Savings' assets (loans) and liabilities (CDs). All interest rates are fixed and paid annually.  -What is the duration of this Treasury note?
 (Multiple Choice)
4.8/5 (85)
(85) The numbers provided by Fourth Bank of Duration are in thousands of dollars.
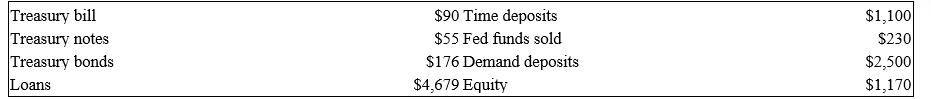 Notes: All Treasury bills have six months until maturity.One-year Treasury notes are priced at par and have a coupon of 7 percent paid semiannually.Treasury bonds have an average duration of 4.5 years and the loan portfolio has a duration of 7 years.Time deposits have a 1-year duration and the Fed funds duration is 0.003 years.Fourth Bank of Duration assigns a duration of zero (0)to demand deposits.
-If the relative change in interest rates is a decrease of 1 percent,calculate the impact on the bank's market value of equity using the duration approximation. (That is, R/(1 + R)= -1 percent)
Notes: All Treasury bills have six months until maturity.One-year Treasury notes are priced at par and have a coupon of 7 percent paid semiannually.Treasury bonds have an average duration of 4.5 years and the loan portfolio has a duration of 7 years.Time deposits have a 1-year duration and the Fed funds duration is 0.003 years.Fourth Bank of Duration assigns a duration of zero (0)to demand deposits.
-If the relative change in interest rates is a decrease of 1 percent,calculate the impact on the bank's market value of equity using the duration approximation. (That is, R/(1 + R)= -1 percent) (Multiple Choice)
4.7/5 (75)
(75) For given changes in interest rates,the change in the market value of net worth of an FI is equal to the difference between the changes in the market value of the assets and market value of the liabilities.
(True/False)
4.9/5 (81)
(81) When does "duration" become a less accurate predictor of expected change in security prices?
(Multiple Choice)
5.0/5 (77)
(77) The larger the interest rate shock,the smaller the interest rate risk exposure of an FI.
(True/False)
4.7/5 (83)
(83) The following is an FI's balance sheet ($millions).
Notes to Balance Sheet.
Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. CDs are 1-year pure discount certificates of deposit paying 4.75 percent.
-What will be the impact,if any,on the market value of the bank's equity if all interest rates increase by 75 basis points?
Notes to Balance Sheet.
Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. CDs are 1-year pure discount certificates of deposit paying 4.75 percent.
-What will be the impact,if any,on the market value of the bank's equity if all interest rates increase by 75 basis points? (Multiple Choice)
4.9/5 (82)
(82) Consider a one-year maturity,$100,000 face value bond that pays a 6 percent fixed coupon annually.What is the price of the bond if market interest rates are 7 percent?
(Multiple Choice)
4.9/5 (88)
(88) Calculate the duration of a two-year corporate loan paying 6 percent interest annually,selling at par.The $30,000,000 loan is 100 percent amortizing with annual payments.
(Multiple Choice)
4.9/5 (74)
(74) The fact that the capital gain effect for rate decreases is greater than the capital loss effect for rate increases is caused by convexity in the yield-price relationship.
(True/False)
4.8/5 (84)
(84) Duration is the weighted-average present value of the cash flows using the timing of the cash flows as weights.
(True/False)
4.8/5 (78)
(78) The rate of change in duration values is less than the rate of change in maturity.
(True/False)
4.8/5 (85)
(85) As the investment horizon approaches,the duration of an unrebalanced portfolio that originally was immunized will be less than the time remaining to the investment horizon.
(True/False)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)