



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


The numbers provided by Fourth Bank of Duration are in thousands of dollars.
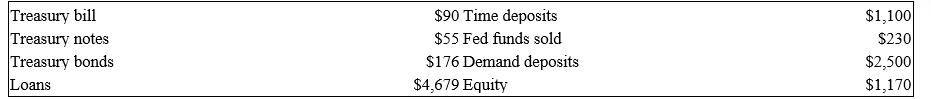 Notes: All Treasury bills have six months until maturity.One-year Treasury notes are priced at par and have a coupon of 7 percent paid semiannually.Treasury bonds have an average duration of 4.5 years and the loan portfolio has a duration of 7 years.Time deposits have a 1-year duration and the Fed funds duration is 0.003 years.Fourth Bank of Duration assigns a duration of zero (0)to demand deposits.
-What is the bank's leverage adjusted duration gap?
Notes: All Treasury bills have six months until maturity.One-year Treasury notes are priced at par and have a coupon of 7 percent paid semiannually.Treasury bonds have an average duration of 4.5 years and the loan portfolio has a duration of 7 years.Time deposits have a 1-year duration and the Fed funds duration is 0.003 years.Fourth Bank of Duration assigns a duration of zero (0)to demand deposits.
-What is the bank's leverage adjusted duration gap? (Multiple Choice)
4.8/5  (77)
(77) U.S. Treasury quotes from the WSJ on Oct. 15, 2003:  -What is the duration of the above Treasury note? Use the asked price to calculate the duration.Recall that Treasuries pay interest semiannually.
 (Multiple Choice)
4.9/5 (85)
(85) Immunizing net worth from interest rate risk using duration matching requires that the duration match must be realigned periodically as the maturity horizon approaches.
(True/False)
4.9/5 (77)
(77) The difference between the changes in the market value of assets and market value of liabilities for a given change in interest rates is,by definition,the change in the FI's net worth.
(True/False)
4.8/5 (74)
(74) The following is an FI's balance sheet ($millions).
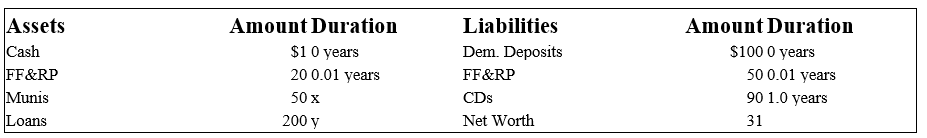 Notes to Balance Sheet.
Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. CDs are 1-year pure discount certificates of deposit paying 4.75 percent.
-What is the duration of the municipal notes (the value of x)?
Notes to Balance Sheet.
Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. CDs are 1-year pure discount certificates of deposit paying 4.75 percent.
-What is the duration of the municipal notes (the value of x)? (Multiple Choice)
4.7/5 (68)
(68) Which of the following statements about leverage-adjusted duration gap is true?
(Multiple Choice)
4.8/5 (85)
(85) For small change in interest rates,market prices of bonds are inversely proportional to their
(Multiple Choice)
4.9/5 (83)
(83) The value for duration describes the percentage increase in the price of a fixed-income asset for a given increase in the required yield or interest rate.
(True/False)
4.8/5 (91)
(91) Managers can achieve the results of duration matching by using these to hedge interest rate risk.
(Multiple Choice)
4.7/5 (60)
(60) A bond is scheduled to mature in five years.Its coupon rate is 9 percent with interest paid annually.This $1,000 par value bond carries a yield to maturity of 10 percent.What is the bond's current market price?
(Multiple Choice)
4.8/5 (91)
(91) Calculate the duration of a two-year corporate bond paying 6 percent interest annually,selling at par.Principal of $20,000,000 is due at the end of two years.
(Multiple Choice)
4.9/5 (81)
(81) Calculate the modified duration of a two-year corporate loan paying 6 percent interest annually.The $40,000,000 loan is 100 percent amortizing,and the current yield is 9 percent annually.
(Multiple Choice)
4.9/5 (71)
(71) What is the impact on the dealer's market value of equity per $100 of assets if the change in all interest rates is an increase of 0.5 percent? [i.e. , R = 0.5 percent]
(Multiple Choice)
4.9/5 (74)
(74) The cost in terms of both time and money to restructure the balance sheet of large and complex FIs has decreased over time.
(True/False)
4.7/5 (69)
(69) Third Duration Investments has the following assets and liabilities on its balance sheet. The two-year Treasury notes are zero coupon assets. Interest payments on all other assets and liabilities occur at maturity. Assume 360 days in a year. 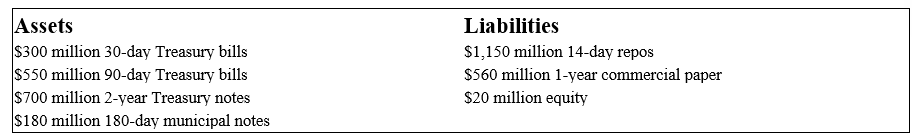 -What is the duration of this bond?
 (Multiple Choice)
4.8/5 (63)
(63) What is the duration of an 8 percent annual payment two-year note that currently sells at par?
(Multiple Choice)
5.0/5 (62)
(62) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)