



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


The larger the size of an FI,the larger the _________ from any given interest rate shock.
(Multiple Choice)
4.7/5  (79)
(79) The numbers provided are in millions of dollars and reflect market values: 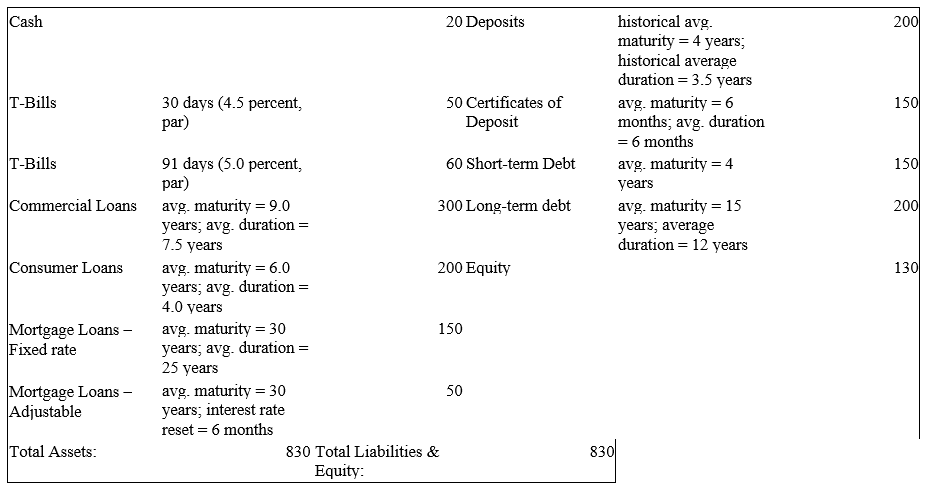 -What is the weighted average duration of the liabilities of the FI?
 (Multiple Choice)
4.8/5 (71)
(71) A key assumption of Macaulay duration is that the yield curve is flat so that all cash flows are discounted at the same discount rate.
(True/False)
4.9/5 (78)
(78) What is the effect of a 100 basis point increase in interest rates on the market value of equity of the FI? Use the duration approximation relationship.Assume r = 4 percent.
(Multiple Choice)
4.7/5 (87)
(87) The following information is about current spot rates for Second Duration Savings' assets (loans) and liabilities (CDs). All interest rates are fixed and paid annually.  -If interest rates increase by 20 basis points (i.e. , R = 20 basis points),use the duration approximation to determine the approximate price change for the Treasury note.
 (Multiple Choice)
4.9/5 (89)
(89) Using a fixed-rate bond to immunize a desired investment horizon means that the reinvested coupon payments are not affected by changes in market interest rates.
(True/False)
4.9/5 (78)
(78) If all interest rates decline 90 basis points ( R/(1 + R)= -90 basis points),what is the change in the market value of equity?
(Multiple Choice)
4.9/5 (69)
(69) First Duration Bank has the following assets and liabilities on its balance sheet: 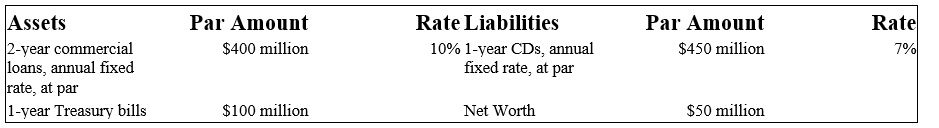 -What is the duration of the commercial loans?
 (Multiple Choice)
4.9/5 (75)
(75) Buying a fixed-rate asset whose duration is exactly equal to the desired investment horizon immunizes against interest rate risk.
(True/False)
4.9/5 (80)
(80) 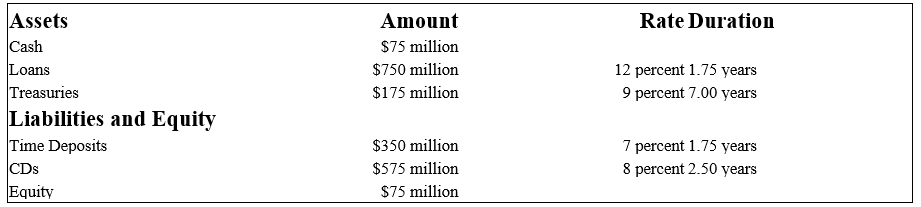 -Calculate the duration of the liabilities to four decimal places.
 (Multiple Choice)
4.8/5 (89)
(89) For a given maturity fixed-income asset,duration decreases as the market yield increases.
(True/False)
4.9/5 (77)
(77) Duration measures the average life of a financial asset or financial liability.
(True/False)
4.8/5 (78)
(78) The leverage adjusted duration of a typical depository institution is positive.
(True/False)
4.9/5 (79)
(79) Suppose a pension fund must have $10,000,000 five years from now to make required payments to retirees.If the pension wants to guarantee the funds are available regardless of future interest rate changes,it should
(Multiple Choice)
4.8/5 (69)
(69) What is the price of the bond if market interest rates are 4 percent?
(Multiple Choice)
4.8/5 (86)
(86) Attempts to satisfy the objectives of shareholders and regulators requires the bank to use the same duration match in the protection of net worth from interest rate risk.
(True/False)
4.8/5 (88)
(88) For a given change in required yields,short-duration securities suffer a smaller capital loss or receive a smaller capital gain than do long-duration securities.
(True/False)
4.7/5 (61)
(61) The following information is about current spot rates for Second Duration Savings' assets (loans) and liabilities (CDs). All interest rates are fixed and paid annually.
-If rates do not change,the balance sheet position that maximizes the FI's returns is
-If rates do not change,the balance sheet position that maximizes the FI's returns is (Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)