



 Chat with AI
Exam 10: Credit Risk: Individual Loan Risk

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


A secured loan has a claim to specific assets of the borrower in the case of default.

Free
(True/False)
4.8/5  (80)
(80) Correct Answer: Verified
True
Equity holders of a levered corporation have no incentive to invest the borrowed funds in risky capital investments.
Free
(True/False)
4.9/5 (73)
(73) Correct Answer:Verified
VerifiedFalse
The condition of no arbitrage profits implies that profits cannot be made without taking some risk.
Free
(True/False)
4.9/5 (75)
(75) Correct Answer:Verified
VerifiedTrue
Borrower reputation is important in assessing credit quality because
(Multiple Choice)
4.7/5 (69)
(69) A major difficulty in estimating RAROC for a loan is the measurement of individual loan risk.
(True/False)
4.9/5 (86)
(86) Junk bonds are bonds that are rated less than investment grade by bond-rating agencies.
(True/False)
4.9/5 (81)
(81) What does the Moody's Analytics model use as equivalent to holding a call option on the assets of the firm?
(Multiple Choice)
5.0/5 (81)
(81) During the decade of the 1990s the asset quality of U.S.banks continued to improve.
(True/False)
4.9/5 (90)
(90) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
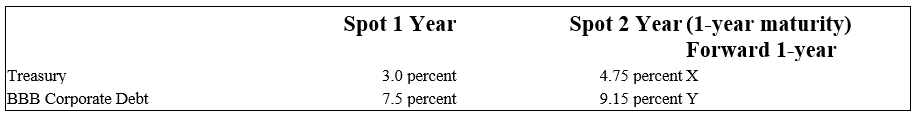 -The duration of a soon to be approved loan of $10 million is four years.The 99th percentile increase in risk premium for bonds belonging to the same risk category of the loan has been estimated to be 5.5 percent. What is the estimated risk-adjusted return on capital (RAROC)of this loan.
 (Multiple Choice)
4.7/5 (77)
(77) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
-Using the term structure of default probabilities,the implied default probability for BBB corporate debt during the current year is
-Using the term structure of default probabilities,the implied default probability for BBB corporate debt during the current year is (Multiple Choice)
4.9/5 (63)
(63) The cumulative default probability of a borrower in a given time period is one minus the product of the marginal default probabilities for all time periods up to that time period.
(True/False)
4.9/5 (77)
(77) Suppose that the financial ratios of a potential borrowing firm took the following values:
X1 = 0.30
X2 = 0
X3 = -0.30
X4 = 0.15
X5 = 2.1
Altman's discriminant function takes the form:
Z = 1.2 X1+ 1.4 X2 + 3.3 X3 + 0.6 X4 + 1.0 X5
The Z score for the firm would be
(Multiple Choice)
4.9/5 (76)
(76) Using a modified discriminant function similar to Altman's,Burger Bank estimates the following coefficients for its portfolio of loans:
Z = 1.4X1 + 1.09X2 + 1.5X3
where X1 = debt to asset ratio;X2 = net income and X3 = dividend payout ratio.
Using Z = 1.682 as the cut-off rate,what should be the debt to asset ratio of the firm in order for the bank to approve the loan?
(Multiple Choice)
4.9/5 (81)
(81) Suppose that the financial ratios of a potential borrowing firm took the following values:
X1 = 0.30
X2 = 0
X3 = -0.30
X4 = 0.15
X5 = 2.1
Altman's discriminant function takes the form:
Z = 1.2 X1+ 1.4 X2 + 3.3 X3 + 0.6 X4 + 1.0 X5
According to Altman's credit scoring model,this firm should be considered
(Multiple Choice)
4.9/5 (82)
(82) One of the weaknesses of estimating expected default rates is that the analysis is based on historic data.
(True/False)
4.8/5 (82)
(82) If the spot interest rate on a prime-rated one-month CD is 6 percent today and the market rate on a two-month maturity prime-rated CD is 7 percent today,the implied forward rate on a one-month CD to be delivered one month from today is
(Multiple Choice)
4.7/5 (77)
(77) Which of the following is NOT a valid conceptual or application problem of the mortality rate approach to estimate default risk?
(Multiple Choice)
4.9/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)