



 Chat with AI
Exam 10: Credit Risk: Individual Loan Risk

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


The following represents two yield curves.
Maturity Pure Discount Treasury Yields B-rated Carparate Band Yields (Pure Discaun Bonds) 1 year 3 percent 6 percent 2 year 6 percent 10 percent 20 year 12 percent 17 percent
-If the cumulative mortality rate in year 3 is 3.46 percent for the B-rated loan,what is its yearly mortality rate in year 3?
(Multiple Choice)
5.0/5  (74)
(74) Which of the following loan applicant characteristics is not relevant in the credit approval decision?
(Multiple Choice)
4.9/5 (62)
(62) The following represents two yield curves.
Maturity Pure Discount Treasury Yields B-rated Carparate Band Yields (Pure Discaun Bonds) 1 year 3 percent 6 percent 2 year 6 percent 10 percent 20 year 12 percent 17 percent
-What is the implied probability of repayment on one-year B-rated debt?
(Multiple Choice)
4.8/5 (78)
(78) The primary difficulty in arranging a syndicated loan is having all of the various lending and borrowing parties reach agreement on terms,rates,and collateral.
(True/False)
4.8/5 (84)
(84) Recessionary phases in the business cycle typically cause greater hardship on companies that borrow large amounts.
(True/False)
4.8/5 (71)
(71) Since their introduction,the proportion of adjustable rate mortgages (ARMs)to fixed-rate residential mortgages has remained very stable over interest rate cycles.
(True/False)
4.8/5 (69)
(69) Simulations conducted by Moody's Analytics have shown that expected default frequency (EDF)models outperform Z-score type models in predicting borrower failure or financial distress.
(True/False)
4.8/5 (70)
(70) Credit risk applies only to bond investment and loan portfolios of depository institutions and other FIs.
(True/False)
4.9/5 (80)
(80) According to Altman's credit scoring model,which of the following Z scores would indicate a low default risk firm?
(Multiple Choice)
4.9/5 (87)
(87) Which of the following factors may affect the promised return an FI receives on a loan?
(Multiple Choice)
4.8/5 (79)
(79) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
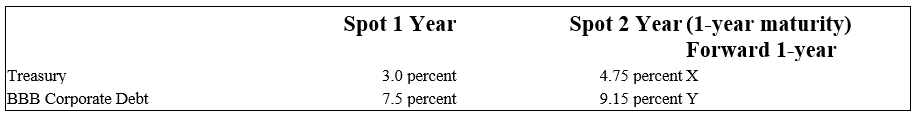 -The duration of a soon to be approved loan of $10 million is four years.The 99th percentile increase in risk premium for bonds belonging to the same risk category of the loan has been estimated to be 5.5 percent. If the minimum RAROC acceptable to the bank is 8 percent,what should be its expected percentage fee income in order for it to approve the loan?
 (Multiple Choice)
5.0/5 (87)
(87) Using a modified discriminant function similar to Altman's,Burger Bank estimates the following coefficients for its portfolio of loans:
Z = 1.4X1 + 1.09X2 + 1.5X3
where X1 = debt to asset ratio;X2 = net income and X3 = dividend payout ratio.
What is the Z-score if the debt to asset ratio is 40 percent,net income is 12 percent,and the dividend payout ratio is 60 percent?
(Multiple Choice)
4.8/5 (81)
(81) Default by a large corporation is seldom a problem for FIs since these corporations have many different sources of borrowed funds.
(True/False)
4.8/5 (67)
(67) Which of the following statements does not reflect a borrower-specific factor often used in qualitative default risk models?
(Multiple Choice)
4.9/5 (77)
(77) From the perspective of an FI,which of the following is an advantage of a floating-rate loan?
(Multiple Choice)
4.7/5 (68)
(68) The exact interest rate to be charged on a fixed-rate loan is agreed upon by all parties at the time the commitment is negotiated.
(True/False)
4.9/5 (81)
(81) The mortality rate measures the past default experience of all loans,regardless of quality.
(True/False)
4.9/5 (85)
(85) The traditional duration equation can be used to measure the capital at risk of a loan.
(True/False)
4.8/5 (65)
(65) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)