



 Chat with AI
Exam 10: Credit Risk: Individual Loan Risk

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


Because of compensating balances and fees used to increase return on a loan,the credit risk premium is not the fundamental factor driving the promised return once the base rate on the loan has been set.
(True/False)
4.8/5  (70)
(70) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
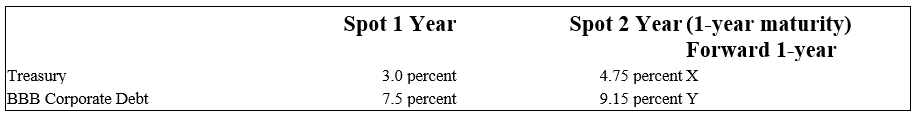 -The cumulative probability of repayment of BBB corporate debt over the next two years is
 (Multiple Choice)
4.8/5 (81)
(81) Commercial paper has become an acceptable substitute source for bank loans for many large corporations.
(True/False)
4.8/5 (82)
(82) Long-term loans are more likely to be made under a loan commitment agreement than short-term loans.
(True/False)
4.9/5 (86)
(86) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
-Calculate the value of y (the implied forward rate on one-year maturity BBB corporate debt to be delivered in one year).
-Calculate the value of y (the implied forward rate on one-year maturity BBB corporate debt to be delivered in one year). (Multiple Choice)
4.9/5 (76)
(76) The probability that a borrower would default in any specific time period is the marginal default probability.
(True/False)
5.0/5 (71)
(71) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
-The duration of a soon to be approved loan of $10 million is four years.The 99th percentile increase in risk premium for bonds belonging to the same risk category of the loan has been estimated to be 5.5 percent. If the fee income on this loan is 0.4 percent and the spread over the cost of funds to the bank is 1 percent,what is the expected income on this loan for the current year?
-The duration of a soon to be approved loan of $10 million is four years.The 99th percentile increase in risk premium for bonds belonging to the same risk category of the loan has been estimated to be 5.5 percent. If the fee income on this loan is 0.4 percent and the spread over the cost of funds to the bank is 1 percent,what is the expected income on this loan for the current year? (Multiple Choice)
4.8/5 (84)
(84) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
-The duration of a soon to be approved loan of $10 million is four years.The 99th percentile increase in risk premium for bonds belonging to the same risk category of the loan has been estimated to be 5.5 percent. What is the capital (loan)risk of the loan if the current average level of interest rates for this category of bonds is 12 percent?
-The duration of a soon to be approved loan of $10 million is four years.The 99th percentile increase in risk premium for bonds belonging to the same risk category of the loan has been estimated to be 5.5 percent. What is the capital (loan)risk of the loan if the current average level of interest rates for this category of bonds is 12 percent? (Multiple Choice)
4.8/5 (67)
(67) Which of the following is NOT characteristic of the consumer loans at U.S.banks?
(Multiple Choice)
4.8/5 (76)
(76) Which of the following observations concerning floating-rate loans is NOT true?
(Multiple Choice)
5.0/5 (93)
(93) At some point,further increases in interest rates on specific loans may decrease expected loan returns because of increased probability of default by the borrower.
(True/False)
4.7/5 (77)
(77) Which of the following is NOT characteristic of the real estate portfolio for most banks?
(Multiple Choice)
4.8/5 (81)
(81) Which of the following is the major weakness of the linear probability model?
(Multiple Choice)
4.9/5 (76)
(76) What is the least important factor determining bankruptcy,according to the Altman Z-score model?
(Multiple Choice)
4.9/5 (85)
(85) A major advantage of discriminant models to assess the credit risk of a customer is the stability of the coefficient weights over time.
(True/False)
4.9/5 (85)
(85) Risk-adjusted return on capital (RAROC)models serve as both a credit risk measure and a pricing tool for a loan officer.
(True/False)
4.9/5 (81)
(81) The following represents two yield curves.
Maturity Pure Discount Treasury Yields B-rated Carparate Band Yields (Pure Discaun Bonds) 1 year 3 percent 6 percent 2 year 6 percent 10 percent 20 year 12 percent 17 percent
-What is the probability that two-year B-rated corporate debt will be fully repaid?
(Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)