



 Chat with AI
Exam 10: Credit Risk: Individual Loan Risk

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


Because a compensating balance is the proportion of a loan that must be kept on deposit at the lending institution,the actual return to the lender on the usable portion of these loans is higher.
(True/False)
4.9/5  (76)
(76) Suppose that the financial ratios of a potential borrowing firm took the following values:
X1 = 0.30
X2 = 0
X3 = -0.30
X4 = 0.15
X5 = 2.1
Altman's discriminant function takes the form:
Z = 1.2 X1+ 1.4 X2 + 3.3 X3 + 0.6 X4 + 1.0 X5
Suppose X3 = 0.2 instead of -0.30.According to Altman's credit scoring model,the firm would fall under which default risk classification?
(Multiple Choice)
4.8/5 (87)
(87) Commercial loans have been decreasing in importance in bank loan portfolios.
(True/False)
4.8/5 (65)
(65) Adjustable rate mortgages have interest rates that adjust periodically according to the movement in some index.
(True/False)
4.8/5 (86)
(86) In making credit decisions,which of the following items is considered a market-specific factor?
(Multiple Choice)
4.9/5 (81)
(81) The following represents two yield curves.
Maturity Pure Discount Treasury Yields B-rated Carparate Band Yields (Pure Discaun Bonds) 1 year 3 percent 6 percent 2 year 6 percent 10 percent 20 year 12 percent 17 percent
-What is the cumulative mortality rate of the A-rated and B-rated loans for year 2?
(Multiple Choice)
4.8/5 (70)
(70) Commercial paper typically is secured by specific assets of the borrower.
(True/False)
4.8/5 (75)
(75) According to option pricing models of credit risk and default,the debt holders of a corporation may have to accept assets which have a value less than the face value of the debt.
(True/False)
4.9/5 (87)
(87) Onyx Corporation has a $200,000 loan that will mature in one year.The risk free interest rate is 6 percent.The standard deviation in the rate of change in the underlying asset's value is 12 percent,and the leverage ratio for Onyx is 0.8 (80 percent).The value for N(h1)is 0.02743,and the value for N(h2)is 0.96406. What is the required yield on this risky loan?
(Multiple Choice)
4.9/5 (84)
(84) All other things equal,longer term loans are more likely to be
(Multiple Choice)
4.9/5 (77)
(77) RAROC (Risk-adjusted return on capital)is a measure of a firm's cost of debt.
(True/False)
4.9/5 (88)
(88) Credit scoring models include all of the following broad types of models EXCEPT
(Multiple Choice)
4.8/5 (79)
(79) In making credit decisions,which of the following items is considered a market-specific factor?
(Multiple Choice)
4.8/5 (84)
(84) A borrower's reputation is an example of a market-specific factor in the credit decision.
(True/False)
4.9/5 (84)
(84) Because they are secured by homes,residential mortgages have demonstrated very little credit risk for FIs.
(True/False)
4.8/5 (67)
(67) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
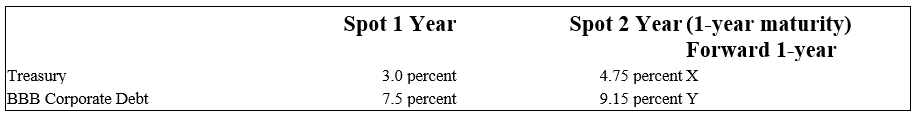 -Using the term structure of default probabilities,the implied default probability for BBB corporate debt during the second year is
 (Multiple Choice)
4.8/5 (64)
(64) Which of the following statements does NOT reflect credit decisions at the retail level?
(Multiple Choice)
4.8/5 (73)
(73) Which of the following completes the statement: All else equal,the higher the duration of a loan,
(Multiple Choice)
4.9/5 (73)
(73) Simulations by Moody's Analytics have shown which of the following models to be relatively better predictors of corporate failure and distress?
(Multiple Choice)
4.8/5 (72)
(72) The following is information on current spot and forward term structures (assume the corporate debt pays interest annually):
-Calculate the value of x (the implied forward rate on one-year maturity Treasuries to be delivered in one year).
-Calculate the value of x (the implied forward rate on one-year maturity Treasuries to be delivered in one year). (Multiple Choice)
4.8/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)