



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


The smaller the leverage-adjusted duration gap,the more exposed the FI is to interest rate shocks.
(True/False)
4.8/5  (74)
(74) What is the price of the bond if market interest rates are 6 percent?
(Multiple Choice)
4.9/5 (83)
(83) One method of changing the positive leverage adjusted duration gap for the purpose of immunizing the net worth of a typical depository institution is to increase the duration of the assets and to decrease the duration of the liabilities.
(True/False)
4.9/5 (76)
(76) Why does immunization against interest rate shocks using duration for fixed-income securities work?
(Multiple Choice)
4.7/5 (72)
(72) Duration increases with the maturity of a fixed-income asset at a decreasing rate.
(True/False)
4.8/5 (72)
(72) For a given maturity fixed-income asset,duration increases as the promised interest payment declines.
(True/False)
4.9/5 (78)
(78) The numbers provided are in millions of dollars and reflect market values: 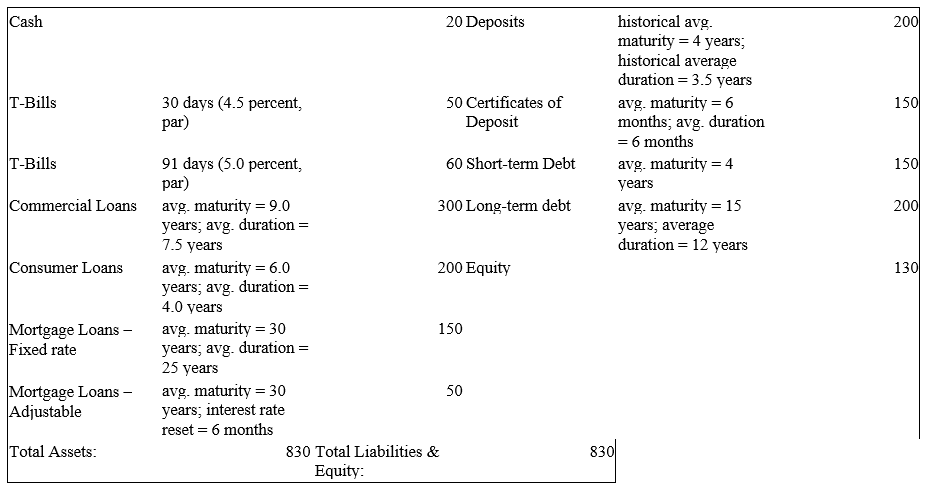 -What is the leverage-adjusted duration gap of the FI?
 (Multiple Choice)
4.7/5 (68)
(68) The greater is convexity,the more insurance a portfolio manager has against interest rate increases and the greater potential gain from rate decreases.
(True/False)
4.7/5 (88)
(88) Matching the maturities of assets and liabilities is not a perfect method of immunizing the balance sheet because the timing of the cash flows is likely to differ between the assets and liabilities.
(True/False)
4.9/5 (91)
(91) A $1,000 six-year Eurobond has an 8 percent coupon,is selling at par,and contracts to make annual payments of interest.The duration of this bond is 4.99 years.What will be the new price using the duration model if interest rates increase to 8.5 percent?
(Multiple Choice)
4.8/5 (67)
(67) A bond is scheduled to mature in five years.Its coupon rate is 9 percent with interest paid annually.This $1,000 par value bond carries a yield to maturity of 10 percent.Calculate the percentage change in this bond's price if interest rates on comparable risk securities decline to 7 percent.Use the duration valuation equation.
(Multiple Choice)
4.9/5 (72)
(72) An FI purchases at par value a $100,000 Treasury bond paying 10 percent interest with a 7.5 year duration.If interest rates rise by 4 percent,calculate the bond's new value. Recall that Treasury bonds pay interest semiannually.Use the duration valuation equation.
(Multiple Choice)
4.8/5 (78)
(78) The numbers provided are in millions of dollars and reflect market values:
-A risk manager could restructure assets and liabilities to reduce interest rate exposure for this example by
-A risk manager could restructure assets and liabilities to reduce interest rate exposure for this example by (Multiple Choice)
4.8/5 (72)
(72) What is the duration of a 5-year par value zero coupon bond yielding 10 percent annually?
(Multiple Choice)
4.9/5 (59)
(59) The numbers provided are in millions of dollars and reflect market values:
-The short-term debt consists of 4-year bonds paying an annual coupon of 4 percent and selling at par.What is the duration of the short-term debt?
-The short-term debt consists of 4-year bonds paying an annual coupon of 4 percent and selling at par.What is the duration of the short-term debt? (Multiple Choice)
4.9/5 (74)
(74) All else equal,as compared to an annual payment fixed income security,a semi-annual payment security has a
(Multiple Choice)
4.9/5 (82)
(82) Duration is related to maturity in a linear manner through the interest rate of the asset.
(True/False)
5.0/5 (77)
(77) What conclusions can you draw from the duration gap in your answer to the previous question?
(Multiple Choice)
4.9/5 (80)
(80) Immunization of a portfolio implies that changes in _____ will not affect the value of the portfolio.
(Multiple Choice)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)