



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


In most countries FIs report their balance sheet using market value accounting.
(True/False)
4.7/5  (82)
(82) A bond is scheduled to mature in five years.Its coupon rate is 9 percent with interest paid annually.This $1,000 par value bond carries a yield to maturity of 10 percent.Calculate the percentage change in this bond's price if interest rates on comparable risk securities increase to 11 percent.Use the duration valuation equation.
(Multiple Choice)
4.9/5 (77)
(77) The duration of a portfolio of assets can be found by calculating the book value weighted average of the durations of the individual assets.
(True/False)
4.8/5 (80)
(80) U.S. Treasury quotes from the WSJ on Oct. 15, 2003:  -If yields increase by 10 basis points,what is the approximate price change on the $100,000 Treasury note? Use the duration approximation relationship.
 (Multiple Choice)
4.9/5 (82)
(82) First Duration Bank has the following assets and liabilities on its balance sheet: 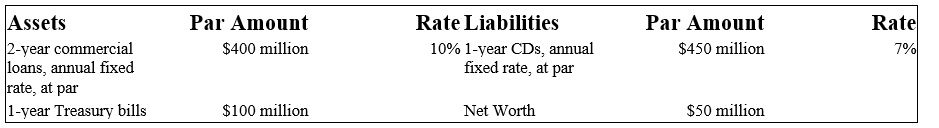 -What is the FI's leverage-adjusted duration gap?
 (Multiple Choice)
4.8/5 (84)
(84) Duration of a fixed-rate coupon bond will always be greater than one-half of the maturity.
(True/False)
4.8/5 (80)
(80) Marking-to-market accounting is a market value accounting method that reflects the purchase prices of assets and liabilities.
(True/False)
4.7/5 (75)
(75) The immunization of a portfolio against interest rate risk means that the portfolio will neither gain nor lose value when interest rates change.
(True/False)
5.0/5 (82)
(82) A bond is scheduled to mature in five years.Its coupon rate is 9 percent with interest paid annually.This $1,000 par value bond carries a yield to maturity of 10 percent.What is the duration of the bond?
(Multiple Choice)
4.8/5 (80)
(80) An FI purchases a $9.982 million pool of commercial loans at par.The loans have an interest rate of 8 percent,a maturity of five years,and annual payments of principal and interest that will exactly amortize the loan at maturity.What is the duration of this asset?
(Multiple Choice)
4.8/5 (86)
(86) Third Duration Investments has the following assets and liabilities on its balance sheet. The two-year Treasury notes are zero coupon assets. Interest payments on all other assets and liabilities occur at maturity. Assume 360 days in a year. 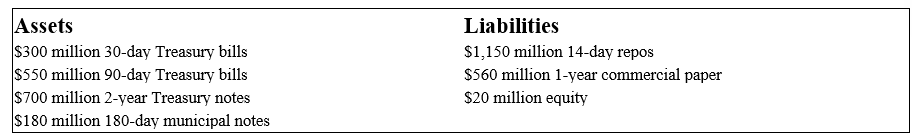 -What is the leverage-adjusted duration gap?
 (Multiple Choice)
4.9/5 (81)
(81) Duration is equal to maturity when at least some of the cash flows are received upon maturity of the asset.
(True/False)
4.7/5 (68)
(68) The following information is about current spot rates for Second Duration Savings' assets (loans) and liabilities (CDs). All interest rates are fixed and paid annually.  -What is the interest rate risk exposure of the optimal transaction in the previous question over the next 2 years?
 (Multiple Choice)
4.8/5 (83)
(83) Third Duration Investments has the following assets and liabilities on its balance sheet. The two-year Treasury notes are zero coupon assets. Interest payments on all other assets and liabilities occur at maturity. Assume 360 days in a year.
-What is the duration of the liabilities?
-What is the duration of the liabilities? (Multiple Choice)
4.7/5 (84)
(84) The numbers provided are in millions of dollars and reflect market values: 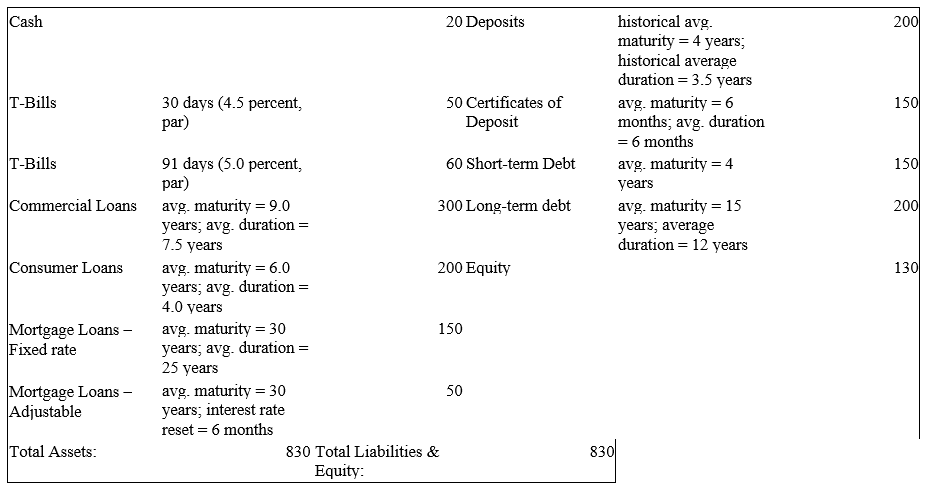 -What is the weighted average duration of the assets of the FI?
 (Multiple Choice)
4.8/5 (70)
(70) The following information is about current spot rates for Second Duration Savings' assets (loans) and liabilities (CDs). All interest rates are fixed and paid annually.
-What is the duration of the two-year loan (per $100 face value)if it is selling at par?
-What is the duration of the two-year loan (per $100 face value)if it is selling at par? (Multiple Choice)
4.8/5 (87)
(87) Immunizing the net worth ratio requires that the duration of the assets be set equal to the duration of the liabilities.
(True/False)
4.8/5 (82)
(82) Third Duration Investments has the following assets and liabilities on its balance sheet. The two-year Treasury notes are zero coupon assets. Interest payments on all other assets and liabilities occur at maturity. Assume 360 days in a year.
-What is the duration of the assets?
-What is the duration of the assets? (Multiple Choice)
4.8/5 (75)
(75) The following information is about current spot rates for Second Duration Savings' assets (loans) and liabilities (CDs). All interest rates are fixed and paid annually.
-Use the duration model to approximate the change in the market value (per $100 face value)of two-year loans if interest rates increase by 100 basis points.
-Use the duration model to approximate the change in the market value (per $100 face value)of two-year loans if interest rates increase by 100 basis points. (Multiple Choice)
5.0/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)