



 Chat with AI
Exam 8: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models159 Questions
Exam 2: Choices and Trade-Offs in the Market192 Questions
Exam 3: Where Prices Come From: The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply224 Questions
Exam 5: Economic Efficiency, Government Price Setting and Taxes187 Questions
Exam 6: Consumer Choice and Behavioural Economics254 Questions
Exam 7: Technology Production and Costs301 Questions
Exam 8: Firms in Perfectly Competitive Markets269 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition: The Competitive Model in a More Realistic255 Questions
Exam 11: Oligopoly: Markets With Few Competitors186 Questions
Exam 12: The Markets for Labour and Other Factors of Production250 Questions
Exam 13: Comparative Advantage and the Gains From International Trade131 Questions
Exam 14: Government Intervention in the Market113 Questions
Exam 15: Externalities, Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy121 Questions
Select questions type


Suppose the equilibrium price in a perfectly competitive industry is $15 and a firm in the industry charges $21.Which of the following will happen?
(Multiple Choice)
4.8/5  (95)
(95) Table 8.4  Table 8.4 shows the short-run cost data of a perfectly competitive firm.Assume that output can only be increased in batches of 20 units.
-Refer to Table 8.4.If the market price is $45, how many units will the firm produce?
Table 8.4 shows the short-run cost data of a perfectly competitive firm.Assume that output can only be increased in batches of 20 units.
-Refer to Table 8.4.If the market price is $45, how many units will the firm produce? (Multiple Choice)
4.9/5 (66)
(66) Which of the following is a characteristic of a firm in a perfectly competitive market?
(Multiple Choice)
4.9/5 (78)
(78) Figure 8.2  -Refer to Figure 8.2.Why is the total revenue curve a ray from the origin?
 (Multiple Choice)
4.9/5 (67)
(67) The market demand curve for a perfectly competitive industry is the horizontal summation of each individual firm's demand curve.
(True/False)
4.9/5 (81)
(81) An increase in a firm's fixed cost will not change the firm's profit-maximising output in the short run.
(True/False)
4.8/5 (85)
(85) Jason, a high-school student, mows lawns for families in his neighbourhood.The going rate is $12 for each lawn-mowing service.Jason would like to charge $20 because he believes he has more experience mowing lawns than the many other teenagers who also offer the same service.If the market for lawn mowing services were perfectly competitive, what would happen if Jason raised his price?
(Multiple Choice)
4.8/5 (80)
(80) If, for the last bushel of apples produced and sold by an apple farm, marginal revenue exceeds marginal cost, then in producing that bushel the farm
(Multiple Choice)
4.9/5 (81)
(81) Figure 8.5  Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.If the market price is $20, the firm's profit-maximising output is
Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.If the market price is $20, the firm's profit-maximising output is (Multiple Choice)
4.9/5 (84)
(84) If, in a perfectly competitive industry, the market price facing a firm is above its average total cost at the output where marginal revenue equals marginal cost, then
(Multiple Choice)
4.8/5 (78)
(78) In the short run, a profit-maximising firm will shut down if its total revenue is greater than its variable costs.
(True/False)
4.8/5 (88)
(88) If a firm's total variable cost exceeds its total revenue, the firm should stop production by shutting down temporarily.
(True/False)
4.8/5 (80)
(80) A perfectly competitive firm's marginal revenue curve is downward sloping.
(True/False)
4.8/5 (83)
(83) Which of the following offers the best reason why restaurants are not considered to be perfectly competitive firms?
(Multiple Choice)
4.9/5 (62)
(62) Figure 8.14  -Refer to Figure 8.14.Which panel best represents the perfectly competitive organic produce market's transition to the long run when some firms in the market are earning economic profits?
 (Multiple Choice)
5.0/5 (64)
(64) Table 8.4 Table 8.4 shows the short-run cost data of a perfectly competitive firm.Assume that output can only be increased in batches of 20 units.
-Refer to Table 8.4.If the market price is $45, the firm
Table 8.4 shows the short-run cost data of a perfectly competitive firm.Assume that output can only be increased in batches of 20 units.
-Refer to Table 8.4.If the market price is $45, the firm (Multiple Choice)
4.9/5 (87)
(87) Figure 8.12 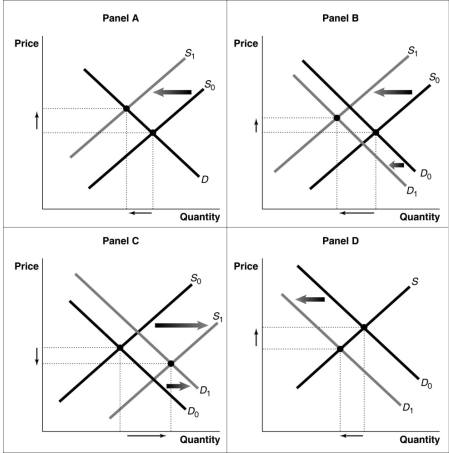 -Refer to Figure 8.12.Consider a typical firm in a perfectly competitive industry which is incurring short-run losses.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (77)
(77) When firms exit a perfectly competitive industry, the market supply curve shifts to the left.
(True/False)
4.7/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)