



 Chat with AI
Exam 8: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models159 Questions
Exam 2: Choices and Trade-Offs in the Market192 Questions
Exam 3: Where Prices Come From: The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply224 Questions
Exam 5: Economic Efficiency, Government Price Setting and Taxes187 Questions
Exam 6: Consumer Choice and Behavioural Economics254 Questions
Exam 7: Technology Production and Costs301 Questions
Exam 8: Firms in Perfectly Competitive Markets269 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition: The Competitive Model in a More Realistic255 Questions
Exam 11: Oligopoly: Markets With Few Competitors186 Questions
Exam 12: The Markets for Labour and Other Factors of Production250 Questions
Exam 13: Comparative Advantage and the Gains From International Trade131 Questions
Exam 14: Government Intervention in the Market113 Questions
Exam 15: Externalities, Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy121 Questions
Select questions type


In the short run, a firm might choose to produce rather than shut down even if its market price is less than its average total cost of production.
(True/False)
4.8/5  (68)
(68) When plasma television sets were first introduced, prices were high and few firms were in the market.Later, economic profits attracted new firms, and the price of plasma televisions fell.This example illustrates
(Multiple Choice)
4.9/5 (96)
(96) The long-run supply curve for a perfectly competitive, constant-cost industry
(Multiple Choice)
4.8/5 (72)
(72) Being a price-taker, a perfectly competitive firm cannot receive a producer surplus in the short run.
(True/False)
4.9/5 (64)
(64) In long-run perfectly competitive equilibrium, which of the following is false?
(Multiple Choice)
4.8/5 (77)
(77) Figure 8.5  Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.The firm's manager suggests that the firm's goal should be to maximise average profit. If the firm does this, the amount of profit that it will earn is
Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.The firm's manager suggests that the firm's goal should be to maximise average profit. If the firm does this, the amount of profit that it will earn is (Multiple Choice)
4.9/5 (89)
(89) For a perfectly competitive firm, to what is average revenue equal?
(Multiple Choice)
4.8/5 (77)
(77) For a perfectly competitive firm, which of the following is not true at profit maximisation?
(Multiple Choice)
4.8/5 (64)
(64) A perfectly competitive firm in a constant-cost industry produces 3000 units of a good at a total cost of $36 000.The prevailing market price is $15.What will happen to the number of firms in the industry and to the industry's output in the long run?
(Multiple Choice)
4.8/5 (94)
(94) Figure 8.10 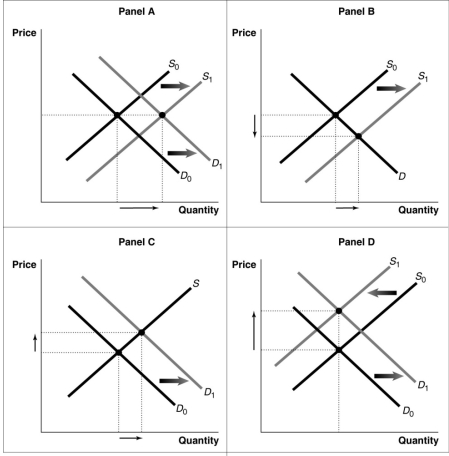 -Refer to Figure 8.10.Consider a typical firm in a perfectly competitive industry that makes short-run profits.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (77)
(77) Figure 8.7  Figure 8.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 8.7.At price P3, the firm would produce
Figure 8.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 8.7.At price P3, the firm would produce (Multiple Choice)
4.9/5 (83)
(83) Figure 8.4  Figure 8.4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 8.4.If the market price is $30, what is the firm's profit-maximising output level?
Figure 8.4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 8.4.If the market price is $30, what is the firm's profit-maximising output level? (Multiple Choice)
4.8/5 (70)
(70) Figure 8.4 Figure 8.4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 8.4.If the market price is $30 and the firm is producing output, the amount of the firm's profit or loss is
Figure 8.4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 8.4.If the market price is $30 and the firm is producing output, the amount of the firm's profit or loss is (Multiple Choice)
4.7/5 (66)
(66) Which of the following is not true for a firm in perfect competition?
(Multiple Choice)
4.7/5 (78)
(78) The price a perfectly competitive firm receives for its output
(Multiple Choice)
5.0/5 (81)
(81) Under what conditions should a competitive firm shut down in the short run?
__________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
4.7/5 (97)
(97) Figure 8.8  -Refer to Figure 8.8.What is total cost at the profit-maximising output level?
 (Multiple Choice)
4.8/5 (73)
(73) The short-run supply curve for a perfectly competitive firm is that part of the firm's marginal cost curve that lies above the minimum point of its average variable cost curve.
(True/False)
5.0/5 (91)
(91) Figure 8.5 Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.If the firm's fixed cost increases by $1000 due to a new environmental regulation, what happens in the diagram above?
Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.If the firm's fixed cost increases by $1000 due to a new environmental regulation, what happens in the diagram above? (Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)