



 Chat with AI
Exam 8: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models159 Questions
Exam 2: Choices and Trade-Offs in the Market192 Questions
Exam 3: Where Prices Come From: The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply224 Questions
Exam 5: Economic Efficiency, Government Price Setting and Taxes187 Questions
Exam 6: Consumer Choice and Behavioural Economics254 Questions
Exam 7: Technology Production and Costs301 Questions
Exam 8: Firms in Perfectly Competitive Markets269 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition: The Competitive Model in a More Realistic255 Questions
Exam 11: Oligopoly: Markets With Few Competitors186 Questions
Exam 12: The Markets for Labour and Other Factors of Production250 Questions
Exam 13: Comparative Advantage and the Gains From International Trade131 Questions
Exam 14: Government Intervention in the Market113 Questions
Exam 15: Externalities, Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy121 Questions
Select questions type


At the profit-maximising level of output for a perfectly competitive firm,
(Multiple Choice)
4.8/5  (90)
(90) In a graph that illustrates a perfectly competitive firm, marginal revenue is
(Multiple Choice)
4.8/5 (80)
(80) Figure 8.15 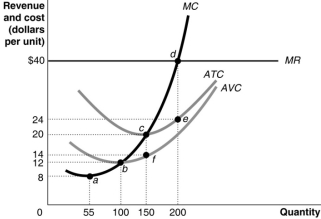 -Use the figure above to answer the following questions.
a.How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b.What is the market price?
c.What is the profit-maximising output?
d.What is total revenue at the profit-maximising output?
e.What is the total cost at the profit-maximising output?
f.What is the profit or loss at the profit-maximising output?
g.What is the firm's total fixed cost?
h.What is the total variable cost?
i.Identify the firm's short-run supply curve.
j.Is the industry in a long-run equilibrium?
k.If it is not in long-run equilibrium, what will happen in this industry to restore long-run equilibrium?
l.In long-run equilibrium, what is the firm's profit maximising quantity?
__________________________________________________________________________________________________________________________________________________________________________________________
-Use the figure above to answer the following questions.
a.How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b.What is the market price?
c.What is the profit-maximising output?
d.What is total revenue at the profit-maximising output?
e.What is the total cost at the profit-maximising output?
f.What is the profit or loss at the profit-maximising output?
g.What is the firm's total fixed cost?
h.What is the total variable cost?
i.Identify the firm's short-run supply curve.
j.Is the industry in a long-run equilibrium?
k.If it is not in long-run equilibrium, what will happen in this industry to restore long-run equilibrium?
l.In long-run equilibrium, what is the firm's profit maximising quantity?
__________________________________________________________________________________________________________________________________________________________________________________________ (Essay)
4.8/5 (76)
(76) Suppose Veronica sells teapots in the perfectly competitive teapot market.Her output per day and her costs are as follows: 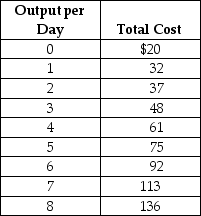 Suppose the current equilibrium price in the teapot market is $15.To maximise profit, how many teapots will Veronica produce, what price will she charge, and how much profit (or loss)will she make? Draw a graph to illustrate your answer.Your graph should include Veronica's demand, ATC, AVC, MC, and MR curves, the price she is charging, the quantity she is producing, and the area representing her profit (or loss).
__________________________________________________________________________________________________________________________________________________________________________________________
Suppose the current equilibrium price in the teapot market is $15.To maximise profit, how many teapots will Veronica produce, what price will she charge, and how much profit (or loss)will she make? Draw a graph to illustrate your answer.Your graph should include Veronica's demand, ATC, AVC, MC, and MR curves, the price she is charging, the quantity she is producing, and the area representing her profit (or loss).
__________________________________________________________________________________________________________________________________________________________________________________________ (Essay)
4.8/5 (73)
(73) Which of the following is not an assumption of perfectly competitive markets?
(Multiple Choice)
4.8/5 (86)
(86) In August 2008, Ethan Nicholas developed the iShoot application for the apple iPhone 3G, and within five months had earned $800 000 from this program.By May 2009, Nicholas had dropped the price from $4.99 to $1.99 in an attempt to maintain sales.This example indicates that in a competitive market,
(Multiple Choice)
4.8/5 (89)
(89) Firms in perfectly competitive industries are unable to control the prices of the products they sell and earn a profit in the long run because
(Multiple Choice)
4.9/5 (85)
(85) If firms do not earn economic profits in a competitive equilibrium, why would the firms choose to stay in business?
__________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
4.9/5 (81)
(81) Figure 8.5  Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.If the market price is $20, the amount of the firm's profit is
Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.If the market price is $20, the amount of the firm's profit is (Multiple Choice)
5.0/5 (63)
(63) Figure 8.2  -Refer to Figure 8.2.What happens if the firm produces more than Q4 units?
 (Multiple Choice)
4.9/5 (69)
(69) If in the long run a firm makes zero profit, it should exit the industry.
(True/False)
4.8/5 (85)
(85) Apple introduced its iPhone 3G in July 2008, and within a month sales had topped 3 million units.By April 2009, more than 25 000 apps for the iPhone 3G were available in the iTunes store, an indication that in a competitive market,
(Multiple Choice)
4.8/5 (82)
(82) In a decreasing-cost industry, the entry of new firms lowers average cost at each level of output.
(True/False)
4.8/5 (83)
(83) In the short run, if a firm shuts down its maximum loss equals the amount of its fixed cost.
(True/False)
4.8/5 (87)
(87) Figure 8.11 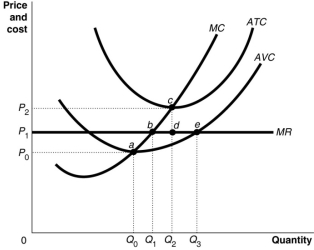 -Refer to Figure 8.11.Suppose the prevailing price is P1 and the firm is currently producing its loss-minimising quantity.In the long-run equilibrium
 (Multiple Choice)
4.7/5 (69)
(69) Table 8.1  Table 8.1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 8.1.If the market price of each camera case is $8 and the firm maximises profit, what is the amount of the firm's profit or loss?
Table 8.1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 8.1.If the market price of each camera case is $8 and the firm maximises profit, what is the amount of the firm's profit or loss? (Multiple Choice)
4.9/5 (92)
(92) Figure 8.7  Figure 8.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 8.7.At price P4, the firm would
Figure 8.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 8.7.At price P4, the firm would (Multiple Choice)
4.8/5 (83)
(83) Figure 8.13  -Refer to Figure 8.13.Assume that the medical screening industry is perfectly competitive and that some firms are incurring short-run losses.Suppose the medical screening industry runs an effective advertising campaign which convinces a large number of people that yearly CT scans are critical for good health.Which of the diagrams in the figure best describes what happens in the industry?
 (Multiple Choice)
5.0/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)