



 Chat with AI
Exam 8: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models159 Questions
Exam 2: Choices and Trade-Offs in the Market192 Questions
Exam 3: Where Prices Come From: The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply224 Questions
Exam 5: Economic Efficiency, Government Price Setting and Taxes187 Questions
Exam 6: Consumer Choice and Behavioural Economics254 Questions
Exam 7: Technology Production and Costs301 Questions
Exam 8: Firms in Perfectly Competitive Markets269 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition: The Competitive Model in a More Realistic255 Questions
Exam 11: Oligopoly: Markets With Few Competitors186 Questions
Exam 12: The Markets for Labour and Other Factors of Production250 Questions
Exam 13: Comparative Advantage and the Gains From International Trade131 Questions
Exam 14: Government Intervention in the Market113 Questions
Exam 15: Externalities, Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy121 Questions
Select questions type


Figure 8.2  -Refer to Figure 8.2.Suppose the firm is currently producing Q2 units.What happens if it expands output to Q3 units?
Free
(Multiple Choice)
4.8/5  (81)
(81) Correct Answer: Verified
B
Firms in perfect competition are price takers because
Free
(Multiple Choice)
4.7/5 (91)
(91) Correct Answer:Verified
VerifiedD
Figure 8.7  Figure 8.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 8.7.At price P2, the firm would
Figure 8.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 8.7.At price P2, the firm wouldFree
(Multiple Choice)
4.9/5 (85)
(85) Correct Answer:Verified
VerifiedC
A perfectly competitive firm produces 3000 units of a good at a total cost of $36 000.The price of each good is $10.What is the firm's short-run profit or loss?
(Multiple Choice)
4.9/5 (75)
(75) If a typical firm in a perfectly competitive industry is earning profits, then
(Multiple Choice)
4.8/5 (91)
(91) An individual seller in perfect competition will not sell at a price lower than the market price because
(Multiple Choice)
4.9/5 (67)
(67) Which of the following is not a characteristic of a perfect competition?
(Multiple Choice)
4.7/5 (72)
(72) What is meant by allocative efficiency? How does a perfectly competitive firm achieve allocative efficiency?
__________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
4.9/5 (75)
(75) Table 8.5 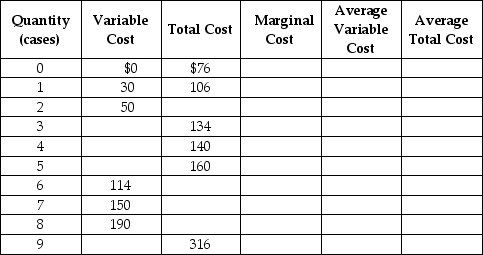 Use the table to answer the following questions.
a.Complete Table 8.5 by filling in the blank cells.
b.Werner is selling in a perfectly competitive market at a price of $40.What is the profit maximising or loss-minimising output?
c.Calculate the firm's profit or loss.
d.Should the firm continue to produce in the short run? Explain.
e.If the firm's fixed costs were $30 higher, what would be the profit-maximising output level in the short run? Indicate whether the output level will increase, decrease or remain unchanged compared to your answer in b.
f.Suppose fixed cost remains at $76.If the price of three-ring binders falls to $20 what is the profit-maximising or loss-minimising output?
g.Calculate the profit or loss.Should the firm continue to produce in the short run? Explain your answer.
h. Suppose the fixed cost remains at $76.What price corresponds to the shut-down point?
i.Suppose the fixed cost remains at $76.What price corresponds to the break-even point?
__________________________________________________________________________________________________________________________________________________________________________________________
-Werner & Sons is a manufacturer of three-ring binders operating in a perfectly competitive industry.Table 8.5 shows the firm's cost schedule.
Use the table to answer the following questions.
a.Complete Table 8.5 by filling in the blank cells.
b.Werner is selling in a perfectly competitive market at a price of $40.What is the profit maximising or loss-minimising output?
c.Calculate the firm's profit or loss.
d.Should the firm continue to produce in the short run? Explain.
e.If the firm's fixed costs were $30 higher, what would be the profit-maximising output level in the short run? Indicate whether the output level will increase, decrease or remain unchanged compared to your answer in b.
f.Suppose fixed cost remains at $76.If the price of three-ring binders falls to $20 what is the profit-maximising or loss-minimising output?
g.Calculate the profit or loss.Should the firm continue to produce in the short run? Explain your answer.
h. Suppose the fixed cost remains at $76.What price corresponds to the shut-down point?
i.Suppose the fixed cost remains at $76.What price corresponds to the break-even point?
__________________________________________________________________________________________________________________________________________________________________________________________
-Werner & Sons is a manufacturer of three-ring binders operating in a perfectly competitive industry.Table 8.5 shows the firm's cost schedule. (Essay)
4.8/5 (75)
(75) Suppose the equilibrium price in a perfectly competitive industry is $10 and a firm in the industry charges $12.Which of the following will happen?
(Multiple Choice)
4.8/5 (91)
(91) In an increasing-cost industry, the long-run supply curve is upward sloping.
(True/False)
4.8/5 (86)
(86) Figure 8.5  Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.The amount of the firm's fixed cost of production is
Figure 8.5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 8.5.The amount of the firm's fixed cost of production is (Multiple Choice)
4.8/5 (73)
(73) When a perfectly competitive firm finds that its market price is below its minimum average variable cost, it will sell
(Multiple Choice)
4.9/5 (83)
(83) A perfectly competitive wheat farmer in a constant-cost industry produces 1000 bushels of wheat at a total cost of $50 000.The prevailing market price is $48.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.8/5 (71)
(71) Which of the following is not an option for a perfectly competitive firm that suffers short-run losses?
(Multiple Choice)
5.0/5 (81)
(81) Figure 8.14  -Refer to Figure 8.14.Which panel best represents the perfectly competitive organic produce market in which some firms are earning short-run economic profits, and the Surgeon General announces that switching from nonorganic produce to organic produce will add 5 years to the average life span of consumers?
 (Multiple Choice)
4.8/5 (85)
(85) Figure 8.8  -Refer to Figure 8.8.What does the firm earn at the profit-maximising output level?
 (Multiple Choice)
4.7/5 (81)
(81) If a firm's fixed cost exceeds its total revenue, the firm should stop production by shutting down temporarily.
(True/False)
5.0/5 (71)
(71) A perfectly competitive firm in long-run equilibrium produces output at the lowest possible average total cost.
(True/False)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)