



 Chat with AI
Exam 21: Firm Supply

Exam 1: Budget Constraint58 Questions
Exam 1: A: Budget Constraint30 Questions
Exam 2: Preferences49 Questions
Exam 2: A: Preferences30 Questions
Exam 3: Utility57 Questions
Exam 3: A: Utility29 Questions
Exam 4: Choice63 Questions
Exam 4: A: Choice31 Questions
Exam 5: Demand79 Questions
Exam 5: A: Demand22 Questions
Exam 6: Revealed Preference58 Questions
Exam 6: A: Revealed Preference26 Questions
Exam 7: Slutsky Equation51 Questions
Exam 7: A: Slutsky Equation30 Questions
Exam 8: Buying and Selling75 Questions
Exam 8: A: Buying and Selling30 Questions
Exam 9: Intertemporal Choice61 Questions
Exam 9: A: Intertemporal Choice30 Questions
Exam 10: Asset Markets46 Questions
Exam 10: A: Asset Markets30 Questions
Exam 11: Uncertainty39 Questions
Exam 11: A: Uncertainty25 Questions
Exam 12: Risky Assets16 Questions
Exam 12: A: Risky Assets10 Questions
Exam 13: Consumers Surplus42 Questions
Exam 13: A: Consumers Surplus30 Questions
Exam 14: Market Demand101 Questions
Exam 14: A: Market Demand25 Questions
Exam 15: Equilibrium48 Questions
Exam 15: A: Equilibrium20 Questions
Exam 16: Auctions36 Questions
Exam 16: A: Auctions25 Questions
Exam 17: Technology52 Questions
Exam 17: A: Technology30 Questions
Exam 18: Profit Maximization52 Questions
Exam 18: A: Profit Maximization21 Questions
Exam 19: Cost Minimization77 Questions
Exam 19: A: Cost Minimization26 Questions
Exam 20: Cost Curves51 Questions
Exam 20: A: Cost Curves20 Questions
Exam 21: Firm Supply41 Questions
Exam 21: A: Firm Supply15 Questions
Exam 22: Industry Supply49 Questions
Exam 22: A: Industry Supply33 Questions
Exam 23: Monopoly76 Questions
Exam 23: A: Monopoly30 Questions
Exam 24: Monopoly Behavior34 Questions
Exam 24: A: Monopoly Behavior20 Questions
Exam 25: Factor Markets24 Questions
Exam 25: A: Factor Markets20 Questions
Exam 26: Oligopoly56 Questions
Exam 26: A: Oligopoly30 Questions
Exam 27: Game Theory34 Questions
Exam 27: A: Game Theory25 Questions
Exam 28: Game Applications28 Questions
Exam 28: A: Game Applications25 Questions
Exam 29: Behavioral Economics34 Questions
Exam 30: Exchange68 Questions
Exam 30: A: Exchange30 Questions
Exam 31: Production35 Questions
Exam 31: A: Production25 Questions
Exam 32: Welfare27 Questions
Exam 32: A: Welfare25 Questions
Exam 33: Externalities42 Questions
Exam 33: A: Externalities25 Questions
Exam 34: Information Technology24 Questions
Exam 34: A: Information Technology15 Questions
Exam 35: Public Goods26 Questions
Exam 35: A: Public Goods20 Questions
Exam 36: Asymmetric Information31 Questions
Exam 36: A: Asymmetric Information20 Questions
Select questions type


A profit-maximizing dairy farm is currently producing 10,000 gallons of milk per day. The government is considering two alternative policies. One is to give the farm a lump sum subsidy of $500 per month. The other policy is to give the farm a subsidy of $.05 per gallon of output.

Free
(Multiple Choice)
4.8/5  (72)
(72) Correct Answer: Verified
C
The change in producer's surplus when the market price changes from p1 to p2 is half of the area to the left of the marginal cost curve between p1 and p2.
Free
(True/False)
5.0/5 (90)
(90) Correct Answer:Verified
VerifiedFalse
A firm faces competitive markets both for its inputs and its outputs. If its long-run supply curve is q = 3p,then it cannot have constant returns to scale.
Free
(True/False)
4.8/5 (90)
(90) Correct Answer:Verified
VerifiedTrue
Suppose that Dent Carr's long-run total cost of repairing s cars per week is c(s) = 3s2 + 108. If the price he receives for repairing a car is $18, then in the long run, how many cars will he fix per week if he maximizes profits?
(Multiple Choice)
4.8/5 (72)
(72) Irma's production function is f(x1, x2) = 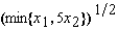 . If the price of factor 1 is w1 = $5 and the price of factor 2 is w2 = $20, then her supply function is given by the equation
 (Multiple Choice)
4.7/5 (81)
(81) A firm produces one output, using one input, with the production function  , where x is the amount of input. The cost function for this firm is proportional to the price of the input times the cube of the amount of output.
 (True/False)
4.9/5 (91)
(91) Suppose that Dent Carr's long-run total cost of repairing s cars per week is c(s) = 3s2 + 12. If the price he receives for repairing a car is $24, then in the long run, how many cars will he fix per week if he maximizes profits?
(Multiple Choice)
4.7/5 (77)
(77) Irma's production function is f(x1, x2) = 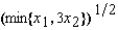 . If the price of factor 1 is w1 = $3 and the price of factor 2 is w2 = $9, then her supply function is given by the equation
 (Multiple Choice)
4.9/5 (79)
(79) A competitive, capitalistic firm produces gift-wrapped pieces of the Berlin wall, using the standard Marxian inputs, K and L. The production function is  , where y is the number of pieces produced.Neglect the use of the wall itself. The price of capital, K, is r, and the price of labor, L, is w
 (Multiple Choice)
4.9/5 (89)
(89) A firm's production function is f(x1, x2) = 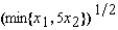 . If the price of factor 1 is w1 = $5 per unit and the price of factor 2 is w2 = $25 per unit, then its supply function is given by the equation S(p) =
 (Multiple Choice)
4.8/5 (67)
(67) A competitive firm produces its output according to the production function y = min{x2, 100}. Let w be the price of the factor x, and let the price of output be $1.The demand for x, when the price of x is w, is
(Multiple Choice)
4.9/5 (83)
(83) A firm has the long-run cost function C(q) = 7q2 + 175.In the long run, it will supply a positive amount of output, so long as the price is greater than
(Multiple Choice)
4.8/5 (58)
(58) A firm has the long-run cost function C(q) = 6q2 + 486.In the long run, it will supply a positive amount of output, so long as the price is greater than
(Multiple Choice)
5.0/5 (76)
(76) A firm has the long-run cost function C(q) = 3q2 + 27.In the long run, it will supply a positive amount of output, so long as the price is greater than
(Multiple Choice)
4.9/5 (64)
(64) Price equals marginal cost is a sufficient condition for profit maximization.
(True/False)
4.8/5 (99)
(99) A competitive firm has a long-run total cost function c(y) = 3y2 + 675 for y > 0 and c(0) = 0. Its long-run supply function is described as
(Multiple Choice)
4.8/5 (82)
(82) A firm in a competitive industry takes account of the fact that the demand curve it confronts has a significant negative slope.
(True/False)
4.9/5 (97)
(97) Two firms have the same technology and must pay the same wages for labor. They have identical factories, but firm 1 paid a higher price for its factory than firm 2 did. If they are both profit maximizers and have upward-sloping marginal cost curves, then we would expect firm 1 to have a higher output than firm 2.
(True/False)
4.8/5 (79)
(79) Mr. O. Carr has the cost function c(y) = y2 + 100 if his output, y, is positive and c(0) = 0. If the price of output is 25, Mr. Carr's profit-maximizing output is zero.
(True/False)
4.9/5 (64)
(64) Marge Costa produces plastic dog dishes using a process that requires only labor and plastic as inputs and has constant returns to scale. With the process she is currently using, a laborer can turn out 30 dog dishes an hour. The wage rate is $9 per hour. The plastic in a dog dish costs Marge $.10. She has no other costs besides labor and plastic. Marge faces a perfectly competitive market for plastic dog dishes, and she decides that she is maximizing profits when she makes 300 dog dishes an hour. What is the market price of dog dishes?
(Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)