



 Chat with AI
Exam 12: Monopoly

Exam 1: What Is Economics254 Questions
Exam 2: The Economony: Myth and Reality184 Questions
Exam 3: The Fundamental Economic Problem: Scarcity and Choice278 Questions
Exam 4: Supply and Demand: an Initial Look297 Questions
Exam 5: Consumer Choice: Individual and Market Demand213 Questions
Exam 6: Demand and Elasticity247 Questions
Exam 7: Production, Inputs, and Cost: Building Blocks for Supply Analysis246 Questions
Exam 8: Output, Price, and Profit: the Importance of Marginal Analysis232 Questions
Exam 9: The Financial Markets and the Economy: the Tail That Wags the Dog225 Questions
Exam 10: The Firm and the Industry Under Perfect Competition219 Questions
Exam 11: The Case for Free Markets: the Price System251 Questions
Exam 12: Monopoly236 Questions
Exam 13: Between Competition and Monopoly248 Questions
Exam 14: Limiting Market Power: Antitrust and Regulation152 Questions
Exam 15: The Shortcomings of Free Markets210 Questions
Exam 16: The Economics of the Environment, and Natural Resources218 Questions
Exam 17: Taxation and Resource Allocation218 Questions
Exam 18: Pricing the Factors of Production230 Questions
Exam 19: Labor and Entrepreneurship: the Human Inputs267 Questions
Exam 20: Poverty, Inequality, and Discrimination167 Questions
Exam 21: An Introduction to Macroeconomics212 Questions
Exam 22: The Goals of Macroeconomic Policy212 Questions
Exam 23: Economic Growth: Theory and Policy226 Questions
Exam 24: Aggregate Demand and the Powerful Consumer216 Questions
Exam 25: Demand-Side Equilibrium: Unemployment or Inflation215 Questions
Exam 26: Bringing in the Supply Side: Unemployment and Inflation228 Questions
Exam 27: Managing Aggregate Demand: Fiscal Policy207 Questions
Exam 28: Money and the Banking System222 Questions
Exam 29: Monetary Policy: Conventional and Unconventional208 Questions
Exam 30: The Financial Crisis and the Great Recession64 Questions
Exam 31: The Debate Over Monetary and Fiscal Policy216 Questions
Exam 32: Budget Deficits in the Short and Long Run214 Questions
Exam 33: The Trade-Off Between Inflation and Unemployment218 Questions
Exam 34: International Trade and Comparative Advantage215 Questions
Exam 35: The International Monetary System: Order or Disorder216 Questions
Exam 36: Exchange Rates and the Macroeconomy215 Questions
Exam 37: Contemporary Issues in the Useconomy23 Questions
Select questions type


If a firm was able to acquire control over access to bauxite, the ore used in aluminum manufacturing, it would gain monopoly control of the aluminum industry because that firm
(Multiple Choice)
4.8/5  (69)
(69) Public utilities, due to their economies of scale, are permitted by government to charge whatever price that they wish.
(True/False)
4.9/5 (79)
(79) Bargain airline fares in which airlines charge varying rates to passengers for the same flight and service is an example of
(Multiple Choice)
4.7/5 (86)
(86) Figure 11-9 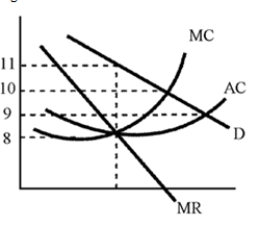 -In assessing the difference between monopoly performance and that of perfect competition, the best approach is to
 (Multiple Choice)
5.0/5 (67)
(67) The key element in preserving a monopoly is keeping rivals out of the market.
(True/False)
4.8/5 (71)
(71) ____ mean that the costs involved cannot be recouped for a considerable period of time.
(Multiple Choice)
5.0/5 (88)
(88) Figure 11-7 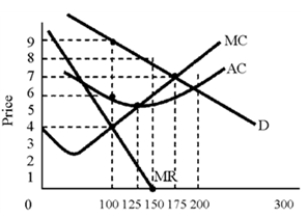 -The firm shown in Figure 11-7 is an unregulated monopolist; it totals equals _____ .
 (Multiple Choice)
4.9/5 (94)
(94) Pure monopoly is able to exist because the firm's product is better than the substitutes that are available in the market.
(True/False)
4.9/5 (75)
(75) Figure 11-5 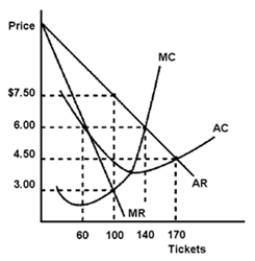 -In Figure 11-5, Crown Theater, a monopolist movie theater, has chosen the profit-maximizing output.At this output level, what is total cost for the firm?
 (Multiple Choice)
4.8/5 (76)
(76) A monopolist's profit per unit is shown by the difference between price and average cost per unit.
(True/False)
4.9/5 (79)
(79) The difference in prices for first-class and coach airline tickets exemplifies price discrimination.
(True/False)
4.8/5 (85)
(85) One of the conclusions of the model of monopoly is that the firm earns economic profits above the required opportunity cost of the factors of production.Are these profits lost to society? Do they take spending power from the economy, and act as a brake on economic growth?
(Essay)
4.7/5 (76)
(76) Figure 11-4 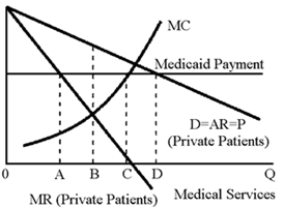 -Physicians have two types of patients: private patients who pay directly or with insurance, and Medicaid patients whose care is paid for by the state.Physicians must lower prices to attract more private patients, but they can add unlimited Medicaid patients at a constant price.The situation facing Dr.Casey is depicted in Figure 11-4.Units of medical service (say, number of patients × number of visits) are measured on the horizontal axis.How many units of medical service will Dr.Casey deliver?
 (Multiple Choice)
4.8/5 (82)
(82) In the long run, profit-maximizing monopolists facing a downward-sloping demand curve
(Multiple Choice)
4.8/5 (69)
(69) There exist only two causes of monopoly: barriers to entry and government restrictions.
(True/False)
4.8/5 (77)
(77) Figure 11-2 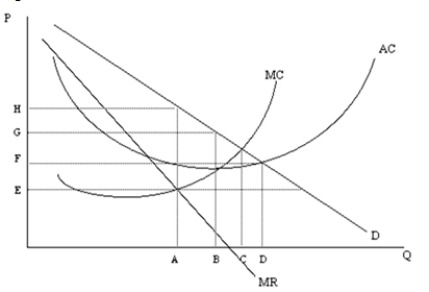 -For the monopolist show in Figure 11-2, how much profit is the monopolist making per unit?
 (Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)