



 Chat with AI
Exam 4: Process Costing and Hybrid Product-Costing Systems

Exam 1: The Changing Role of Managerial Accounting in a Dynamic Business Environment85 Questions
Exam 2: Basic Cost Management Concepts115 Questions
Exam 3: Product Costing and Cost Accumulation in a Batch Production Environment95 Questions
Exam 4: Process Costing and Hybrid Product-Costing Systems88 Questions
Exam 5: Activity-Based Costing and Management103 Questions
Exam 6: Activity Analysis, Cost Behavior, and Cost Estimation90 Questions
Exam 7: Cost-Volume-Profit Analysis109 Questions
Exam 8: Variable Costing and the Costs of Quality and Sustainability74 Questions
Exam 9: Financial Planning and Analysis: the Master Budget112 Questions
Exam 10: Standard Costing and Analysis of Direct Costs97 Questions
Exam 11: Flexible Budgeting and Analysis of Overhead Costs89 Questions
Exam 12: Responsibility Accounting, Operational Performance Measures, and the Balanced Scorecard89 Questions
Exam 13: Investment Centers and Transfer Pricing101 Questions
Exam 14: Decision Making: Relevant Costs and Benefits96 Questions
Exam 15: Target Costing and Cost Analysis for Pricing Decisions107 Questions
Exam 16: Capital Expenditure Decisions120 Questions
Exam 17: Allocation of Support Activity Costs and Joint Costs81 Questions
Exam 18: The Sarbanes-Oxley Act, Internal Controls, and Management Accounting20 Questions
Exam 19: Compound Interest and the Concept of Present Value27 Questions
Exam 20: Inventory Management20 Questions
Select questions type


The flow of costs through the manufacturing accounts is essentially the same in both process costing and job-order costing.
(True/False)
5.0/5  (80)
(80) Operation costing might be used to determine the cost of all of the following products except:
(Multiple Choice)
4.9/5 (65)
(65) Baxter Products manufactures office furniture by using an assembly-line process. All direct materials are introduced at the start of the process, and conversion cost is incurred evenly throughout manufacturing. An examination of the company's Work-in-Process account for August revealed the following selected information:
Debit side-
August 1 balance: 600 units, 40% complete; cost, $44,600*
Production started: 1,800 units
Direct materials used during August: $90,000
August conversion cost: $51,400
Credit side-
Production completed: 1,400 units
*Supplementary records disclosed direct material cost of $30,000 and conversion cost of $14,600.
Conversations with manufacturing personnel revealed that the ending work in process was 80% complete.
Required:
A. Determine the number of units in the August 31 work-in-process inventory.
B. Calculate the cost of goods completed during August, and prepare the appropriate journal entry to record completed production.
C. Determine the cost of the August 31 work-in-process inventory.
(Essay)
4.9/5 (73)
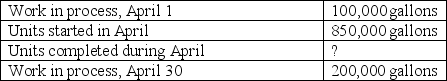
(73) 
Equivalent-unit calculations are necessary to allocate manufacturing costs between units sold and ending work in process.
(True/False)
4.8/5 (92)
(92) Use the following information to answer the following Questions
Lakeland Chemical manufactures a product called Zing. Direct materials are added at the beginning of the process, and conversion activity occurs uniformly throughout production. The beginning work-in-process inventory is 60% complete with respect to conversion; the ending work-in-process inventory is 20% complete. The following data pertain to May:
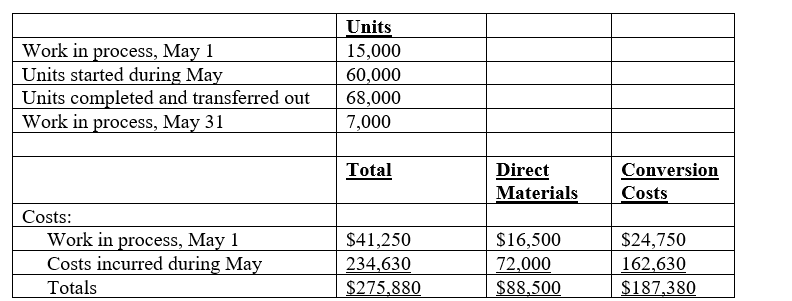 -Using the weighted-average method of process costing, the equivalent units of conversion activity total:
 (Multiple Choice)
4.7/5 (91)
(91) Covington Corporation uses a process-cost accounting system. The company adds direct materials at the start of its production process; conversion cost, on the other hand, is incurred evenly throughout manufacturing. The firm has no beginning work-in-process inventory; its ending work in process is 40% complete. Which of the following sets of percentages would be used to calculate the correct number of equivalent units in the ending work-in-process inventory?
(Multiple Choice)
4.9/5 (83)
(83) Harrington Industries, which uses a process-costing system, had a balance in its Work-in-Process account of $68,000 on January 1. The account was charged with direct materials, direct labor, and manufacturing overhead of $450,000 throughout the year. If a review of the accounting records determined that $86,000 of goods were still in production at year-end, Harrington should make a journal entry on December 31 that includes:
(Multiple Choice)
4.7/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)