



 Chat with AI
Exam 4: The Market Forces of Supply and Demand

Exam 1: Ten Principles of Economics220 Questions
Exam 2: Thinking Like an Economist284 Questions
Exam 3: Interdependence and the Gains From Trade192 Questions
Exam 4: The Market Forces of Supply and Demand277 Questions
Exam 5: Elasticity and Its Application222 Questions
Exam 6: Supply, Demand, and Government Policies321 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets218 Questions
Exam 8: Applications: The Costs of Taxation203 Questions
Exam 9: Application: International Trade214 Questions
Exam 10: Externalities204 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System225 Questions
Exam 13: The Costs of Production261 Questions
Exam 14: Firms in Competitive Markets243 Questions
Exam 15: Monopoly231 Questions
Exam 16: Monopolistic Competition246 Questions
Exam 17: Oligopoly204 Questions
Exam 18: The Markets for the Factors of Production232 Questions
Exam 19: Earnings and Discrimination230 Questions
Exam 20: Income Inequality and Poverty194 Questions
Exam 21: The Theory of Consumer Choice209 Questions
Exam 22: Frontiers in Microeconomics185 Questions
Exam 23: Measuring a Nations Income231 Questions
Exam 24: Measuring the Cost of Living214 Questions
Exam 25: Production and Growth187 Questions
Exam 26: Saving, Investment, and the Financial System225 Questions
Exam 27: Tools of Finance198 Questions
Exam 28: Unemployment and Its Natural Rate361 Questions
Exam 29: The Monetary System210 Questions
Exam 30: Money Growth and Inflation201 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts194 Questions
Exam 32: A Macroeconomic Theory of the Open Economy188 Questions
Exam 33: Aggregate Demand and Aggregate Supply189 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand207 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment223 Questions
Exam 36: Six Debates Over Macroeconomic Policy154 Questions
Select questions type


When the market price is below the equilibrium price, the quantity of the good demanded exceeds the quantity supplied.
(True/False)
4.9/5  (84)
(84) Figure 4-1 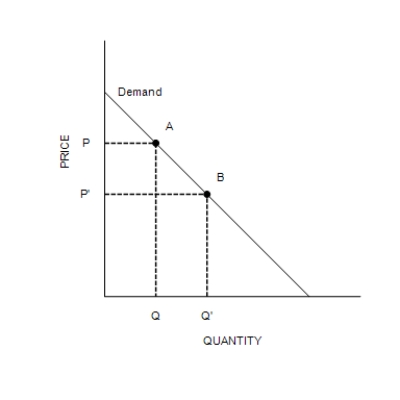
-Refer to Figure 4-1. It is apparent from the figure that the
-Refer to Figure 4-1. It is apparent from the figure that the (Multiple Choice)
4.8/5 (78)
(78) A likely example of substitute goods for most people would be
(Multiple Choice)
4.7/5 (76)
(76) Which of the following is not held constant in a demand schedule?
(Multiple Choice)
4.9/5 (75)
(75) All goods and services are sold in perfectly competitive markets.
(True/False)
4.9/5 (67)
(67) When the price of a good is high, selling the good is profitable, and so the quantity supplied is large.
(True/False)
5.0/5 (63)
(63) Suppose there is a flood in St. Louis, Missouri, that destroys several beer bottling facilities. Which of the following would not be a direct result of this event?
(Multiple Choice)
4.7/5 (76)
(76) A likely example of complementary goods for most people would be
(Multiple Choice)
4.9/5 (90)
(90) Which of the following would not increase in response to a decrease in the price of ironing boards?
(Multiple Choice)
4.9/5 (92)
(92) Figure 4-8 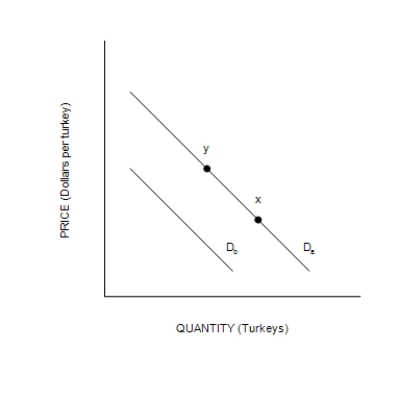 -Refer to Figure 4-8. All else equal, an increase in the income of buyers who consider turkey to be an inferior good would cause a move from
 (Multiple Choice)
4.9/5 (87)
(87) The demand curve is the upward-sloping line relating price and quantity demanded.
(True/False)
4.9/5 (77)
(77) Figure 4-13
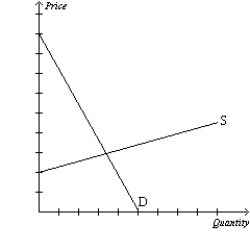
-If corn is an input into the production of ethanol, will a decrease in the price of corn increase the supply of ethanol or decrease the supply of ethanol?
-If corn is an input into the production of ethanol, will a decrease in the price of corn increase the supply of ethanol or decrease the supply of ethanol? (Short Answer)
4.8/5 (77)
(77) If orange juice and apple juice are substitutes, an increase in the price of orange juice will shift the demand curve for apple juice to the right.
(True/False)
4.7/5 (72)
(72) A decrease in the price of baseball bats will decrease the demand for baseballs.
(True/False)
4.9/5 (83)
(83) A movement upward and to the left along a given demand curve is called a decrease in demand.
(True/False)
4.7/5 (78)
(78) Table 4-9
The following table shows the supply and demand schedules in a market.
-Refer to Table 4-9. At a price of $8, how large of a surplus will there be in this market?
(Short Answer)
4.8/5 (74)
(74) An increase in supply will cause a decrease in price, which will cause an increase in demand.
(True/False)
4.8/5 (84)
(84) Individual supply curves are summed vertically to obtain the market supply curve.
(True/False)
4.9/5 (80)
(80) Table 4-2
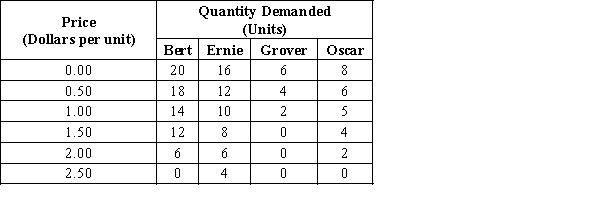
-Refer to Table 4-2. If these are the only four buyers in the market, then the market quantity demanded at a price of $1.50 is
-Refer to Table 4-2. If these are the only four buyers in the market, then the market quantity demanded at a price of $1.50 is (Multiple Choice)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)