



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics220 Questions
Exam 2: Thinking Like an Economist284 Questions
Exam 3: Interdependence and the Gains From Trade192 Questions
Exam 4: The Market Forces of Supply and Demand277 Questions
Exam 5: Elasticity and Its Application222 Questions
Exam 6: Supply, Demand, and Government Policies321 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets218 Questions
Exam 8: Applications: The Costs of Taxation203 Questions
Exam 9: Application: International Trade214 Questions
Exam 10: Externalities204 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System225 Questions
Exam 13: The Costs of Production261 Questions
Exam 14: Firms in Competitive Markets243 Questions
Exam 15: Monopoly231 Questions
Exam 16: Monopolistic Competition246 Questions
Exam 17: Oligopoly204 Questions
Exam 18: The Markets for the Factors of Production232 Questions
Exam 19: Earnings and Discrimination230 Questions
Exam 20: Income Inequality and Poverty194 Questions
Exam 21: The Theory of Consumer Choice209 Questions
Exam 22: Frontiers in Microeconomics185 Questions
Exam 23: Measuring a Nations Income231 Questions
Exam 24: Measuring the Cost of Living214 Questions
Exam 25: Production and Growth187 Questions
Exam 26: Saving, Investment, and the Financial System225 Questions
Exam 27: Tools of Finance198 Questions
Exam 28: Unemployment and Its Natural Rate361 Questions
Exam 29: The Monetary System210 Questions
Exam 30: Money Growth and Inflation201 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts194 Questions
Exam 32: A Macroeconomic Theory of the Open Economy188 Questions
Exam 33: Aggregate Demand and Aggregate Supply189 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand207 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment223 Questions
Exam 36: Six Debates Over Macroeconomic Policy154 Questions
Select questions type


Figure 7-14
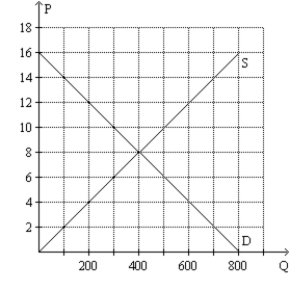
-Refer to Figure 7-14. Suppose there is initially a price floor set at $10 in this market. If the government removed the price floor, by how much would total consumer surplus increase for those consumers who were purchasing the good when the price floor was in place?
-Refer to Figure 7-14. Suppose there is initially a price floor set at $10 in this market. If the government removed the price floor, by how much would total consumer surplus increase for those consumers who were purchasing the good when the price floor was in place? (Essay)
4.9/5  (77)
(77) Which tools allow economists to determine if the allocation of resources determined by free markets is desirable?
(Multiple Choice)
4.9/5 (78)
(78) In a competitive market, sales go to those producers who are willing to supply the product at the lowest price.
(True/False)
4.9/5 (72)
(72) Answer each of the following questions about supply and producer surplus.
a.What is producer surplus, and how is it measured?
b.What is the relationship between the cost to sellers and the supply curve?
c.Other things equal, what happens to producer surplus when the price of a good rises? Illustrate your answer on a supply curve.
(Essay)
4.9/5 (83)
(83) Figure 7-10

-Refer to Figure 7-10. If the market equilibrium price falls from $120 to $80, how much is the change in total consumer surplus in the market?
-Refer to Figure 7-10. If the market equilibrium price falls from $120 to $80, how much is the change in total consumer surplus in the market? (Short Answer)
4.7/5 (86)
(86) Figure 7-14
-Refer to Figure 7-14. Suppose the government imposes a price floor at $10 per unit in this market. With the price floor, how much is total producer surplus assuming those producers with the lowest cost are the ones who supply the market?
-Refer to Figure 7-14. Suppose the government imposes a price floor at $10 per unit in this market. With the price floor, how much is total producer surplus assuming those producers with the lowest cost are the ones who supply the market? (Essay)
4.8/5 (79)
(79) Figure 7-5
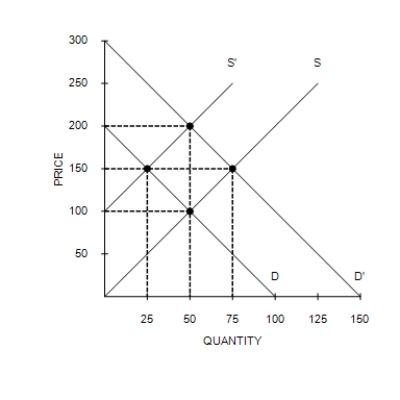 -Refer to Figure 7-5. If the supply curve is S and the demand curve shifts from D to D', what is the increase in producer surplus due to new producers entering the market?
 (Multiple Choice)
4.9/5 (96)
(96) What happens to consumer surplus in the smart watch market if smart watches are normal goods and income of the smart watch buyers falls?
(Multiple Choice)
4.8/5 (72)
(72) Table 7-8
Seller Cost (Dollars) Evan 50 Selena 100 Angie 150 Kris 200
-Refer to Table 7-8. If the sellers bid against each other for the right to sell the good to a consumer, then the good will sell for
(Multiple Choice)
4.8/5 (95)
(95) Table 7-5
Buyer Willingness to Pay (Dollars) Charisse 450 Keira 350 Eric 300 Earvin 250
-Refer to Table 7-5. You are selling extra tickets to the Midwest Regional Sweet 16 game in the men's NCAA basketball tournament. The table shows the willingness to pay of the four potential buyers in the market for a ticket to the game. Which of the following graphs represents the market demand curve?
(Multiple Choice)
4.9/5 (75)
(75) Given the following two equations:
Show how equation (1) can be used to derive equation (2).
1) Total Surplus = Consumer Surplus + Froducer Surplus
2) Total Surplus = Value to Buyers - Cost to Sellers
(Essay)
4.9/5 (77)
(77) Which of the following will cause an increase in producer surplus?
(Multiple Choice)
5.0/5 (74)
(74) Figure 7-1
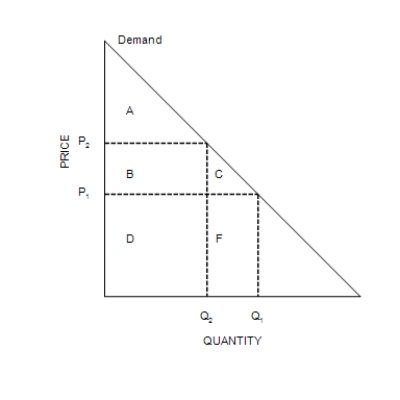 -Refer to Figure 7-1. Suppose that the price falls from P2 to P1. Area C represents the
 (Multiple Choice)
4.7/5 (82)
(82) A good weather in Spain results in good crop of oranges causing the prices of both oranges and orange juice to fall. As a result, the consumer surplus in the market for oranges
(Multiple Choice)
4.8/5 (81)
(81) Figure 7-12
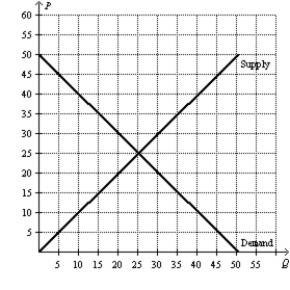
-Refer to Figure 7-12. At what price will total surplus be maximized in this market?
-Refer to Figure 7-12. At what price will total surplus be maximized in this market? (Essay)
4.8/5 (69)
(69) If the cost of producing chairs decreases causing the price of chairs to decrease, consumer surplus in the chair market will
(Multiple Choice)
4.7/5 (71)
(71) If producing a soccer ball costs Jake $5, and he sells it for $40, his producer surplus is $45.
(True/False)
4.9/5 (72)
(72) Larry purchases a book for $10, and his consumer surplus is $3. How much is Larry willing to pay for the book?
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)