



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics220 Questions
Exam 2: Thinking Like an Economist284 Questions
Exam 3: Interdependence and the Gains From Trade192 Questions
Exam 4: The Market Forces of Supply and Demand277 Questions
Exam 5: Elasticity and Its Application222 Questions
Exam 6: Supply, Demand, and Government Policies321 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets218 Questions
Exam 8: Applications: The Costs of Taxation203 Questions
Exam 9: Application: International Trade214 Questions
Exam 10: Externalities204 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System225 Questions
Exam 13: The Costs of Production261 Questions
Exam 14: Firms in Competitive Markets243 Questions
Exam 15: Monopoly231 Questions
Exam 16: Monopolistic Competition246 Questions
Exam 17: Oligopoly204 Questions
Exam 18: The Markets for the Factors of Production232 Questions
Exam 19: Earnings and Discrimination230 Questions
Exam 20: Income Inequality and Poverty194 Questions
Exam 21: The Theory of Consumer Choice209 Questions
Exam 22: Frontiers in Microeconomics185 Questions
Exam 23: Measuring a Nations Income231 Questions
Exam 24: Measuring the Cost of Living214 Questions
Exam 25: Production and Growth187 Questions
Exam 26: Saving, Investment, and the Financial System225 Questions
Exam 27: Tools of Finance198 Questions
Exam 28: Unemployment and Its Natural Rate361 Questions
Exam 29: The Monetary System210 Questions
Exam 30: Money Growth and Inflation201 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts194 Questions
Exam 32: A Macroeconomic Theory of the Open Economy188 Questions
Exam 33: Aggregate Demand and Aggregate Supply189 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand207 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment223 Questions
Exam 36: Six Debates Over Macroeconomic Policy154 Questions
Select questions type


Denis buys strawberries, and he would be willing to pay more than he now pays. Suppose that Denis has a change in his tastes such that he values strawberries more than before. If the market price is the same as before, then
(Multiple Choice)
4.8/5  (83)
(83) Table 7-4
For each of the three potential buyers of apples, the table displays the willingness to pay for Bob, Sasha, and Eric, who are the only three buyers of apples. Assume that only three apples can be supplied per day.
First Apple Second Apple Third Apple Bob 2.00 1.50 0.75 Sasha 1.50 1.00 0.60 Eric 0.75 0.25 0.00
-Refer to Table 7-4. The market quantity of apples demanded per day is exactly seven if the price of an orange, P, satisfies
(Multiple Choice)
5.0/5 (79)
(79) Figure 7-9
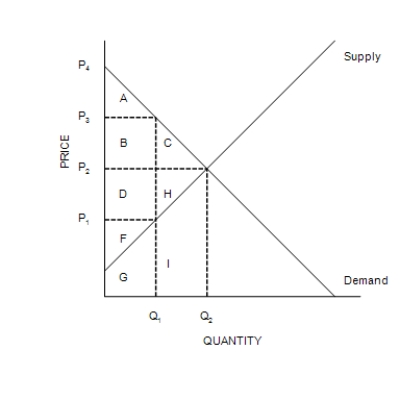 -Refer to Figure 7-9. At equilibrium, consumer surplus is represented by the area
 (Multiple Choice)
4.9/5 (89)
(89) Suppose the market demand curve for a good passes through the point (quantity demanded = 100, price = $25). If there are five buyers in the market, then
(Multiple Choice)
4.7/5 (84)
(84) Figure 7-5
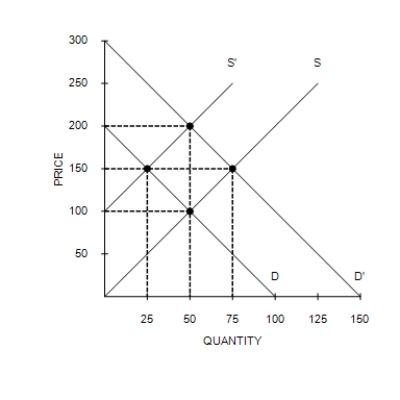 -Refer to Figure 7-5. If the supply curve is S and the demand curve shifts from D to D', what is the increase in producer surplus to existing producers?
 (Multiple Choice)
4.7/5 (84)
(84) Consumer surplus can be measured as the area between the demand curve and the supply curve.
(True/False)
4.8/5 (87)
(87) Each seller of a product is willing to sell as long as the price he or she can receive is greater than the opportunity cost of producing the product.
(True/False)
4.8/5 (77)
(77) Suppose there is an increase in supply that reduces market price. Consumer surplus increases because (1) consumer surplus received by existing buyers increases and (2) new buyers enter the market.
(True/False)
4.7/5 (76)
(76) Consumer surplus is the amount a buyer is willing to pay for a good minus the amount the buyer actually has to pay for it.
(True/False)
4.8/5 (77)
(77) Scenario 7-1
Suppose market demand is given by the equation
-Refer to Scenario 7-1. If the market equilibrium price falls from $10 to $5, how much consumer surplus do consumers entering the market after the price drop receive?
(Essay)
4.8/5 (83)
(83) When demand increases so that market price increases, producer surplus increases because (1) producer surplus received by existing sellers increases, and (2) new sellers enter the market.
(True/False)
4.7/5 (90)
(90) Table 7-7
Seller Cost (Dollars) Mike 1,600 Laura 1,300 Alex 1,200 David 900 Codi 700
-Refer to Table 7-7. Suppose each of the five sellers can supply at most one unit of the good. The market quantity supplied is exactly 2 if the price is
(Multiple Choice)
4.8/5 (88)
(88) Table 7-11
Price (Dollars per unit) Quantity Demanded (Units) Quantity Supplied (Units) 12.00 0 36 10.00 3 30 8.00 6 24 6.00 9 18 4.00 12 12 2.00 15 6 0.00 18 0
-Refer to Table 7-11. Both the demand curve and the supply curve are straight lines. If the price is $4 but only 6 units are bought and sold, consumer surplus will be
(Multiple Choice)
4.9/5 (89)
(89) Table 7-13
The following table shows the cost of producing a good for the only four producers in a market.
Producer Cost W \ 40 X \ 30 Y \ 20 Z \ 10
-Refer to Table 7-13. If the market price is $28, which producers will supply units in the market?
(Short Answer)
4.9/5 (80)
(80) On a graph, the area below a demand curve and above the price measures
(Multiple Choice)
4.9/5 (82)
(82) Table 7-14
-Refer to Table 7-14. How much is total surplus at the equilibrium price in this market?
(Essay)
4.7/5 (80)
(80) Figure 7-14
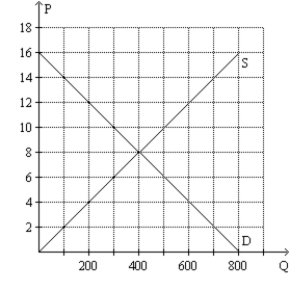
-Refer to Figure 7-14. Suppose the government imposes a price floor at $10 per unit in this market. With the price floor, how much is total consumer surplus?
-Refer to Figure 7-14. Suppose the government imposes a price floor at $10 per unit in this market. With the price floor, how much is total consumer surplus? (Essay)
4.8/5 (80)
(80) Suppose televisions are a normal good and buyers of televisions experience a decrease in income. As a result, consumer surplus in the television market
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)