



 Chat with AI
Exam 13: The Costs of Production

Exam 1: Ten Principles of Economics220 Questions
Exam 2: Thinking Like an Economist284 Questions
Exam 3: Interdependence and the Gains From Trade192 Questions
Exam 4: The Market Forces of Supply and Demand277 Questions
Exam 5: Elasticity and Its Application222 Questions
Exam 6: Supply, Demand, and Government Policies321 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets218 Questions
Exam 8: Applications: The Costs of Taxation203 Questions
Exam 9: Application: International Trade214 Questions
Exam 10: Externalities204 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System225 Questions
Exam 13: The Costs of Production261 Questions
Exam 14: Firms in Competitive Markets243 Questions
Exam 15: Monopoly231 Questions
Exam 16: Monopolistic Competition246 Questions
Exam 17: Oligopoly204 Questions
Exam 18: The Markets for the Factors of Production232 Questions
Exam 19: Earnings and Discrimination230 Questions
Exam 20: Income Inequality and Poverty194 Questions
Exam 21: The Theory of Consumer Choice209 Questions
Exam 22: Frontiers in Microeconomics185 Questions
Exam 23: Measuring a Nations Income231 Questions
Exam 24: Measuring the Cost of Living214 Questions
Exam 25: Production and Growth187 Questions
Exam 26: Saving, Investment, and the Financial System225 Questions
Exam 27: Tools of Finance198 Questions
Exam 28: Unemployment and Its Natural Rate361 Questions
Exam 29: The Monetary System210 Questions
Exam 30: Money Growth and Inflation201 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts194 Questions
Exam 32: A Macroeconomic Theory of the Open Economy188 Questions
Exam 33: Aggregate Demand and Aggregate Supply189 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand207 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment223 Questions
Exam 36: Six Debates Over Macroeconomic Policy154 Questions
Select questions type


A key difference between accountants and economists is their different treatment of the cost of capital. Does this cause an accountant's estimate of total costs to be higher or lower than an economist's estimate? Explain.
(Essay)
4.8/5  (75)
(75) Table 13-7
The following table shows the production costs for The Flying Elvis Copter Rides.
Output (Helicopter rides) Total Cost (Dollars) Fixed Cost (Dollars) Variable Cost (Dollars) Marginal Cost (Dollars) Average Fixed Cost (Dollars per ride) Average Variable Cost (Dollars per ride) Avera Total Cost (Dollars ride) 0 50 50 0 -- - - - 1 150 2 120 3 120
-Refer to Table 13-7. What is the value of D?
(Multiple Choice)
4.8/5 (77)
(77) Table 13-5
The following table shows the production and costs for the Wooden Chair Factory.
Labor (Number of workers) Capital (Number of machines) Output (Chairs produced per hour) Marginal Product of Labor (Chairs produced per hour) Cost of Workers (Dollars) Cost of Machines (Dollars Total Cost (Dollars) 1 2 5 2 2 10 3 2 20 4 2 35 5 2 55 6 2 70 7 2 80
-Refer to Table 13-5. Assume the Wooden Chair Factory currently employs 5 workers. What is the marginal product of labor when the factory adds a 6th worker?
(Multiple Choice)
4.9/5 (71)
(71) Diminishing marginal product exists when the production function becomes flatter as inputs increase.
(True/False)
4.8/5 (70)
(70) If a firm experiences constant returns to scale at all output levels, then its long-run average total cost curve would
(Multiple Choice)
4.9/5 (84)
(84) The marginal-cost curve intersects the average-total-cost curve at the minimum point of the marginal-cost curve.
(True/False)
4.8/5 (69)
(69) When average total cost is above marginal cost, average total cost is rising.
(True/False)
4.9/5 (85)
(85) In the short run, a firm that produces and sells house paint can adjust
(Multiple Choice)
4.9/5 (87)
(87) Table 13-2
Labor (Number of workers) Output (Units) Marginal Product (Units) 0 0 - 1 300 2 500 3 600 4 650
-Refer to Table 13-2. What is the marginal product of the first worker?
(Multiple Choice)
4.8/5 (73)
(73) Figure 13-3 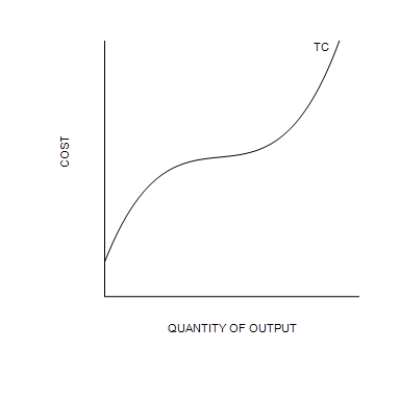 -Refer to Figure 13-3. Why doesn't the total cost curve begin at the origin (the point 0,0)?
 (Multiple Choice)
4.8/5 (85)
(85) In the short run, if a firm produces nothing, total costs are zero.
(True/False)
4.7/5 (91)
(91) Figure 13-6
The following figure depicts average total cost functions for a firm that produces automobiles. 
-Refer to Figure 13-6. At levels of output between P and Q, the firm experiences
-Refer to Figure 13-6. At levels of output between P and Q, the firm experiences (Multiple Choice)
4.9/5 (80)
(80) Figure 13-3
-Refer to Figure 13-3. Which of the following can be inferred from the figure above?
-Refer to Figure 13-3. Which of the following can be inferred from the figure above? (Multiple Choice)
4.9/5 (71)
(71) Describe how an accounting firm could experience economies of scale.
(Essay)
4.8/5 (71)
(71) If the average total cost curve is falling, what is necessarily true of the marginal cost curve? If the average total cost curve is rising, what is necessarily true of the marginal cost curve?
(Essay)
4.8/5 (85)
(85) Consider a small hair styling salon. List some examples of explicit costs of this business.
(Essay)
5.0/5 (98)
(98) Table 13-15
Labor Output Marginal Product Variable Cost Fixed Cost 0 0 - \ 0 \ 5 1 100 100 \ 5 \ 5 2 250 \ 10 \ 5 3 350 \ 15 \ 5 4 50 \ 20 \ 5 5 25 \ 25 \ 5 6 430 \ 30 \ 5
-Refer to Table 13-15. What is the shape of the average-variable-cost curve?
(Essay)
4.9/5 (90)
(90) Table 13-13
Listed in the table are the long-run total costs for three different firms.
uantity Firm A 100 100 100 100 100 Firm B 100 200 300 400 500 Firm C 100 300 600 1,000 1,500
-Refer to Table 13-13. Firm A is experiencing constant returns to scale.
(True/False)
4.8/5 (76)
(76) Consider a small hair styling salon. List some examples of implicit costs of this business.
(Essay)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)