



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


In determining taxable income for state income tax purposes, interest income from Federal bonds typically constitutes an)_________ modification.
(Short Answer)
4.9/5  (65)
(65) Typically exempt from the sales/use tax base is the purchase of clothing from a neighbor's garage sale.
(True/False)
5.0/5 (75)
(75) In determining a corporation's taxable income for state income tax purposes, which of the following does not constitute a subtraction modification from Federal income?
(Multiple Choice)
4.9/5 (89)
(89) _________describes) the degree of business activity that must be present before a taxing jurisdiction has the right to impose a tax on an out-of-state entity's income.
(Short Answer)
4.9/5 (87)
(87) Most states begin the computation of corporate taxable income with an amount from the Federal income tax return.
(True/False)
4.9/5 (82)
(82) The benefits of a passive investment company employed in a nonunitary state typically include:
(Multiple Choice)
4.7/5 (90)
(90) The most commonly used state income tax apportionment formula is:
(Multiple Choice)
4.9/5 (76)
(76) Simpkin Corporation owns manufacturing facilities in States A, B, and C. State A uses a three-factor apportionment formula under which the sales, property, and payroll factors are equally weighted. State B uses a three-factor apportionment formula under which sales are double-weighted. State C employs a single-factor apportionment factor, based solely on sales. Simpkin's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows: State A State B State C Totals Sales \ 400,000 \ 800,000 \ 300,000 \ 1,500,000 Payroll 100,000 150,000 50,000 300,000 Property 200,000 200,000 200,000 600,000 Simpkin's apportionable income assigned to State B is:
(Multiple Choice)
5.0/5 (82)
(82) By making a water's edge election, a multinational taxpayer can limit the reach of unitary principles to the apportionment factors and income of its U.S. and E.U. affiliates.
(True/False)
4.8/5 (74)
(74) Bert Corporation, a calendar year taxpayer, owns property in States M and O. Both states require that the average value of assets be included in the property factor. State M requires that the property be valued at its historical cost, and State O requires that the property be included in the property factor at its net depreciated book value. 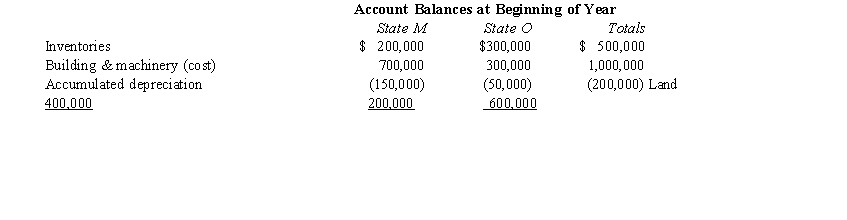
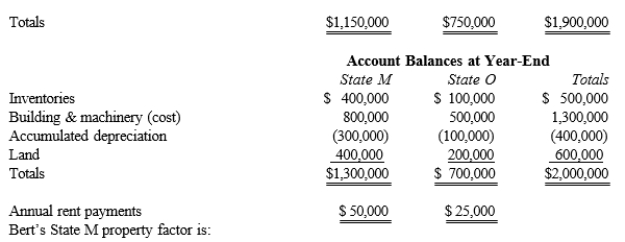
(Multiple Choice)
4.9/5 (91)
(91) Usually a business chooses a location where it will build a new plant based chiefly on tax considerations.
(True/False)
4.9/5 (97)
(97) Adams Corporation owns and operates two manufacturing facilities, one in State X and the other in State Y. Due to a temporary decline in the corporation's sales, Adams has rented 20% of its Y facility to an unaffiliated corporation. Adams generated $1,000,000 net rental income and $5,000,000 income from manufacturing. Adams is incorporated in Y. For X and Y purposes, rental income is classified as allocable nonbusiness income. By applying the statutes of each state, Adams determined that its apportionment factors are 0.65 for X and 0.35 for Y.
Adams's income attributed to X is:
(Multiple Choice)
4.7/5 (66)
(66) A taxpayer automatically has nexus with a state for sales and use tax purposes if it has income tax nexus with the same state.
(True/False)
4.8/5 (83)
(83) Double weighting the sales factor effectively decreases the corporate income tax burden on taxpayers based in a state such as entities with in-state headquarters.
(True/False)
5.0/5 (72)
(72) Hendricks Corporation sells widgets in two states. State A levies a 9% effective tax rate, and State B levies a 3% rate. A and B have adopted sales-factor-only apportionment formulas. To reduce overall multistate income tax liabilities, Hendricks should:
(Multiple Choice)
4.8/5 (84)
(84) If a gift card is unused after a specified period of time, the state can collect the amount of the card proceeds from the seller as ____________________ property.
(Short Answer)
4.9/5 (84)
(84) Helene Corporation owns manufacturing facilities in States A, B, and C. State A uses a three-factor apportionment formula under which the sales, property, and payroll factors are equally weighted. State B uses a three-factor apportionment formula under which sales are double-weighted. State C employs a single-factor apportionment factor based solely on sales. Helene's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows: State A State B State C Totals Sales \ 400,000 \ 800,000 \ 300,000 \ 1,500,000 Payroll 100,000 150,000 50,000 300,000 Property 200,000 200,000 200,000 600,000 Helene's apportionable income assigned to State A is:
(Multiple Choice)
4.8/5 (79)
(79) Match each of the following terms with the appropriate description in the state income tax formula. Apply the
UDITPA rules in your responses.
-State-level NOL.
(Multiple Choice)
4.9/5 (75)
(75) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its State A headquarters to a customer in State B. General has not established nexus with State B. State A does not apply a throwback rule. In which states) will the sale be included in the sales factor numerator?
(Multiple Choice)
4.8/5 (89)
(89) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its State A headquarters to a customer in State B. This activity is not sufficient for General to create nexus with State B. State A applies a throwback rule but State B does not. In which states) will the sale be included in the sales factor numerator?
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)